
Vroeg verkopen mogelijk
- Risiconiveau
- Hoogste
- Risico-rendement
- Zeer slecht
- Starten vanaf
- €5
Affiliatelink · kapitaal loopt risico
Bekijk 5 projecten →Vragen over beleggen? Vraag het de AI-gids.
Hallo! Ik ben de AI-gids van Crowdinform.
Log gratis in om de AI-gids vragen te stellen over platforms, projecten en uw plannen.
De AI antwoordt op basis van de gecontroleerde gegevens van Crowdinform. Hij kan fouten maken. Informatie, geen persoonlijk beleggingsadvies.
Even opzoeken… Er ging iets mis. Probeer het opnieuw. Vandaag nog {n} vragen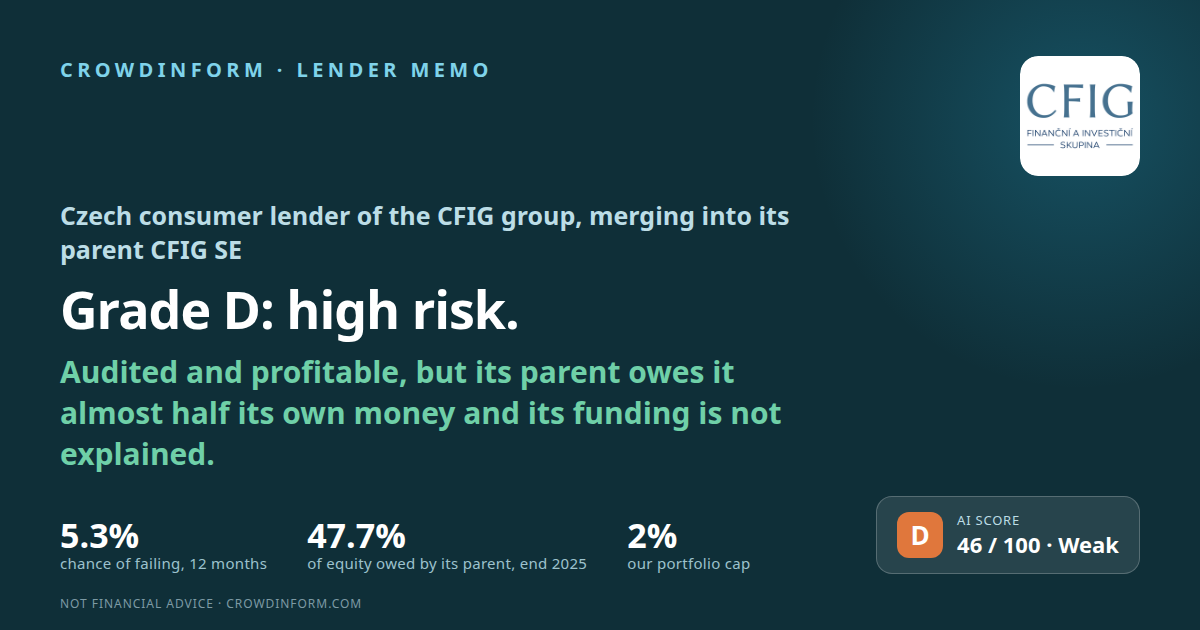
Tsjechië
Kapitaal loopt risico. De rente is afgesproken, niet gegarandeerd: als een lener in gebreke blijft, kunt u (een deel van) uw geld verliezen.
Onze AI geeft dit project 46 van de 100: Laag. Zo werkt de AI-score
Informatie, geen persoonlijk beleggingsadvies. De AI-score beoordeelt de documenten die het platform publiceert, kan onjuist zijn en voorspelt geen rendement.
Investments in CFIG loans on Bondster lead to CFIG Credit a.s. itself (IČO 09433635, Pardubice), a Czech non-bank consumer lender founded in 2020. Bondster’s CFIG page (dated 11 January 2023) says the company lends “completely online”, belongs to the CFIG group “which consists of 10 companies”, and offers investors “selected loans with verified clients, guaranteeing a buyback in case of repayment problems”. A buyback is the lender’s own promise to buy the investment back if the borrower is late; the page does not say after how many days. Bondster shows no score for CFIG. CFIG Credit is 0.08% of the money invested on Bondster (Bondster’s chart “Structure of investments by providers”, no date shown, read 20 November 2026); Bondster publishes no amount outstanding per lender that we could read. Its sole shareholder is CFIG SE, and CFIG Credit is merging into CFIG SE (merger project of 14 September 2026, not yet registered on 21 November 2026): once the merger is registered, CFIG SE will owe whatever CFIG Credit owes Bondster investors. We have not read CFIG SE’s accounts. Bondster is run by BONDSTER Marketplace s.r.o., Prague, which is not a bank and had negative equity at the end of 2025. This memo asks one question: what is the chance that CFIG Credit fails to pay in the next 12 months, and why.
We ask six questions about every lender: does it earn enough, are its loans being repaid, does it have enough of its own money to absorb losses, how risky is its country, can we trust its numbers, and are there warning signs. Each is scored 1 to 5 and weighted. The four cards show how they land. Together they give 46 out of 100, which means 6–15%, the range we show for a D; on our method the figure is about 5.3%, below that range. That figure is below the 6–15% range we show for a D, because the Czech Republic is a strong country; the grade itself comes from the score. D runs from 35 to 49, so the grade is D, 4 points below C and 11 above E. One step up on earnings (2 to 3) would give 52, a C; one step up on the loans or on the cushion would give exactly 50, also a C. No single step down reaches E: the lowest, earnings 2 to 1, gives 40. The answers to the open questions below, which we have not yet asked, could move it either way, and one of them could bring a veto.
Profit of CZK 17.0m in 2025 and 13.5m in 2024; in 2025 it held only because write-downs of bad loans fell from CZK 33.2m to 6.3m while costs rose; at the 2024 level, 2025 would have been a loss. Owners’ money CZK 295.6m, 36.2% of what it owns, or 21.4% once the CZK 140.9m its owner owes it is set aside. Cash CZK 3.6m.
The allowance for losses is 16% of the receivables we treat as its loans, but the accounts give no split by days overdue. By its policy a receivable gets no allowance until it is 18 months overdue. None of its receivables is secured.
It lends in the Czech Republic, grade B in our country memo: a strong economy and currency. The new cost cap on consumer credit from February 2027 applies to its kind of lending; on average its income and costs sit below the cap, but close to it on one reading of its accounts (section 3).
A clean audit; but the notes do not name who owes it CZK 657.0m or whom it owes CZK 165.8m, do not show where Bondster investors’ money sits, the company is being merged into its owner, and the register shows two board members against four in the notes at the end of 2025.
De volledige analyse behandelt de lener of het bedrijf, de zekerheid, de kasstroom, de risico's en een oordeel. Log in om deze te lezen.
Informatie, geen persoonlijk beleggingsadvies. De AI-score beoordeelt de documenten die het platform publiceert, kan onjuist zijn en voorspelt geen rendement.
Log in om de AI vragen te stellen over de documenten van dit project.
Inloggen👍 Ja · 0 👎 Nee · 0
Affiliatelink · kapitaal loopt risico
Bekijk 5 projecten →Mintos
Mintos
Reacties · 0