
Regulowana
Trwa bonus
Wcześniejsza sprzedaż
- Poziom ryzyka
- Wysoki
- Ryzyko a zwrot
- Średni
- Już od
- €50
Link polecający · ryzyko utraty kapitału
Zobacz projekty (42) →Pytania o inwestowanie? Zapytaj przewodnika AI.
Cześć! Jestem przewodnikiem AI Crowdinform.
Zaloguj się za darmo, aby pytać przewodnika AI o platformy, projekty i swoje plany.
Odpowiedzi pochodzą ze sprawdzonych danych Crowdinform. Informacja, a nie osobiste doradztwo inwestycyjne.
Szukam… Coś poszło nie tak. Spróbuj ponownie. Pozostałe pytania dziś: {n}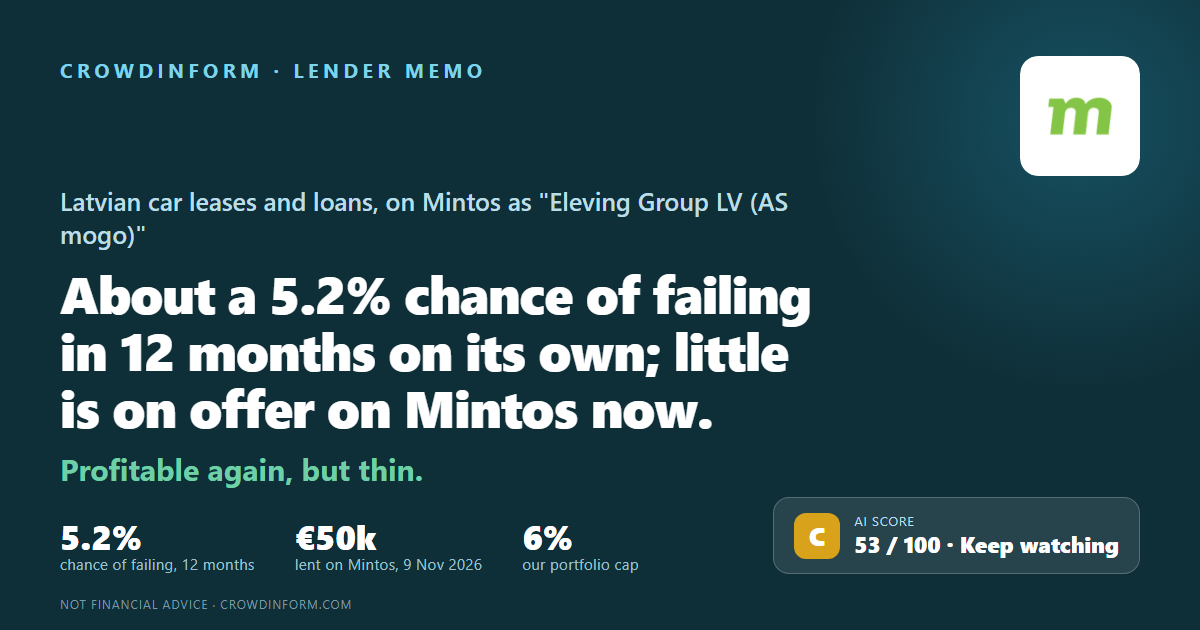
Łotwa
Ryzyko utraty kapitału. Oprocentowanie jest ustalone, ale nie gwarantowane: jeśli pożyczkobiorca nie spłaci zobowiązania, możesz stracić część lub całość swoich pieniędzy.
Nasza AI daje temu projektowi 53 na 100 punktów: Średnia. Jak działa ocena AI
Informacje, a nie osobiste doradztwo inwestycyjne. Ocena AI dotyczy dokumentów publikowanych przez platformę, może być błędna i nie przewiduje zysków.
AS mogo is a Latvian leasing company — car leases, car loans and instalment loans — and the original lender the Eleving group grew out of. It has 33 staff. Mintos investors lend to it through a Mintos company. This memo asks one question: what is the chance it fails to pay its lenders back in the next 12 months, and why. It replaces our memo of 13 September 2026, which scored it a D at 47 and described the parent's support as a letter of comfort. The prospectus shows it is a guarantee, and the score is now a C.
It has turned round, and the turn is small. AS mogo made €0.14m in 2025 after losing €0.97m in 2024. Of every €100 of income it kept €2.20 last year, against a loss of €24.88 the year before. Its loan book doubled, from €12.1m to €24.0m. Earnings covered interest only 1.12 times, and a fall of 2.9% in income would wipe out the year's pre-tax profit of €0.19m.
The cushion is not what the balance sheet first suggests. Owners' money is €22.2m — but €19.1m of that is shares in two sister companies, Primero Finance in Estonia and mogo rent, and both of those holdings are pledged to Eleving's bondholders. Take them out and what is left to absorb losses on a €24.0m loan book is about €3.1m.
And the funding is the group. 94% of its borrowing — €18.6m of €19.8m on the balance sheet — comes from companies in the same group, at 12%. The loans themselves are €18.4m; the rest is interest owed on them. It has had no bank or bond funding of its own since its Riga bonds were repaid in April 2024.
So the answer turns on Eleving, and Eleving has given a guarantee. The Mintos base prospectus of 27 March 2026 says that Eleving Group S.A. "guarantees the Lending Company's obligations towards the Issuer" — the Issuer being the Mintos company that holds these loans. Eleving is rated B by Fitch, outlook positive, affirmed 12 December 2025, and under our method that rating sets the odds: about 1 in 33. The guarantee runs to the Mintos company, not to you directly.
Support runs the other way too, and that one has no cap. AS mogo is one of 13 subsidiaries that jointly guarantee Eleving's bonds — €342.6m outstanding at the end of 2025, about 15 times its own equity — with pledges over its shares, receivables, trademarks and bank accounts. Latvian law sets no cap on such a guarantee. That is harmless while Eleving pays and decisive if it does not. If Eleving failed, its bondholders would be claiming on AS mogo alongside Mintos.
Six things would stop us scoring at all and send the answer straight to E — a default, a missed payment to a platform, a regulator pulling a licence, an auditor doubting the company can continue, a broken promise to a lender, or accounts we cannot rely on. None of them applies to this company. Two things would pull the answer the other way, a guarantee from a stronger owner or a credit rating. One of them does apply, and it is the only reason this memo gives a second number.
Back in profit: €0.14m in 2025 after a €0.97m loss. Interest covered only 1.12 times.
The book doubled to €24.0m; payments more than sixty days late fell to about 3.2% — partly because bad loans are sold.
Grade B (3.74 out of 5). The euro, and a cost cap that has not moved since 2019. The 3 October election returned the incumbent.
Funded 94% by the group, and guarantees €342.6m of Eleving bonds with no legal cap.
Every investment carries risk, and risk is not really a letter or a mark out of ten. It is two plain questions: how likely is it that this company fails, and how much of your money would you lose if it did. Put those together and you can see whether the reward is worth it.
For AS mogo: Mintos showed an average investor rate of 13.99% a year on 9 November 2026, on the little still outstanding. On our reading the chance of the company behind it failing in the next twelve months is about 3.0% — the parent's number, because of the guarantee. If about 1 in 33 lenders like this one fail in a year and about 70% of the money is gone when they do, the risk costs about 2.1% a year, and about 11.9% is left once the risk is paid for. On the company's own number instead of the parent's, the risk cost would be about 3.6% and about 10.4% would be left. That is our arithmetic on our own scale, and you are entitled to disagree with the scale; what you should not do is read the 13.99% on its own.
The group funds it, guarantees it, owns it — and it guarantees the group back without a cap. Reading AS mogo as a separate Latvian company is the main way to get this wrong.
Half of this loan book was written in 2025. Loans go bad in their second year, not their first, so arrears of about 3.2% are a promise rather than a record.
Nearly all of it is shares in two sister lenders, and those are pledged elsewhere. About €3.1m is what actually stands behind the lending.
Founded in 2012 and the original car lender the Eleving group grew from. 33 staff on the 2025 filing.
Of a €24.0m gross book at the end of 2025: leasing €12.6m, car loans €5.7m, instalment loans €5.6m — which add to €23.9m, a tenth short of the total, because each is rounded. The last of the three has no car behind it.
From €12.1m to €24.2m gross. Income of €6.5m, profit of €0.14m.
All of it, within Eleving Group S.A. of Luxembourg — rated B by Fitch, outlook positive. AS mogo in turn owns Primero Finance OÜ and AS "mogo rent".
The notes are issued by SIA Mintos Finance No. 1. You do not lend to AS mogo directly.
Outstanding on 9 November 2026 (€50,034), on the platform's own figure. On 13 September 2026 it showed €6.4m, and a printout taken the same day €7.3m. See the update at the top.
The average investor rate shown on 9 November 2026. Buyback varies by note series, and Eleving Group guarantees AS mogo's obligations to the Mintos company.
Updated 9 October 2026 and read on 9 November 2026 (9.3 in July) — a high score. That is Mintos's number, not ours, and we have not checked how it is built.
Pełna analiza obejmuje pożyczkobiorcę lub spółkę, zabezpieczenie, przepływy pieniężne, ryzyka i werdykt. Zaloguj się, aby ją przeczytać.
Informacje, a nie osobiste doradztwo inwestycyjne. Ocena AI dotyczy dokumentów publikowanych przez platformę, może być błędna i nie przewiduje zysków.
Zaloguj się, aby zapytać AI o dokumenty tego projektu.
Zaloguj się👍 Tak · 0 👎 Nie · 0
Link polecający · ryzyko utraty kapitału
Zobacz projekty (42) →Mintos
Mintos
Mintos