
Regulowana
Trwa bonus
Wcześniejsza sprzedaż
- Poziom ryzyka
- Wysoki
- Ryzyko a zwrot
- Średni
- Już od
- €50
Link polecający · ryzyko utraty kapitału
Zobacz projekty (42) →Pytania o inwestowanie? Zapytaj przewodnika AI.
Cześć! Jestem przewodnikiem AI Crowdinform.
Zaloguj się za darmo, aby pytać przewodnika AI o platformy, projekty i swoje plany.
Odpowiedzi pochodzą ze sprawdzonych danych Crowdinform. Informacja, a nie osobiste doradztwo inwestycyjne.
Szukam… Coś poszło nie tak. Spróbuj ponownie. Pozostałe pytania dziś: {n}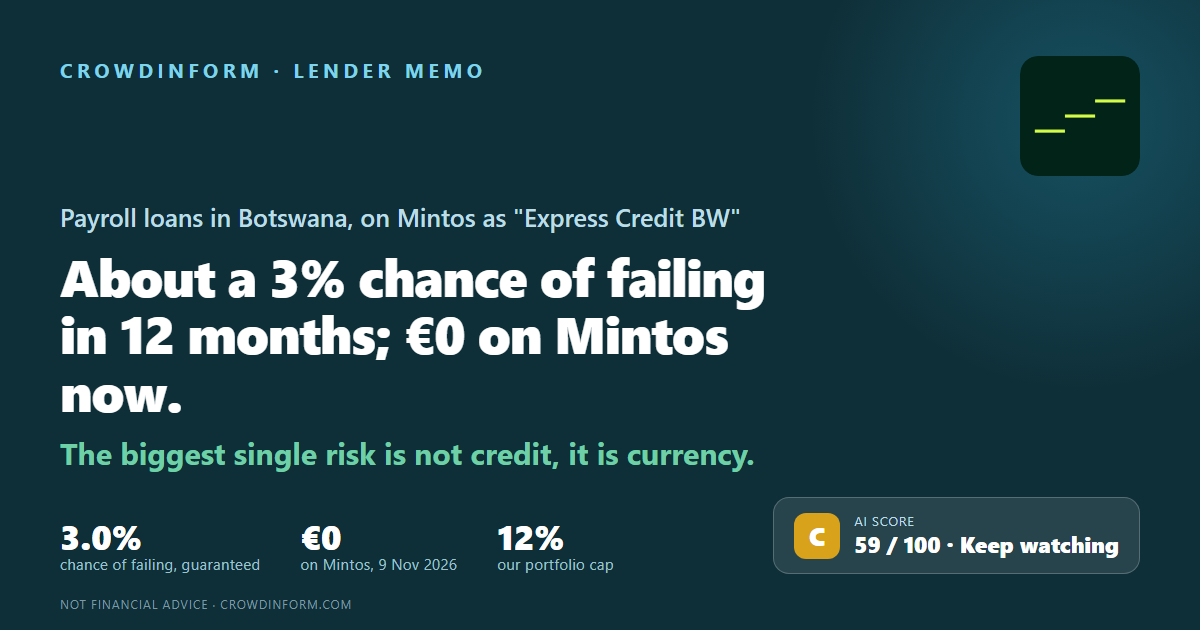
Botswana
Ryzyko utraty kapitału. Oprocentowanie jest ustalone, ale nie gwarantowane: jeśli pożyczkobiorca nie spłaci zobowiązania, możesz stracić część lub całość swoich pieniędzy.
Nasza AI daje temu projektowi 59 na 100 punktów: Średnia. Jak działa ocena AI
Informacje, a nie osobiste doradztwo inwestycyjne. Ocena AI dotyczy dokumentów publikowanych przez platformę, może być błędna i nie przewiduje zysków.
This memo answers one question: the chance that ExpressCredit (Proprietary) Limited — the Botswana payroll lender Mintos investors lend to — fails to pay its lenders in the next 12 months, and why. It replaces our memo of 14 September 2026. The grade is unchanged, but two documents have since been read that change what stands behind it in both directions.
What it does is simple and it works. It lends to people whose employer deducts the repayment from their pay — mostly Botswana government employees — in amounts from P2,000 to P500,000, averaging P38,920 over 44 months. The book grew 65% in 2025 to P508.3m, and defaulted loans fell from 13.5% of it to 7.9%, with 89% of them provided for.
The profit halved while it grew, and the reason is on the page. It kept 5.47 pula of every 100 in 2023, 27.67 in 2024 and 13.23 in 2025. 2024 was the unusual year, not 2025: bad debts were abnormally low and the money was cheap. In 2025 bad debts went back to normal and the interest bill rose to 28.08 pula of every 100 as its parent's euro loan replaced cheaper funding.
The biggest single risk is not credit, it is currency. It borrows in euros from its parent and lends in pula. The net short position was P270.5m at the end of 2025 — 2.34 times owners' money, against P26.6m a year earlier. Its own accounts say a fifth fall in the pula would cost P54.1m, which would turn 2025's P25.7m of pre-tax profit into a loss of about P28.4m. The only hedge disclosed expired on 26 March 2026.
Two arrangements run in opposite directions, and both were confirmed since our last memo. For a lender on the platform, Eleving Group S.A. guarantees this company's obligations to the Mintos issuer — which is why there are two numbers above. Against it, ExpressCredit has pledged its shares, receivables, trademarks and bank accounts to secure its parent's €270.0m of bonds. Its own accounts mention neither.
Six things would stop us scoring at all and send the answer straight to E — a default, a missed payment to a platform, a regulator pulling a licence, an auditor doubting the company can continue, a broken promise to a lender, or accounts we cannot rely on. None of them applies. One came close: in 2025 the owner took back more than the year’s profit, and a second such year would be a veto on its own. Two things would pull the answer the other way, a guarantee from a stronger owner or a credit rating. One of them applies. Eleving Group S.A. guarantees this company’s obligations to the Mintos issuer, and the parent’s odds are better than its own — so the page carries two numbers, and the better one is the one that counts for a lender on that platform.
Kept 13.23 pula of every 100 in 2025, down from 27.67. Interest covered 1.61 times after bad debts.
Defaulted loans 7.9% of the book, 89% provided for. Repayments come out of the payroll.
3.23 out of 5. Its borrowers are paid by a government short of money, and the pula is designed to fall.
74% of its borrowing is one euro loan from its parent; it has pledged its assets for that parent's bonds.
Every investment carries risk, and risk is not really a letter or a mark out of ten. It is two plain questions: how likely is it that this company fails, and how much of your money would you lose if it did. Put those together and you can see whether the reward is worth it.
For ExpressCredit the sum looks like this. The odds that count on the platform are 3.0% — about 1 in 33 — because the guarantee is given to the company that issues the notes. If a lender fails, our house assumption is that about 70% of the money is lost, so the risk costs about 2.1% a year. The average rate offered was 8.38% in September 2026, when notes were on offer, which leaves about 6.3% once the risk is paid for. Without the guarantee the same sum starts from 4.0%, and that is the number to use if you think the parent would not pay.
Our method lets a confirmed guarantee from a stronger owner set the odds and the limit. It does not change the grade, because the grade describes the company — and the company is the same one either way.
The prospectus says the guarantor "is not guaranteeing Mintos or the Issuer's obligations towards the Investors". It stands behind ExpressCredit's promises to the Mintos company. That is worth a great deal and it is not the same as a promise to you.
Botswana's pula is set to slide about 2.76% a year by policy. On a P270.5m gap that is roughly 29% of a year's pre-tax profit, every year, with no crisis required.
Regulated by NBFIRA, incorporated on 22 December 2015. 16 branches and more than 155 sales agents.
Unsecured, P2,000 to P500,000, averaging P38,920 over 44 months. Most borrowers are paid by the government.
About €29.67m net at the end of 2025, after growing 65% in the year; €29.9m at June 2026 on its parent's figures.
A Luxembourg group rated B with a positive outlook, affirmed in December 2025. It is also this company's largest lender and its guarantor on the platform.
Listed as "Express Credit BW", with the notes issued by SIA Mintos Finance No. 8.
Read on 9 November 2026 — Mintos's own figure, not independently checked. It showed €1.3m on 13 September 2026. On the group's figures it was nil at the end of 2025 and €0.8m in June and at 30 September 2026 — the platform is a small part of its funding.
As read on 13 September 2026; on 9 November 2026 Mintos showed no average rate, because nothing was outstanding. With a buyback, the loans ceded in security to the issuer, and the parent's guarantee to that issuer.
Mintos, updated 9 October 2026, read on 9 November 2026 — a platform figure. Its parts: loans performing 7.4, collections 7.8, buyback 9.3, structure 5.7. It was 7.9 in September. Its published update history is in two names — the last entry under "ExpressCredit BW" is from December 2023, and there are 2025 entries under "Eleving Group (BW)". We could not establish from the platform whether that is this listing renamed.
Pełna analiza obejmuje pożyczkobiorcę lub spółkę, zabezpieczenie, przepływy pieniężne, ryzyka i werdykt. Zaloguj się, aby ją przeczytać.
Informacje, a nie osobiste doradztwo inwestycyjne. Ocena AI dotyczy dokumentów publikowanych przez platformę, może być błędna i nie przewiduje zysków.
Zaloguj się, aby zapytać AI o dokumenty tego projektu.
Zaloguj się👍 Tak · 0 👎 Nie · 0
Link polecający · ryzyko utraty kapitału
Zobacz projekty (42) →Mintos
Mintos
Mintos