
Regulowana
Trwa bonus
Wcześniejsza sprzedaż
- Poziom ryzyka
- Wysoki
- Ryzyko a zwrot
- Średni
- Już od
- €50
Link polecający · ryzyko utraty kapitału
Zobacz projekty (42) →Pytania o inwestowanie? Zapytaj przewodnika AI.
Cześć! Jestem przewodnikiem AI Crowdinform.
Zaloguj się za darmo, aby pytać przewodnika AI o platformy, projekty i swoje plany.
Odpowiedzi pochodzą ze sprawdzonych danych Crowdinform. Informacja, a nie osobiste doradztwo inwestycyjne.
Szukam… Coś poszło nie tak. Spróbuj ponownie. Pozostałe pytania dziś: {n}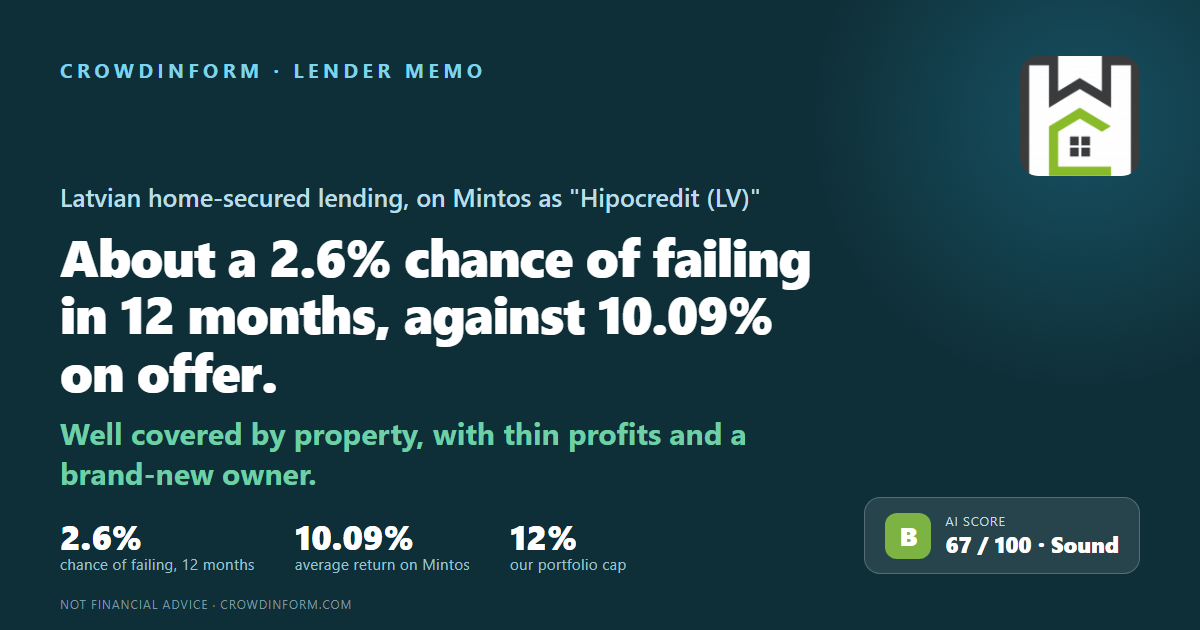
Łotwa
Ryzyko utraty kapitału. Oprocentowanie jest ustalone, ale nie gwarantowane: jeśli pożyczkobiorca nie spłaci zobowiązania, możesz stracić część lub całość swoich pieniędzy.
Nasza AI daje temu projektowi 67 na 100 punktów: Średnia. Jak działa ocena AI
Informacje, a nie osobiste doradztwo inwestycyjne. Ocena AI dotyczy dokumentów publikowanych przez platformę, może być błędna i nie przewiduje zysków.
AS Hipocredit lends money to people in Latvia against their homes. Every loan has a first mortgage, and the homes behind the loans are worth about two and a half times what the borrowers owe. Investors reach it through Mintos, where it is listed as Hipocredit (LV). This memo asks one question: what is the chance that AS Hipocredit fails to pay the people who lend to it in the next 12 months, and why.
The collateral is the strength here. Every loan is secured by a first mortgage registered in the Latvian Land Register, and on average a borrower owes 39% of what the property is worth. A home could lose more than half its value before the loan itself was at risk. The company says it has never lost principal. But 2025 brought its first large bad loan: one large borrower went insolvent, and €346,852 was set aside against seven doubtful loans.
The weakness is how little is left over. Of every €100 of income in 2025, 52.16 went to its own lenders as interest and fees, and 8.90 was left as profit — down from 22.72 a year earlier. Profit fell from €0.55m to €0.20m while income fell 5%. The audited accounts confirm those figures and explain them: fewer new loans, and more money set aside for bad debts.
And almost everything about the ownership changed in July. The company was sold on 16 July 2026, has a new board, and issued a new unsecured bond in August. None of that is in the 2025 figures, which RSM Latvia audited with a clean opinion and no warning about the business continuing.
Four things decide the score, and the loan book is what holds it up:
Profitable in every year shown, but profit fell to €0.20m, mostly from bad debts, and earnings covered the interest bill only 1.26 times.
Every loan backed by a first mortgage; borrowers owe 39% of the property's value on average; no principal lost so far. But seven doubtful loans needed three-quarters set aside in 2025, and the arrears split is from the end of 2023.
The euro, so no currency risk, and a land register that works. A caretaker government since May 2026 and an election in October.
Sold to a new owner in July 2026, new board, a new unsecured bond — and two changes of board chair between September 2025 and January 2026.
Every investment carries risk, and risk is not really a letter or a mark out of ten. It is two plain questions: how likely is it that this company cannot pay, and what would you get back if it could not. This memo answers the first. The second depends on the property behind each loan, and on how long a Latvian court takes.
A 1 in 39 chance of failing to pay in a year is not a promise about any single loan. It is our estimate for the company as a whole, on the figures we could read.
Slices of loans to people in Latvia, each secured by a first mortgage on a home.
€2.50m of owners' money, 14.5% of everything the company owns, plus €420,000 paid in during 2026.
Not a fall in house prices — the cover is wide. It is the thin margin: a 13.7% fall in income wipes out the pre-tax profit.
Licence NK-2016-012 from the Consumer Rights Protection Centre since 29 August 2016. Active, with no sanctions listed.
An office in Riga and 8 staff, lending across the country.
First mortgages, mainly on flats. Borrowers owe 39% of the value on average, 69% at most.
At December 2025, down 8% over the year, on income of €2.28m.
Listed as "Hipocredit (LV)". The present structure dates from October 2016.
Mintos's own figure, read on 9 November 2026, not independently verified.
The rate on its Mintos loans, from the 2025 audited notes. Mintos shows an average return of 10.09% (read on 9 November 2026); we could not reconcile the two.
A 60-day buyback, and commercial pledges of up to €20m and €4m given to Mintos.
Pełna analiza obejmuje pożyczkobiorcę lub spółkę, zabezpieczenie, przepływy pieniężne, ryzyka i werdykt. Zaloguj się, aby ją przeczytać.
Informacje, a nie osobiste doradztwo inwestycyjne. Ocena AI dotyczy dokumentów publikowanych przez platformę, może być błędna i nie przewiduje zysków.
Zaloguj się, aby zapytać AI o dokumenty tego projektu.
Zaloguj się👍 Tak · 0 👎 Nie · 0
Link polecający · ryzyko utraty kapitału
Zobacz projekty (42) →Mintos
Mintos
Mintos