
Regolamentata
Bonus attivo
Vendita anticipata
- Livello di rischio
- Alto
- Rischio-rendimento
- Medio
- Inizia da
- €50
Link di affiliazione · capitale a rischio
Vedi 42 progetti →Domande sugli investimenti? Chiedi alla guida IA.
Ciao! Sono la guida IA di Crowdinform.
Accedi gratis per fare domande alla guida IA su piattaforme, progetti e i tuoi piani.
Le risposte provengono dai dati verificati di Crowdinform. Informazione, non consulenza personalizzata sugli investimenti.
Sto cercando… Qualcosa è andato storto. Riprova. {n} domande rimaste oggi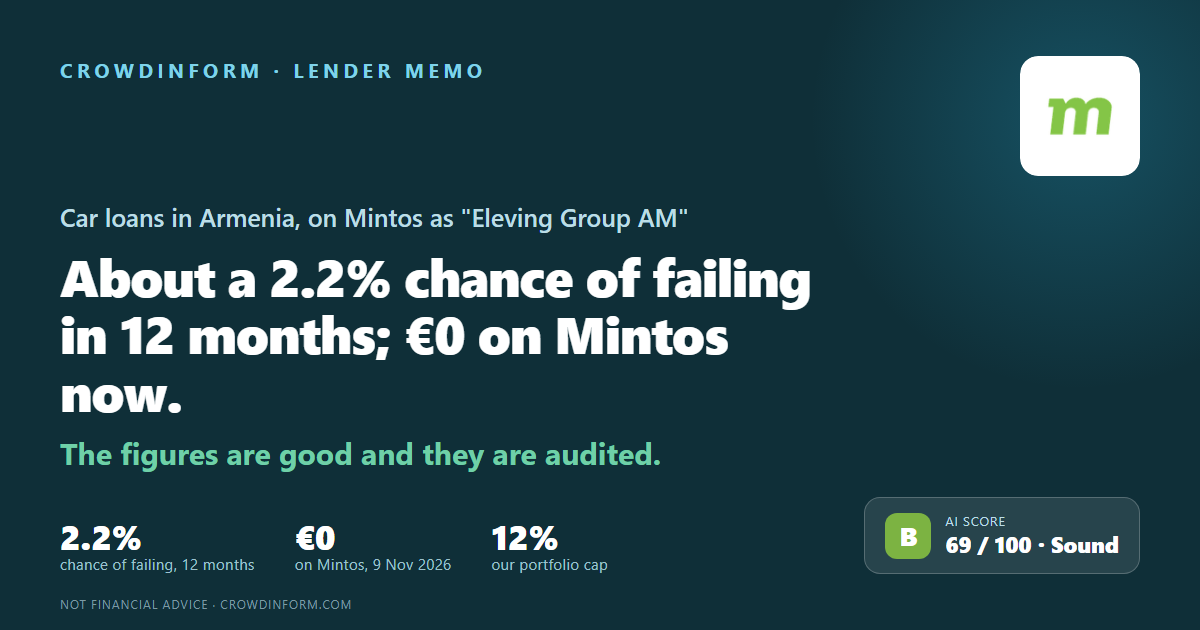
Armenia
Capitale a rischio. Il tasso è concordato, non garantito: se un debitore è inadempiente puoi perdere una parte o la totalità del tuo denaro.
La nostra IA assegna a questo progetto 69 su 100: Medio. Come funziona il punteggio IA
Informazioni, non consulenza personalizzata in materia di investimenti. Il punteggio IA valuta i documenti pubblicati dalla piattaforma, può essere sbagliato e non prevede i rendimenti.
This memo answers one question: the chance that "MOGO" Universal Credit Organization LLC — Eleving Group's Armenian car lender, whose notes Mintos investors buy — fails to pay its lenders in the next 12 months, and why. The platform lists it as "Eleving Group AM"; the accounts, the licence and the loan contracts all say MOGO. It replaces our memo of 14 September 2026, which graded it on the 2024 accounts.
The figures are good and they are audited. It kept 29.75 drams of every 100 of income in 2025 — AMD 1.23bn, about €2.81m — after 41.71 in 2024 and 22.19 in 2023. Owners' money is €13.8m, 59% of everything it holds, against €9.5m of debts, and no dividend has been paid in three years. Interest was covered 7.1 times.
Nothing is lent to the group — the flow runs the other way, and that is the thing to watch. The management fee the group charges, with the tax on it that cannot be recovered, rose 38% to AMD 752m (€1.72m) in 2025 — 61% of the year's profit. Group companies charged AMD 830m in all. It is disclosed and it is legal; it is also money that leaves before any lender is paid.
Profit fell 14.1% in 2025, and the reasons are visible rather than hidden. Running costs rose 17%, a currency loss of AMD 197m replaced 2024's AMD 141m gain, and bad debts turned back into a cost — AMD 0.15bn — after two years in which old provisions were released and flattered the result.
One administrative fact matters more than it looks. Every Mintos base prospectus for these notes is marked expired — the last one, of 28 August 2025, was valid for up to twelve months and no replacement was listed when we checked. Existing notes carry on; new ones need a new prospectus. Investors had €4.3m here on 13 September 2026; on 9 November 2026 Mintos showed nothing outstanding, after Eleving repaid its Mintos borrowing (see the update at the top).
Six things would stop us scoring at all and send the answer straight to E — a default, a missed payment to a platform, a regulator pulling a licence, an auditor doubting the company can continue, a broken promise to a lender, or accounts we cannot rely on. None of them applies, on the company’s own audited accounts. Two things would pull the answer the other way, a guarantee from a stronger owner or a credit rating. One of them exists — its parent group guarantees this company’s obligations to the Mintos companies — but this company’s own odds are already better than its parent’s, so the guarantee confirms the answer rather than improving it, and there is no second number on this page.
AMD 1.23bn of profit, €13.8m of owners' money at 59% of assets, interest covered 7.1 times.
17.35% of the car book is in default, down from 21.27% — while new car lending grew 48%.
2.71 out of 5. Fast growth and a strong dram, with borrowers taking on debt faster than their incomes rise.
The group fee above, a guarantee of its parent's bonds, and a tax audit that is still open.
Every investment carries risk, and risk is not really a letter or a mark out of ten. It is two plain questions: how likely is it that this company fails, and how much of your money would you lose if it did. Put those together and you can see whether the reward is worth it.
For Mogo Armenia the sum looks like this. Our odds are 2.2% — about 1 in 45. If a lender fails, our house assumption is that about 70% of the money is lost, so the risk costs about 1.5% a year. The average rate on the platform was 9.22% in September 2026, when notes were on offer, which leaves about 7.7% once the risk is paid for. That is one of the wider margins in this series — and the reason to read the rest of the page is that the things most likely to narrow it are decisions the parent makes, not the Armenian business.
The parent guarantees this company to the platform's companies. Our method takes the better of the two sets of odds — and here the subsidiary's are better than the parent's, so the guarantee changes nothing. It would matter at a weaker company.
In 2023 and 2024 bad debts gave money back rather than costing it, because old provisions were recovered. That flattered both years. 2025 is the first recent year where the charge is a cost again, and it is the fairer picture.
It stops new notes being issued; it does not touch the ones already out, and it says nothing about whether the company pays. Worth watching precisely because it is easy to mistake for something worse.
Central Bank of Armenia licence number 42, held since 23 June 2017. 8 branches and 79 staff on average in 2025.
At an average effective rate of 53.7% a year on the book, most of it fees rather than interest. Plus an old payday book that has been written down.
About €30.4m gross at the end of 2025; €21.2m after provisions.
A Latvian company inside Eleving Group S.A. The group values this Armenian business at €22.8m, discounting its future cash at 32.5%.
Listed as "Eleving Group AM"; the notes are issued by SIA Mintos Finance No. 1 and the loans pledged to a separate Mintos company.
Read on 9 November 2026 — Mintos's own figure, not independently checked. It showed €4.3m on 13 September 2026; the group reported €4.3m for Armenia at June 2026 and €2.4m at 30 September 2026.
As read on 13 September 2026; on 9 November 2026 Mintos showed no average rate, because nothing was outstanding. With a buyback, the receivables pledged to the lending company, and the parent group's guarantee to that company.
Mintos, updated 9 October 2026, read on 9 November 2026 — a platform figure. Its parts: loans performing 9.4, collections 8.1, buyback 9.3, structure 4.5. It was 8.7 in July.
L'analisi completa copre il debitore o l'azienda, la garanzia, i flussi di cassa, i rischi e un verdetto. Accedi per leggerla.
Informazioni, non consulenza personalizzata in materia di investimenti. Il punteggio IA valuta i documenti pubblicati dalla piattaforma, può essere sbagliato e non prevede i rendimenti.
Accedi per fare domande all'IA sui documenti di questo progetto.
Accedi👍 Sì · 0 👎 No · 0
Link di affiliazione · capitale a rischio
Vedi 42 progetti →Mintos
Mintos