
Vroeg verkopen mogelijk
- Risiconiveau
- Hoogste
- Risico-rendement
- Zeer slecht
- Starten vanaf
- €10
Vragen over beleggen? Vraag het de AI-gids.
Hallo! Ik ben de AI-gids van Crowdinform.
Log gratis in om de AI-gids vragen te stellen over platforms, projecten en uw plannen.
Antwoorden komen uit de gecontroleerde gegevens van Crowdinform. Informatie, geen persoonlijk beleggingsadvies.
Even opzoeken… Er ging iets mis. Probeer het opnieuw. Vandaag nog {n} vragen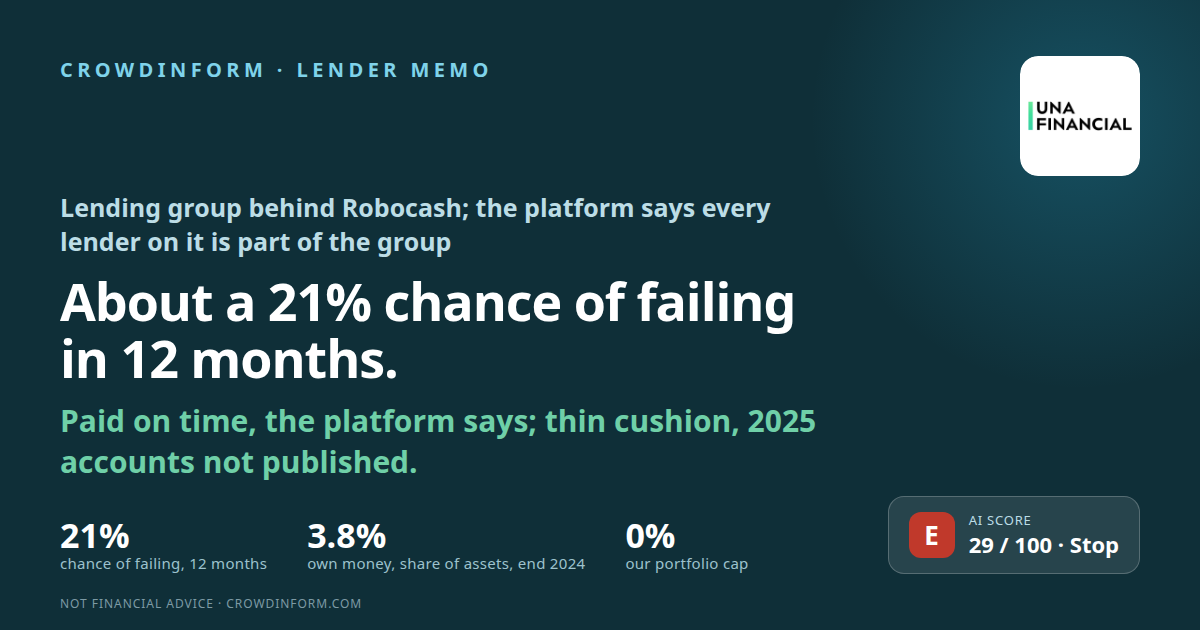
Singapore
Kapitaal loopt risico. De rente is afgesproken, niet gegarandeerd: als een lener in gebreke blijft, kunt u (een deel van) uw geld verliezen.
Onze AI geeft dit project 29 van de 100: Laag. Zo werkt de AI-score
Informatie, geen persoonlijk beleggingsadvies. De AI-score beoordeelt de documenten die het platform publiceert, kan onjuist zijn en voorspelt geen rendement.
Loans listed as “RC Bucharest (Robocash SG)” on Robocash lead to UnaFinancial Group: the Romanian vehicle ROBOCASH BUCHAREST S.R.L. sells investors claims on loans it gives to the group “through its ultimate holding company Robocash PTE. LTD.” (the platform’s words). On 16 November 2026 these were 94.5% of the platform’s active loans by number (672,188 of 711,130); Big Loan (Fingertip Finance Corp., Philippines, which the platform says is part of the same group) was the other 5.5%. The platform shows an outstanding portfolio of €69.3m in total and no euro amount per lender. Its lender page also lists “RC Bucharest (Kazakhstan)”; the statistics showed no active loans under that name. This memo is therefore about the group as a whole: Robocash PTE. LTD., Singapore, and its subsidiaries, consolidated. Its statements for 2021–22 call it Robocash Group; those for 2023 say “formerly Robocash Group”. The buyback after 30 days of delay is the promise of the “Lender” (User Agreement, clause 6.9), which for these loans is the Romanian vehicle as far as the platform’s page shows; the Assignment Agreement that names the parties is not public and we have not read it. It is not the platform’s promise. The platform’s own footer says: “Robocash is not regulated under any financial services license.” The platform says that “all loan originators on the platform belong to the same group”, and the group’s statements list the platform’s operator, Robocash d.o.o. (Croatia), among its subsidiaries. In plain words: as far as the published pages show, nobody independent stands between the investor and the group. The company that sells the claim and promises to buy it back, the company that borrows the money and the platform that reports on all of them are, by the platform’s account, parts of one group. Who owns the Romanian vehicle we could not confirm. This memo asks one question: what is the chance that the group fails to pay in the next 12 months, and why.
We ask six questions about every lender: does it earn enough, are its loans being repaid, does it have enough of its own money to absorb losses, how risky are its countries, can we trust its numbers, and are there warning signs. Each is scored 1 to 5 and weighted. The four cards show how they land. Together they give 29 out of 100, which means about 21%. E is everything below 35, so the grade is E, 6 points below D. That is not close to the line: only one step up on earnings alone, from 2 to 3, would give 35, a D, with about 18%. One step up on trust in the numbers alone would give 31, and one step up on the loans alone 33, both still E. A better score needs audited group accounts for 2025 with notes, showing a profit after tax and figures on late loans.
Profit before tax of USD 12.0m in 2024, but USD 0.6m after tax. Owners’ money was USD 4.25m, 3.8% of assets, on figures without assurance.
The charge for unpaid loans was 84% of interest earned in 2024. The group publishes no figures on late loans or allowances. At the one group lender with audited detail, 79.8% of loans before allowances were classed as credit-impaired at the end of 2025.
Kazakhstan D and the Philippines D in our country memos. The group does not publish how its loans split between countries.
No assurance on 2023 and 2024, no notes in any year, 2025 not published. A licence suspended in Kazakhstan in 2025 and restored; press reports of a licence revoked in the Philippines.
De volledige analyse behandelt de lener of het bedrijf, de zekerheid, de kasstroom, de risico's en een oordeel. Log in om deze te lezen.
Informatie, geen persoonlijk beleggingsadvies. De AI-score beoordeelt de documenten die het platform publiceert, kan onjuist zijn en voorspelt geen rendement.
Log in om de AI vragen te stellen over de documenten van dit project.
Inloggen👍 Ja · 0 👎 Nee · 0
Mintos
Mintos
Reacties · 0