
Revente anticipée
- Niveau de risque
- Très élevé
- Risque-rendement
- Très mauvais
- Dès
- €10
Des questions sur l'investissement ? Demandez au guide IA.
Bonjour ! Je suis le guide IA de Crowdinform.
Connectez-vous gratuitement pour interroger le guide IA sur les plateformes, les projets et vos plans.
Les réponses proviennent des données vérifiées de Crowdinform. Information, et non conseil en investissement personnalisé.
Recherche en cours… Une erreur s'est produite. Veuillez réessayer. {n} questions restantes aujourd'hui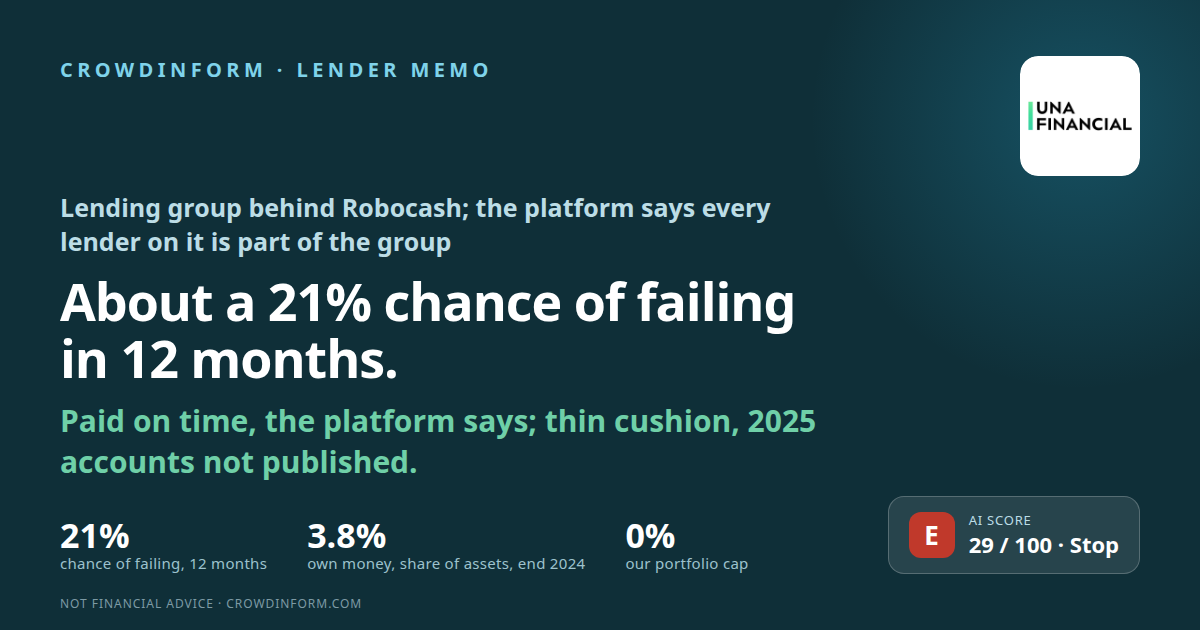
Singapour
Capital à risque. Le taux est convenu, et non garanti : si un emprunteur fait défaut, vous pouvez perdre une partie ou la totalité de votre argent.
Notre IA attribue à ce projet 29 sur 100 : Faible. Comment fonctionne le score IA
Information, et non conseil en investissement personnalisé. Le score IA évalue les documents publiés par la plateforme, peut se tromper et ne prédit pas les rendements.
Loans listed as “RC Bucharest (Robocash SG)” on Robocash lead to UnaFinancial Group: the Romanian vehicle ROBOCASH BUCHAREST S.R.L. sells investors claims on loans it gives to the group “through its ultimate holding company Robocash PTE. LTD.” (the platform’s words). On 16 November 2026 these were 94.5% of the platform’s active loans by number (672,188 of 711,130); Big Loan (Fingertip Finance Corp., Philippines, which the platform says is part of the same group) was the other 5.5%. The platform shows an outstanding portfolio of €69.3m in total and no euro amount per lender. Its lender page also lists “RC Bucharest (Kazakhstan)”; the statistics showed no active loans under that name. This memo is therefore about the group as a whole: Robocash PTE. LTD., Singapore, and its subsidiaries, consolidated. Its statements for 2021–22 call it Robocash Group; those for 2023 say “formerly Robocash Group”. The buyback after 30 days of delay is the promise of the “Lender” (User Agreement, clause 6.9), which for these loans is the Romanian vehicle as far as the platform’s page shows; the Assignment Agreement that names the parties is not public and we have not read it. It is not the platform’s promise. The platform’s own footer says: “Robocash is not regulated under any financial services license.” The platform says that “all loan originators on the platform belong to the same group”, and the group’s statements list the platform’s operator, Robocash d.o.o. (Croatia), among its subsidiaries. In plain words: as far as the published pages show, nobody independent stands between the investor and the group. The company that sells the claim and promises to buy it back, the company that borrows the money and the platform that reports on all of them are, by the platform’s account, parts of one group. Who owns the Romanian vehicle we could not confirm. This memo asks one question: what is the chance that the group fails to pay in the next 12 months, and why.
We ask six questions about every lender: does it earn enough, are its loans being repaid, does it have enough of its own money to absorb losses, how risky are its countries, can we trust its numbers, and are there warning signs. Each is scored 1 to 5 and weighted. The four cards show how they land. Together they give 29 out of 100, which means about 21%. E is everything below 35, so the grade is E, 6 points below D. That is not close to the line: only one step up on earnings alone, from 2 to 3, would give 35, a D, with about 18%. One step up on trust in the numbers alone would give 31, and one step up on the loans alone 33, both still E. A better score needs audited group accounts for 2025 with notes, showing a profit after tax and figures on late loans.
Profit before tax of USD 12.0m in 2024, but USD 0.6m after tax. Owners’ money was USD 4.25m, 3.8% of assets, on figures without assurance.
The charge for unpaid loans was 84% of interest earned in 2024. The group publishes no figures on late loans or allowances. At the one group lender with audited detail, 79.8% of loans before allowances were classed as credit-impaired at the end of 2025.
Kazakhstan D and the Philippines D in our country memos. The group does not publish how its loans split between countries.
No assurance on 2023 and 2024, no notes in any year, 2025 not published. A licence suspended in Kazakhstan in 2025 and restored; press reports of a licence revoked in the Philippines.
L'analyse complète couvre l'emprunteur ou l'entreprise, la garantie, les flux de trésorerie, les risques et un verdict. Connectez-vous pour la lire.
Information, et non conseil en investissement personnalisé. Le score IA évalue les documents publiés par la plateforme, peut se tromper et ne prédit pas les rendements.
Connectez-vous pour interroger l'IA sur les documents de ce projet.
Connexion👍 Oui · 0 👎 Non · 0
Mintos
Mintos
Commentaires · 0