
Regulated
Can sell early
- Risk level
- High
- Risk-return
- Medium
- Start from
- €20
Questions about investing? Ask the AI guide.
Hi! I'm the Crowdinform AI guide.
Sign in free to ask the AI guide about platforms, projects and your plans.
AI answers from Crowdinform's checked data. It can make mistakes. Information, not personal investment advice.
Looking it up… Something went wrong. Please try again. {n} questions left today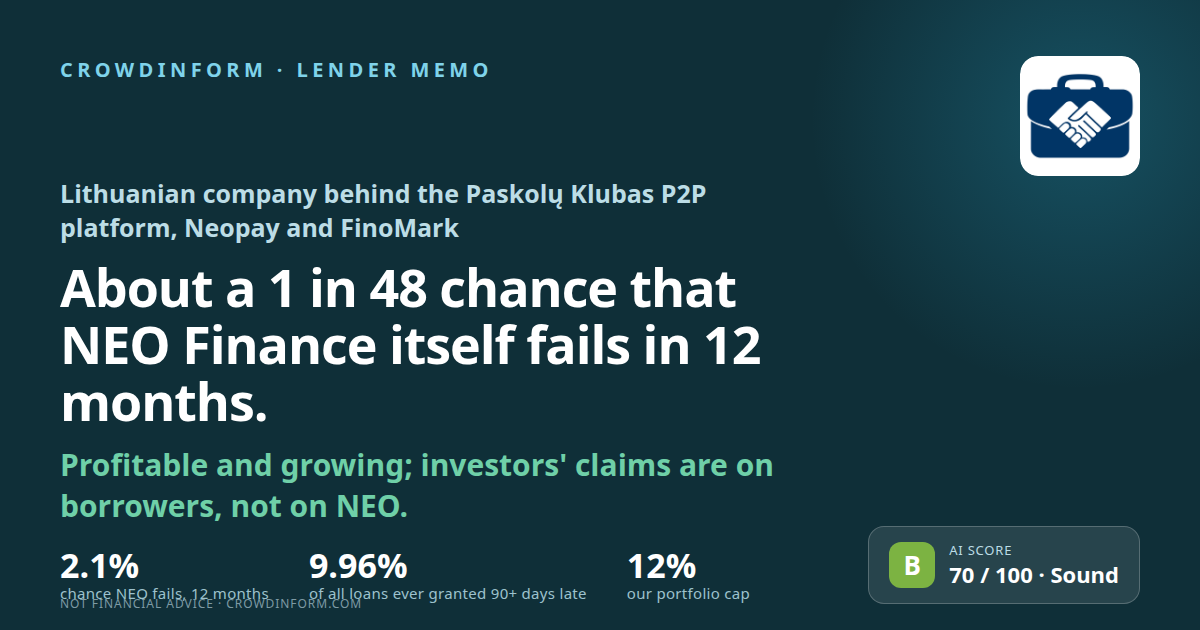
Lithuania
Capital at risk. The rate is agreed, not guaranteed: if a borrower defaults you can lose some or all of your money.
Our AI gives this project 70 out of 100: High. How the AI score works
Information, not personal investment advice. The AI score rates the documents the platform publishes, can be wrong, and does not predict returns.
This memo answers two questions rather than one, because the Paskolų Klubas platform needs both. First, what an investor there actually owns, and what happens to it if the company fails. Second, the chance that NEO Finance, AB — the company that runs the platform — fails to pay its own debts in the next 12 months. Those are different questions with different answers, and our score answers the second.
First, what you own. An investor on Paskolų Klubas funds consumer loans to individual Lithuanian borrowers. Your claim is on those borrowers, not on NEO Finance. The platform's own risk page says the investor "bears the full risk of the consumer borrower's insolvency". So our score — which is about NEO — is not the main thing that decides whether you are repaid. Borrower defaults are.
Second, the company. The marks come to 70, a B — about 1 in 48. Our October draft stopped there with a veto: a line in NEO’s audited accounts called "loans to related parties", added to its loans to its own subsidiaries, came to €3.94m against €4.77m of its own money — 83%, where our line is 50%. A separate check of that finding (8 November, repeated on 20 November 2026) rated it low, so it is no longer a veto. Section 4 explains why.
What the accounts actually show. €1.09m is lent to its own subsidiaries, which buy loans on its platforms, and the accounts say so. The other €2.85m, the line called "loans to related parties", is missing from the audited related-party note, which puts everything related parties owed NEO at €1.10m, 23% of equity. In June 2026 that line, with NEO’s other loan lines, adds up almost exactly to the portfolio of consumer and business loans NEO itself holds on its platforms. Most likely it is a misleading label, not money lent to insiders — but NEO has not said so, and we ask it in the open questions. At September 2026 its loans to subsidiaries were €1.14m against €6.04m of equity, 18.8%.
The business itself is doing well, and the memo should say so. Income rose from €4.74m to €8.39m in two years and profit from €0.26m to €1.50m. What was left over of every €100 went €5.50, €7.59, €17.86. The payments business has grown faster than the lending platform, so NEO depends on the platform less than it did. It paid its first recorded dividend in April 2026. In the first nine months of 2026 it made €1.48m before tax, 23% more than the €1.21m of the same months of 2025 (unaudited).
If NEO failed, your cash is ring-fenced and your loans survive — but somebody has to collect them. As an electronic money institution it must hold client money apart, and at the end of 2025 it held €31.0m that way. The loan contracts stay valid. What is missing is a named back-up servicer: the continuity plan has borrowers told to pay investors directly. Collections on the overdue loans, which depend on NEO's collectors, courts and bailiffs, would slow.
Six things would stop us scoring at all and send the answer straight to E — a default, a missed payment to a platform, a regulator pulling a licence, an auditor doubting the company can continue, a broken promise to a lender, or accounts we cannot rely on. None of them applies with certainty. Until 20 November 2026 we applied the one about lending to related parties; a separate check found the accounts do not support it, and it is now an open question. Two things would pull the answer the other way, a guarantee from a stronger owner or a credit rating. Neither applies. NEO Finance is the parent of its own group, and its owner has promised investors nothing, so there is no second number on this page.
Profit €1.50m in 2025, €17.86 of every €100, and its third profitable year. Regulatory own funds 3.3 times the minimum.
9.96% of every loan ever granted is more than ninety days late — an amount equal to 31% of what is outstanding today. New lending fell 41%.
Grade A (4.25 out of 5). The rate cap falls to 40% on 20 November 2026 and NEO's loans average 14.9%, so it does not bite.
A loan line labelled related-party lending that the related-party note does not show, notes that do not reconcile, a new auditor and a change at the top in March 2026.
The full review covers the borrower or company, the security, the cash flow, the risks and a verdict. Sign in to read it.
Information, not personal investment advice. The AI score rates the documents the platform publishes, can be wrong, and does not predict returns.
Sign in to ask the AI about this project's documents.
Sign in👍 Yes · 0 👎 No · 0
Comments · 0