
Revente anticipée
- Niveau de risque
- Très élevé
- Risque-rendement
- Mauvais
- Dès
- €10
Lien affilié · capital à risque
Voir 8 projets →Des questions sur l'investissement ? Demandez au guide IA.
Bonjour ! Je suis le guide IA de Crowdinform.
Connectez-vous gratuitement pour interroger le guide IA sur les plateformes, les projets et vos plans.
Les réponses proviennent des données vérifiées de Crowdinform. Information, et non conseil en investissement personnalisé.
Recherche en cours… Une erreur s'est produite. Veuillez réessayer. {n} questions restantes aujourd'hui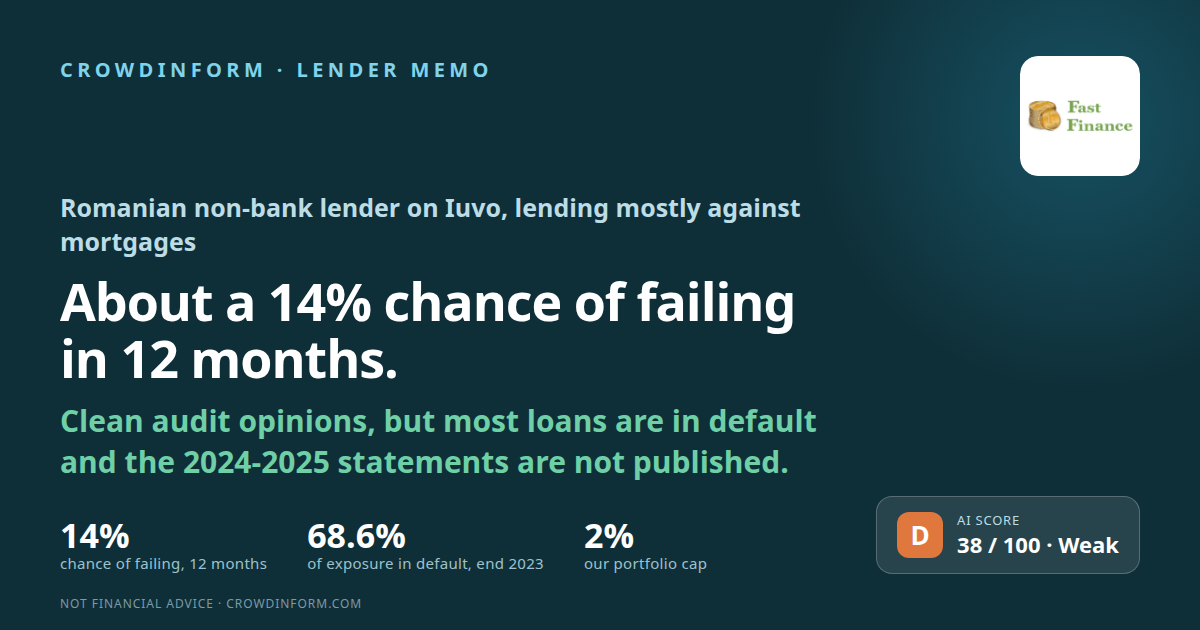
Roumanie
Capital à risque. Le taux est convenu, et non garanti : si un emprunteur fait défaut, vous pouvez perdre une partie ou la totalité de votre argent.
Notre IA attribue à ce projet 38 sur 100 : Faible. Comment fonctionne le score IA
Information, et non conseil en investissement personnalisé. Le score IA évalue les documents publiés par la plateforme, peut se tromper et ne prédit pas les rendements.
Fast Finance IFN S.A., trade register number J40/14948/2013, fiscal code 32548576, Bucharest, is a Romanian non-bank lender (an “IFN”). It lends to individuals and companies in Romania only, mostly through products its accounts name “cu Ipoteca”, with a mortgage. It is the company that owes Iuvo’s investors. Its 2023 statements book the money that came through Iuvo, under a cooperation contract of 27 December 2017, as its own debt, RON 3,142,891 at the end of 2023. So the investor depends on Fast Finance paying, not on the borrower alone. The money takes this route. Investor → IUVO GROUP OÜ (Estonia, 14063375), which runs the Iuvo platform → Fast Finance IFN S.A., which keeps the loans on its balance sheet → Romanian borrowers, with RON 27.5m of loans and attached interest before provisions at the end of 2023. Iuvo’s page for Fast Finance shows a buyback; that is Fast Finance’s own promise. Iuvo publishes two assignment agreements of 22 April 2026, one in which the investor buys the claim on the borrower and the originator buys it back, and one in which the claim is on the originator itself; which one applies to Fast Finance is in the key terms behind the investor login, which we have not read. Fast Finance’s 2023 notes describe the claim published on the portal as one “against the originator of the loan” (note 3.2, our translation), which points to the second, but the current terms may differ. Fast Finance is not a company of Management Financial Group (MFG), the group that owns Iuvo’s operator, so Iuvo’s “group guarantee” for MFG’s lenders does not cover it. Fast Finance was 0.50% of the amount of receivables listed on Iuvo in the third quarter of 2026 (Iuvo’s quarterly portfolio, 13 October 2026); that is new listings, not an amount owed, and Iuvo publishes no amount outstanding per lender. Iuvo’s footer says: “IUVO GROUP OÜ is not a bank, investment firm, crowdfunding service provider or payment institution, and its activity is not subject to supervision as a licensed financial institution.” This memo asks one question: what is the chance that Fast Finance fails to pay in the next 12 months, and why.
We ask six questions about every lender: does it earn enough, are its loans being repaid, does it have enough of its own money to absorb losses, how risky is its country, can we trust its numbers, and are there warning signs. Each is scored 1 to 5 and weighted. The four cards show how they land. Together they give 38 out of 100, which means about 14%. D runs from 35 to 49, so the grade is D, 3 points above E: within reach of the grade below. One step down on earnings (2 to 1) would give 32, on the cushion (3 to 2) 34: both E. One step down on the country would give 35, still D by the smallest margin. No single step up reaches C (50): the best, earnings 2 to 3, gives 44.
Profitable in each of the four years, but only 1.74 lei of every 100 of income was left in 2023, the last year with a full profit and loss account. The 2024 and 2025 profits lean on asset sales. Equity was 48.7% of assets at the end of 2023.
At the end of 2023, 68.6% of the exposure was in default (“Stage 3”) by the stage table, and bad debts took 73.6 of every 100 lei of income. Most of the income is interest on loans that are overdue.
Romania is grade D (2.39) in our country memo of 21 September 2026, which scores 2 out of 5 here. A cap on the cost of consumer loans is in force, and a draft ordinance would change the rules again.
Two unmodified audit opinions, but no published statements behind them. The 2023 notes show a RON 10.5m debt to a shareholder that is larger than all the liabilities in the balance sheet, and other lines that do not agree.
L'analyse complète couvre l'emprunteur ou l'entreprise, la garantie, les flux de trésorerie, les risques et un verdict. Connectez-vous pour la lire.
Information, et non conseil en investissement personnalisé. Le score IA évalue les documents publiés par la plateforme, peut se tromper et ne prédit pas les rendements.
Connectez-vous pour interroger l'IA sur les documents de ce projet.
Connexion👍 Oui · 0 👎 Non · 0
Lien affilié · capital à risque
Voir 8 projets →Mintos
Mintos
Commentaires · 0