
Regolamentata
Bonus attivo
Vendita anticipata
- Livello di rischio
- Alto
- Rischio-rendimento
- Medio
- Inizia da
- €50
Link di affiliazione · capitale a rischio
Vedi 11 progetti →Domande sugli investimenti? Chiedi alla guida IA.
Ciao! Sono la guida IA di Crowdinform.
Accedi gratis per fare domande alla guida IA su piattaforme, progetti e i tuoi piani.
Le risposte provengono dai dati verificati di Crowdinform. Informazione, non consulenza personalizzata sugli investimenti.
Sto cercando… Qualcosa è andato storto. Riprova. {n} domande rimaste oggi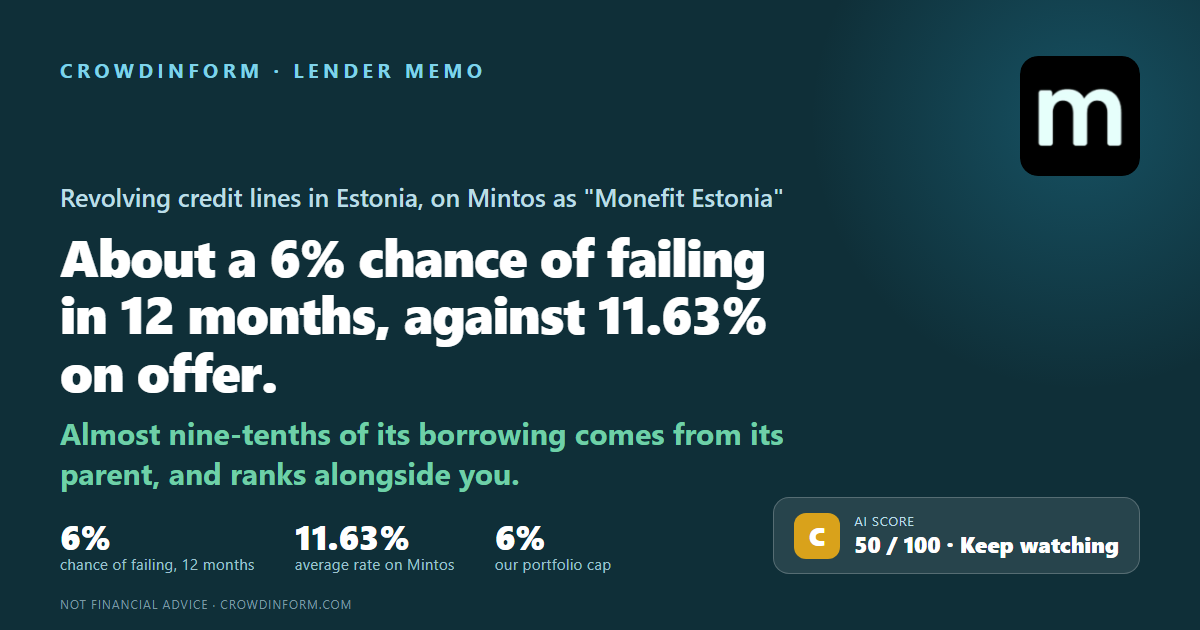
Estonia
Capitale a rischio. Il tasso è concordato, non garantito: se un debitore è inadempiente puoi perdere una parte o la totalità del tuo denaro.
La nostra IA assegna a questo progetto 50 su 100: Medio. Come funziona il punteggio IA
Informazioni, non consulenza personalizzata in materia di investimenti. Il punteggio IA valuta i documenti pubblicati dalla piattaforma, può essere sbagliato e non prevede i rendimenti.
Monefit Estonia OÜ lends revolving credit lines of €150 to €15,000 to people in Estonia, at rates from 0% to 43.2% over terms of eighteen to a hundred and four months. It has been licensed by Estonia's Financial Supervision Authority since March 2016. It has no staff of its own: the work is done by its parent, Creditstar International OÜ, which owns all of it. Mintos lists it as Monefit Estonia. This memo asks one question: what is the chance it fails to pay its lenders back in the next 12 months, and why.
The lending itself works. In 2025 this company earned €20.6m of income and made €9.27m before a charge it pays its parent. After the charge it kept €46,000. Of every €100 of income, €43.11 went in interest to its own lenders and €44.84 went to the parent, leaving 22 cents. Every line reconciles exactly to the audited profit, so the arithmetic is not in question. What it is doing is a choice about where the profit goes.
The second fact is the one to hold on to. Of the €71.9m this company has borrowed, €63.9m is a single unsecured loan from its parent at 16%, repayable within twelve months — almost nine-tenths of everything it has borrowed. Money lent through Mintos is about a ninth. In an insolvency the parent's claim would not stand behind yours — it would share the assets with you.
It sits exactly on the C/D line. We mark six things out of five. Move any single one of the six down by one point and the score falls below 50 and the grade becomes D. Nothing here has any margin.
Six things would stop us scoring at all and send the answer straight to E — a default, a missed payment to a platform, a regulator pulling a licence, an auditor doubting the company can continue, a broken promise to a lender, or accounts we cannot rely on. None applies here, on the position today. One of them needs explaining, and section 5 does it: in 2022 and 2023 Creditstar companies fell behind on payments to Mintos investors, and the rescheduled money was moved to Mintos's "In Recovery" status. We could not confirm whether this company's own notes were among them. Our test asks about the position today, and today there is no delay. Two things would pull the answer the other way, a guarantee from a stronger owner or a credit rating. Neither applies here.
Keeps 22 cents of every €100 after the charge to its parent. €8.13m of owners' money, 10.2% of what it owns, down from 13.5% as the book grew.
Bad debts cost 2.0% of the book in 2025, which is low. But no arrears and no ageing are published, so the figure cannot be checked against anything.
The euro, so no currency risk. Top-ten courts and clean government. Its highest rate, 43.2%, sits just under a ceiling of about 45% that moves on its own.
A clean KPMG audit and nothing paid out to owners. But the group's main covenant has about €2m of room, and a sister company was given a supervisory order in 2024.
Every investment carries risk, and risk is not really a letter or a mark out of ten. It is two plain questions: how likely is it that this company fails, and how much of your money would you lose if it did. Put those together and you can see whether the reward is worth it.
For Monefit Estonia: about a 6% chance of failing in the next 12 months. If we assume about 30% of the money comes back in that case, the risk costs roughly 4.2% a year. Mintos's own figure for the average rate on these notes, read on 5 November 2026, is 11.63%. On those two numbers about 7.4 points a year are left after paying for the risk, which is the most favourable comparison in any memo we have written so far. Both numbers carry caveats, and they are in section 1 and section 4 rather than hidden here.
An advertised 10% is what you are promised if everything goes well. What you keep is that rate minus what failures cost you. So the rate on its own tells you very little.
Risk cost = chance of failing × share of your money you would not get back. Nobody knows the second number in advance. How much comes back has varied widely from case to case. We use 30% back, 70% lost, as our own working assumption so that memos can be compared with each other — it is not a measured figure, and the answer moves a lot if you choose differently.
Take two imaginary lenders. One pays 14% but has a 17% chance of failing within the year: the risk costs about 11.9% a year, leaving roughly 2%. The other pays 9% with a 2.5% chance: the risk costs about 1.8%, leaving about 7%. The lower rate is the better deal. That is the whole idea.
Licence 4.1-1/36 of 16 March 2016 to grant consumer credit, and a mortgage-credit licence added on 8 July 2019. Both are on the regulator's own register, which we read on 12 October 2026 and which records no supervisory measure against this company. It takes no deposits.
Wholly owned. The same company is its lender and its service provider: Monefit Estonia has no staff of its own.
€150 to €15,000 to people in Estonia, 0% to 43.2%, over eighteen to a hundred and four months.
Up 32% in 2025. Income €20.6m. Owners' money €8.13m.
Read on 5 November 2026, with an average rate of 11.63% and a Mintos Risk Score of 6.4, as Mintos last updated it on 9 October 2026. The buyback is owed by this company; we found no group guarantee behind it. Platform figures are Mintos's own.
Lendermarket tells its investors the group stands behind their notes. Monefit SmartSaver money is raised by other group companies and reaches this one as a loan.
L'analisi completa copre il debitore o l'azienda, la garanzia, i flussi di cassa, i rischi e un verdetto. Accedi per leggerla.
Informazioni, non consulenza personalizzata in materia di investimenti. Il punteggio IA valuta i documenti pubblicati dalla piattaforma, può essere sbagliato e non prevede i rendimenti.
Accedi per fare domande all'IA sui documenti di questo progetto.
Accedi👍 Sì · 0 👎 No · 0
Link di affiliazione · capitale a rischio
Vedi 11 progetti →Mintos
Mintos