
Gereguleerd
- Risiconiveau
- Hoogste
- Risico-rendement
- Slecht
- Starten vanaf
- €10
Vragen over beleggen? Vraag het de AI-gids.
Hallo! Ik ben de AI-gids van Crowdinform.
Log gratis in om de AI-gids vragen te stellen over platforms, projecten en uw plannen.
De AI antwoordt op basis van de gecontroleerde gegevens van Crowdinform. Hij kan fouten maken. Informatie, geen persoonlijk beleggingsadvies.
Even opzoeken… Er ging iets mis. Probeer het opnieuw. Vandaag nog {n} vragen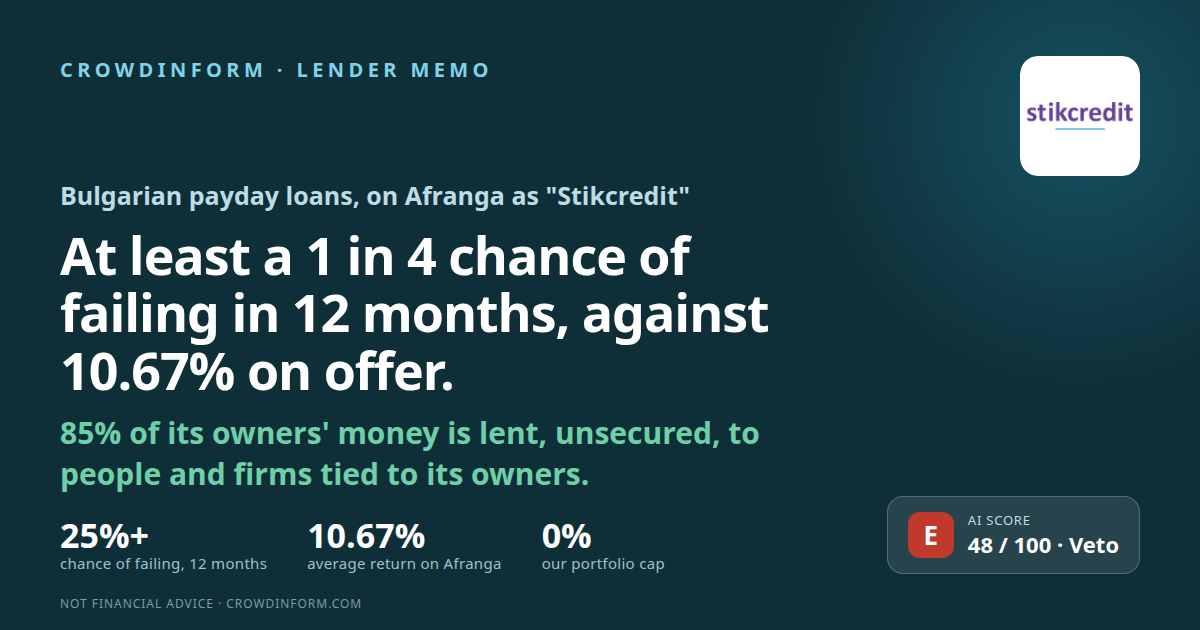
Bulgarije
Kapitaal loopt risico. De rente is afgesproken, niet gegarandeerd: als een lener in gebreke blijft, kunt u (een deel van) uw geld verliezen.
Onze AI geeft dit project 48 van de 100: Laag. Zo werkt de AI-score
Informatie, geen persoonlijk beleggingsadvies. De AI-score beoordeelt de documenten die het platform publiceert, kan onjuist zijn en voorspelt geen rendement.
Stik-Credit AD is a Bulgarian company lending small sums to people, through more than fifty offices and online. Investors on the Afranga platform lend money to it directly, under the name Stikcredit. This memo asks one question: what is the chance it fails to pay those lenders back in the next 12 months, and why.
We should start with what is good here, because there is more of it than in most memos in this series. Stik-Credit has made money every year we can see. It has no bank debt. Both audits are clean with no doubt raised about the business continuing. It has 209 staff and more than fifty offices, and it has been on the Bulgarian National Bank’s register since 2016.
Then the thing that overrides all of it. On its own audited figures, €11.76m was lent to companies connected to its owners at the end of 2025 — 75% of the owners’ money — and €14.46m by 30 June 2026, which is 85%. The audited note says in terms that no collateral was taken. Among the borrowers are a loss-making sister company, the owners’ property projects, a casino business, and the executive director personally.
We ask six questions about every lender: does it earn enough, are its loans being repaid, does it have enough of its own money to absorb losses, how risky is its country, can we trust its numbers, and are there warning signs. On those six alone this company scores 48 out of 100 — a D, about 1 in 14, or 6.95%. But a separate test overrides the score, and it is triggered, so the answer at the top of this page is at least 25%.
Profitable every year: it kept 10.40 of every 100 in 2025. But profit fell 35% while the company grew, and the cushion is mostly lent out.
56.6% of the book is more than 90 days late — and it wrote nothing off in 2025, raising provisions instead.
The best part of the memo. The euro since January 2026 removes currency risk. The thing to watch is a consumer-credit bill now in parliament.
The owners’ businesses borrow its capital unsecured; it guarantees a loss-making sister with no cap; the consumer authority found 14 unfair clauses.
De volledige analyse behandelt de lener of het bedrijf, de zekerheid, de kasstroom, de risico's en een oordeel. Log in om deze te lezen.
Informatie, geen persoonlijk beleggingsadvies. De AI-score beoordeelt de documenten die het platform publiceert, kan onjuist zijn en voorspelt geen rendement.
Log in om de AI vragen te stellen over de documenten van dit project.
Inloggen👍 Ja · 0 👎 Nee · 0
Mintos
Mintos
Reacties · 0