
Kan säljas i förtid
- Risknivå
- Högst
- Risk–avkastning
- Dålig
- Börja från
- €10
Affiliatelänk · ditt kapital är i riskzonen
Se 8 projekt →Frågor om att investera? Fråga AI-guiden.
Hej! Jag är Crowdinforms AI-guide.
Logga in gratis för att fråga AI-guiden om plattformar, projekt och dina planer.
Svaren kommer från Crowdinforms kontrollerade data. Information, inte personlig investeringsrådgivning.
Letar… Något gick fel. Försök igen. {n} frågor kvar i dag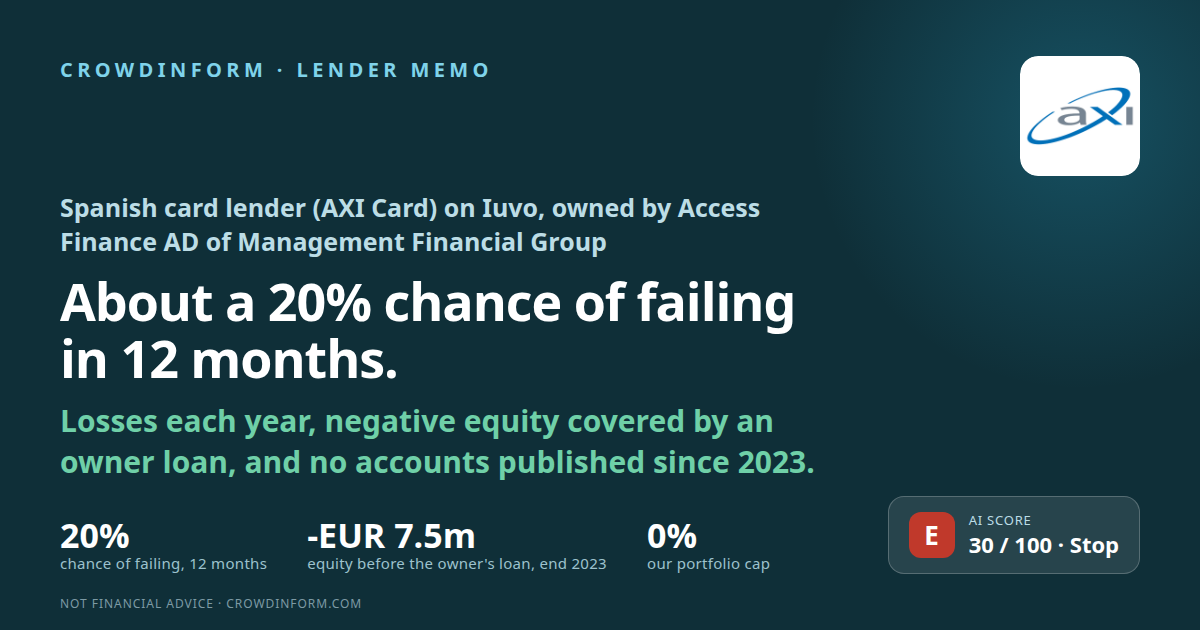
Spanien
Ditt kapital är i riskzonen. Räntan är avtalad, inte garanterad: om en låntagare inte betalar kan du förlora en del av eller alla dina pengar.
Vår AI ger det här projektet 30 av 100: Låg. Så fungerar AI-betyget
Information, inte personlig investeringsrådgivning. AI-betyget bedömer de dokument som plattformen publicerar, kan vara fel och förutspår inte avkastning.
Loans of “AXI Card Spain” on Iuvo lead to Access Finance, S.L.U., a Spanish limited company with a sole shareholder that lends to consumers through credit cards under the AXI Card brand. Iuvo’s lender page names only the brand and its website, says the business is “part of the portfolio of Management Financial Group (MFG)” and does not name the company; the accounts Iuvo published for AXI Card Spain in 2024 are those of Access Finance S.L.U. Its owner is Access Finance AD of Bulgaria, the lender behind Biala Karta on Iuvo, whose 2025 accounts say: “The Company owns 100% of Access Finance S.L. – Spain”, registered in 2019 and granting “unsecured loans by credit card”. Management Financial Group AD (MFG), Bulgaria, owns 75.74% of Access Finance AD; MFG is owned 50/50 by Nedelcho Spasov and Stanimir Vassilev, and also owns IUVO GROUP OÜ, which runs Iuvo. So the chain is: investor, Access Finance S.L.U., Spanish card customers; above it, Access Finance AD and MFG. Iuvo’s lender page shows “Buyback” and gives no terms. Which of Iuvo’s two contract forms these loans use (the lender as guarantor of a claim on the borrower, or the lender as the debtor) is in each loan’s key terms behind the login, which we did not read; either way the buyback or the debt is owed by the Spanish company, not by its owner. The buyback is the lender’s own promise. AXI Card took 0.78% of the amount of loans listed on Iuvo in the third quarter of 2026 (Iuvo’s quarterly portfolio, 13 October 2026); that is new listings, not money outstanding. Iuvo’s originators page gave its “receivables portfolio” as €5.35m (read 18 November 2026); Iuvo publishes no amount outstanding to investors per lender. Iuvo’s footer and its user agreement (2.1.1) say that IUVO GROUP OÜ “is not a bank, investment firm, crowdfunding service provider or payment institution, and its activity is not subject to supervision as a licensed financial institution”. This memo rests on accounts almost three years old: the company’s only published accounts are its abridged accounts for 2023, with 2022 beside them, nine pages without their notes. Iuvo’s AXI Card Spain page today links only the Bulgarian owner’s 2024 accounts. This memo asks one question: what is the chance that Access Finance S.L.U. fails to pay in the next 12 months, and why.
We ask six questions about every lender: does it earn enough, are its loans being repaid, does it have enough of its own money to absorb losses, how risky is its country, can we trust its numbers, and are there warning signs. Each is scored 1 to 5 and weighted. The four cards show how they land. Together they give 30 out of 100, which means about 20%. E is anything below 35, so the grade is E, 5 points below D: not within 3 points of the line. Only one single step would reach D: earnings from 1 to 2, which would give 36. One step up on the loans (2 to 3) or on the cushion (1 to 2) would give 34, still E. Every answer here rests on accounts almost three years old; the 2024 and 2025 accounts, which we have not seen, could move it either way.
Losses of €3.50m in 2022 and €2.57m in 2023, the second equal to 86.6% of its turnover. Owners’ money was −€7.53m at the end of 2023, positive by €0.22m only when the owner’s €7.75m equity loan is counted.
No evidence either way: the abridged accounts show customer receivables of €2.15m and nothing about how many are late or written off, so this question gets our “no evidence” score of 2.
Spain is grade C in our country memo: no currency risk, but courts that void card credit priced far above the market average, and a draft law to cap high-cost credit.
One audit, of 2023, with a material uncertainty about the company continuing; nine pages without notes; no accounts since. Its owner has written its loans to the company down by at least 98%.
Hela analysen tar upp låntagaren eller bolaget, säkerheten, kassaflödet, riskerna och ett omdöme. Logga in för att läsa den.
Information, inte personlig investeringsrådgivning. AI-betyget bedömer de dokument som plattformen publicerar, kan vara fel och förutspår inte avkastning.
Logga in för att fråga AI om projektets dokument.
Logga in👍 Ja · 0 👎 Nej · 0
Affiliatelänk · ditt kapital är i riskzonen
Se 8 projekt →Mintos
Mintos
Kommentarer · 0