
Reguliert
Bonus läuft
- Risikostufe
- Hoch
- Risiko-Rendite
- Mittel
- Start ab
- €10
Empfehlungslink · Kapitalverlustrisiko
7 Projekte ansehen →Fragen zum Investieren? Fragen Sie den KI-Guide.
Hallo! Ich bin der KI-Guide von Crowdinform.
Melden Sie sich kostenlos an, um den KI-Guide zu Plattformen, Projekten und Ihren Plänen zu fragen.
Lieber einen Experten fragen →
Die Antworten stammen aus den geprüften Daten von Crowdinform. Information, keine persönliche Anlageberatung.
Wird nachgeschlagen… Etwas ist schiefgelaufen. Bitte versuchen Sie es erneut. Heute noch {n} Fragen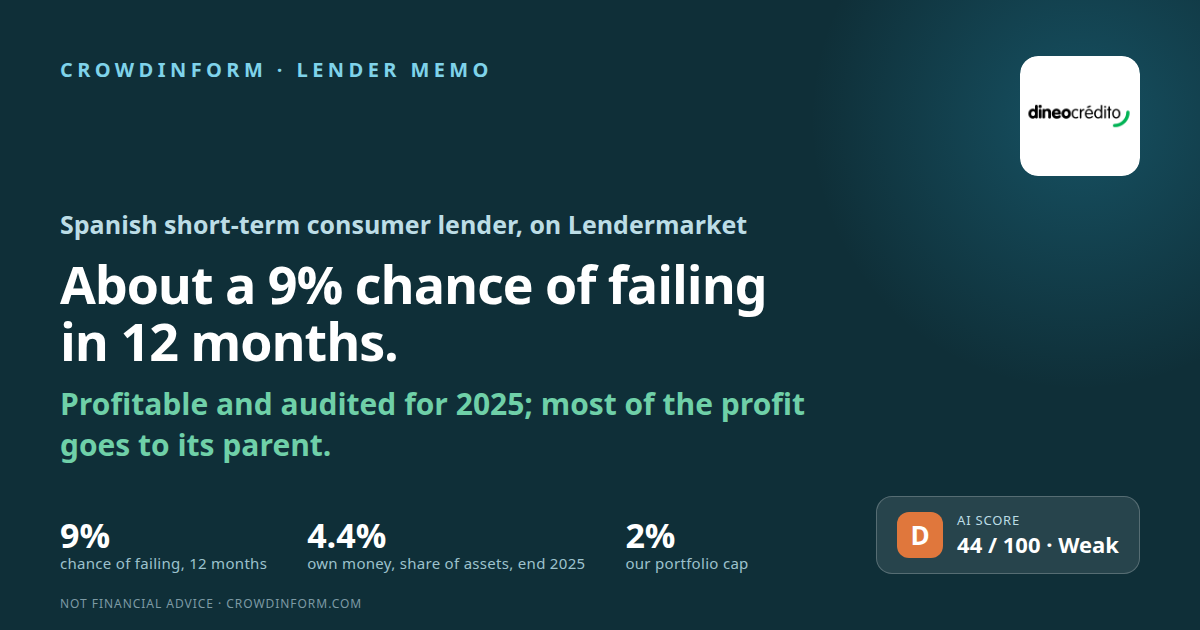
Spanien
Kapitalverlustrisiko. Der Zins ist vereinbart, nicht garantiert: Fällt ein Kreditnehmer aus, können Sie Ihr Geld teilweise oder vollständig verlieren.
Unsere KI gibt diesem Projekt 44 von 100 Punkten: Niedrig. So funktioniert der KI-Score
Informationen, keine persönliche Anlageberatung. Der KI-Score bewertet die von der Plattform veröffentlichten Dokumente, kann falsch sein und sagt keine Renditen voraus.
Loans of Dineo on Lendermarket lead to Dineo Crédito, S.L.U. itself, a Madrid company with the Spanish tax number B86971157 (from the company’s own legal notice; the accounts do not print it). Lendermarket’s risk page names “Dineo Crédito S.L.” as the legal entity, and the accounts we read are that company’s own. Lendermarket’s lender list, read on 16 November 2026, puts Dineo under “Regulated Services”. That is Lendermarket’s Crowdfunding Service, for which Lendermarket Limited is authorised by the Central Bank of Ireland; its other service, the assignment of claims, is outside that regulation. Under the Crowdfunding Service, Lendermarket’s services statement says, “funding of the Loan Originator takes place via an unsecured loan advanced by the User to the Loan Originator”. In plain words: the investor lends to Dineo itself, without security, and does not buy a borrower’s loan. The list shows a buyback obligation (“Yes”), no group guarantee (“No”), “skin in the game” of 5-10% and an average interest rate of 11.95%. Lendermarket says a buyback is “a contractual obligation of the relevant Loan Originator, not a guarantee from Lendermarket”, so the promise is Dineo’s alone. Lendermarket publishes no amount per lender that we could read, and Dineo’s accounts do not mention Lendermarket or investors at all. Dineo makes very short loans to consumers in Spain, online and, by its own presentation, at selling points in Cash Converters shops. The accounts say its sole shareholder is Cash Converters España, S.L., which they call “the ultimate parent company of the group”. We did not find who owns that company and we do not guess; we draw no link to any other company that uses the Cash Converters name. This memo asks one question: what is the chance that Dineo fails to pay in the next 12 months, and why.
We ask six questions about every lender: does it earn enough, are its loans being repaid, does it have enough of its own money to absorb losses, how risky is its country, can we trust its numbers, and are there warning signs. Each is scored 1 to 5 and weighted. The four cards show how they land. Together they give 44 out of 100, which means about 9%. D runs from 35 to 49, so the grade is D: 6 points below C and 9 above E, not within 3 points of either. The judgement call that matters most is earnings, which we score 3 out of 5. We keep 3, at its lower edge: profit before tax was almost the same in all three years and interest is covered 8.4 times, but cash from operations was only €62,050 in 2025 and profit after tax has fallen two years running. With 2 instead, the score would be 38 and the answer about 14%, still a D but only 3 points above E.
Profit of €2,388,563 in 2025: a profit in each of the three years, but lower in 2024 and lower again in 2025. Owners’ money was €608,020, 4.4% of assets, after a dividend of €1,855,000.
Unpaid loans cost €12,507,635 in 2025, about 48% of revenue. Of loans less than a year late, 24.6% were more than 90 days late.
It lends only in Spain, in euros. Spain is grade C in our country memo: by that memo, a strong economy, but courts that can void high-cost loans and a draft law, not confirmed as enacted, that would cap their price.
A clean 2025 audit, with the auditor drawing attention to customers’ court claims. But no auditor’s page for 2024, misprints in the notes, investors’ money not identifiable in the accounts, and a guarantee and dividends that run to the parent.
Die vollständige Analyse behandelt den Kreditnehmer bzw. das Unternehmen, die Sicherheit, den Cashflow, die Risiken und ein Fazit. Melden Sie sich an, um sie zu lesen.
Informationen, keine persönliche Anlageberatung. Der KI-Score bewertet die von der Plattform veröffentlichten Dokumente, kann falsch sein und sagt keine Renditen voraus.
Melden Sie sich an, um der KI Fragen zu den Dokumenten dieses Projekts zu stellen.
Anmelden👍 Ja · 0 👎 Nein · 0
Empfehlungslink · Kapitalverlustrisiko
7 Projekte ansehen →Mintos
Mintos
Kommentare · 0