
Vorzeitig verkaufbar
- Risikostufe
- Sehr hoch
- Risiko-Rendite
- Schlecht
- Start ab
- €10
Empfehlungslink · Kapitalverlustrisiko
8 Projekte ansehen →Fragen zum Investieren? Fragen Sie den KI-Guide.
Hallo! Ich bin der KI-Guide von Crowdinform.
Melden Sie sich kostenlos an, um den KI-Guide zu Plattformen, Projekten und Ihren Plänen zu fragen.
Lieber einen Experten fragen →
Die Antworten stammen aus den geprüften Daten von Crowdinform. Information, keine persönliche Anlageberatung.
Wird nachgeschlagen… Etwas ist schiefgelaufen. Bitte versuchen Sie es erneut. Heute noch {n} Fragen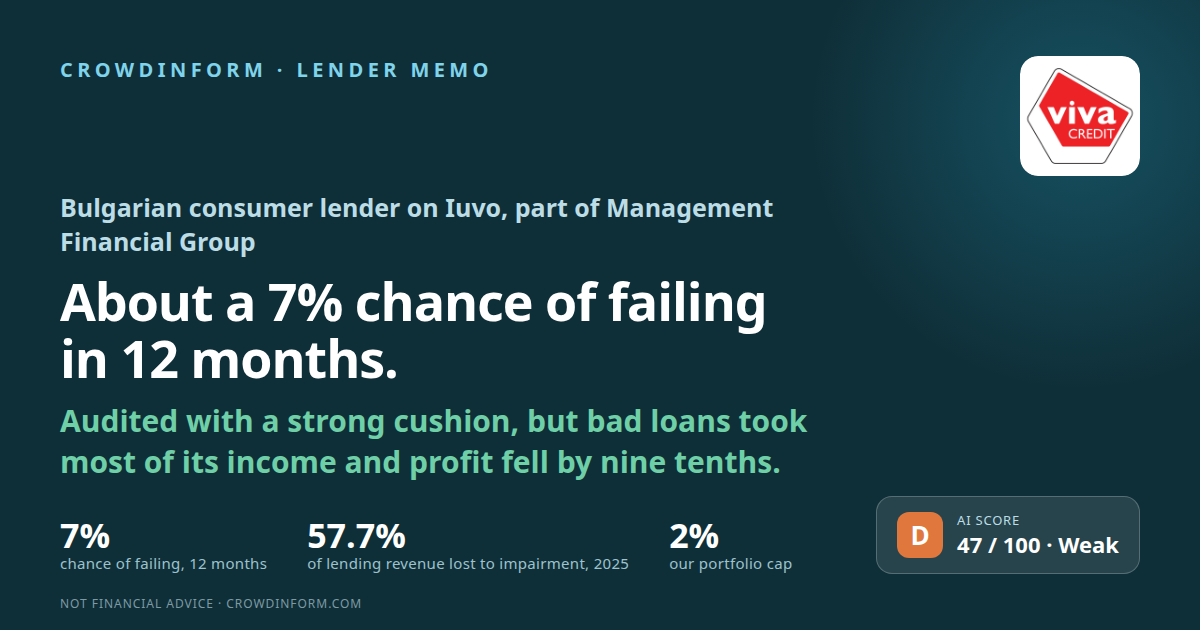
Bulgarien
Kapitalverlustrisiko. Der Zins ist vereinbart, nicht garantiert: Fällt ein Kreditnehmer aus, können Sie Ihr Geld teilweise oder vollständig verlieren.
Unsere KI gibt diesem Projekt 47 von 100 Punkten: Niedrig. So funktioniert der KI-Score
Informationen, keine persönliche Anlageberatung. Der KI-Score bewertet die von der Plattform veröffentlichten Dokumente, kann falsch sein und sagt keine Renditen voraus.
Viva Credit AD, company number 207343548, Sofia, lends small, short loans (“microloans”) to people in Bulgaria; its activity report says they are offered “on-site in various commercial establishments and via the Internet”. It is the company that owes Iuvo’s investors. Its audited accounts book the money investors put into its loans on Iuvo as its own borrowing, “P2P investors”, and describe the deals as assignments “with the right of recourse, which require the Company to guarantee the full payment of the remaining part of the investor’s principal in the event of a default of more than 60 days by the Company’s client”. So the investor depends on Viva Credit paying, not on the borrower alone. The money takes this route. Investor → IUVO GROUP OÜ (Estonia, 14063375), which runs the Iuvo platform and, by Viva Credit’s accounts, acts as agent → Viva Credit AD, which keeps the loans on its balance sheet and owes the investors BGN 2,074 thousand at the end of 2025, about €1.06m at the fixed rate of 1.95583 leva to the euro → Bulgarian borrowers, with microloans of BGN 29.5m before allowances. Iuvo’s page for Viva Credit shows a buyback; that is Viva Credit’s promise. Iuvo publishes two assignment agreements of 22 April 2026, one in which the investor buys the claim on the borrower and the originator buys it back, and one in which the claim is on the originator itself; which one applies to Viva Credit is in the key terms behind the investor login, which we have not read. Viva Credit belongs to Management Financial Group AD (MFG), Bulgaria, which held 99.46% of its shares at the end of 2025; MFG’s 2024 accounts name its owners as Nedelcho Spasov and Stanimir Vassilev, 50% each. MFG is also the parent of the platform’s operator: it holds 96.59% of IUVO GROUP OÜ (Viva Credit’s 2025 activity report). Viva Credit was 3.07% of the amount of receivables listed on Iuvo in the third quarter of 2026, and MFG companies together 95.11% (Iuvo’s quarterly portfolio, 13 October 2026); those are new listings, not amounts owed, and Iuvo publishes no amount outstanding per lender. Iuvo’s footer says: “IUVO GROUP OÜ is not a bank, investment firm, crowdfunding service provider or payment institution, and its activity is not subject to supervision as a licensed financial institution.” This memo asks one question: what is the chance that Viva Credit fails to pay in the next 12 months, and why.
We ask six questions about every lender: does it earn enough, are its loans being repaid, does it have enough of its own money to absorb losses, how risky is its country, can we trust its numbers, and are there warning signs. Each is scored 1 to 5 and weighted. The four cards show how they land. Together they give 47 out of 100, which means about 7%. D runs from 35 to 49, so the grade is D, 3 points below C: within reach of the next grade. One step up on any one of three questions would make it a C: the loans (1 to 2) would give 51, earnings (2 to 3) 53, the cushion (4 to 5) 51. One step down on the cushion would give 43, on the country 44: still D.
Profitable in each of the last three years, but only just in 2025: BGN 747 thousand after tax, against 7,264 thousand in 2024. Equity of BGN 16.1m was 66.5% of its assets, with almost nothing in intangible items.
Impairment took 57.7% of lending revenue in 2025. 45.1% of the loans were more than 90 days late at the year-end, after BGN 19.2m was written off in the year and overdue loans were sold at a loss of BGN 2.7m.
Bulgaria is grade C (3.30) in our country memo of 21 September 2026, which scores 3 out of 5 here. A new consumer-credit law is reported to have passed since (not confirmed by us); the memo has not yet been reviewed for it.
Two clean audits with full notes. But a 2023 dividend of BGN 4.9m is said to be paid by bank transfer while the cash-flow statement shows 37 thousand, a BGN 3.5m loan goes to a company the accounts do not name, and the platform is not supervised.
Die vollständige Analyse behandelt den Kreditnehmer bzw. das Unternehmen, die Sicherheit, den Cashflow, die Risiken und ein Fazit. Melden Sie sich an, um sie zu lesen.
Informationen, keine persönliche Anlageberatung. Der KI-Score bewertet die von der Plattform veröffentlichten Dokumente, kann falsch sein und sagt keine Renditen voraus.
Melden Sie sich an, um der KI Fragen zu den Dokumenten dieses Projekts zu stellen.
Anmelden👍 Ja · 0 👎 Nein · 0
Empfehlungslink · Kapitalverlustrisiko
8 Projekte ansehen →Mintos
Mintos
Kommentare · 0