Crowdfunding in Sweden: the platforms to know
Crowdfunding in Sweden: 5 platforms compared on what you invest in, minimum, stated figures and licence, plus FI's rules and the 30% tax on interest.
- Investing in Loans
- Crowdfunding
Questions about investing? Ask the AI guide.
Hi! I'm the Crowdinform AI guide.
Sign in free to ask the AI guide about platforms, projects and your plans.
Answers come from Crowdinform's checked data. Information, not personal investment advice.
Looking it up… Something went wrong. Please try again. {n} questions left todayArticle
Discover what crowdfunding taxonomy is and how it helps you choose the best crowdfunding model for your goals. Start your journey today!
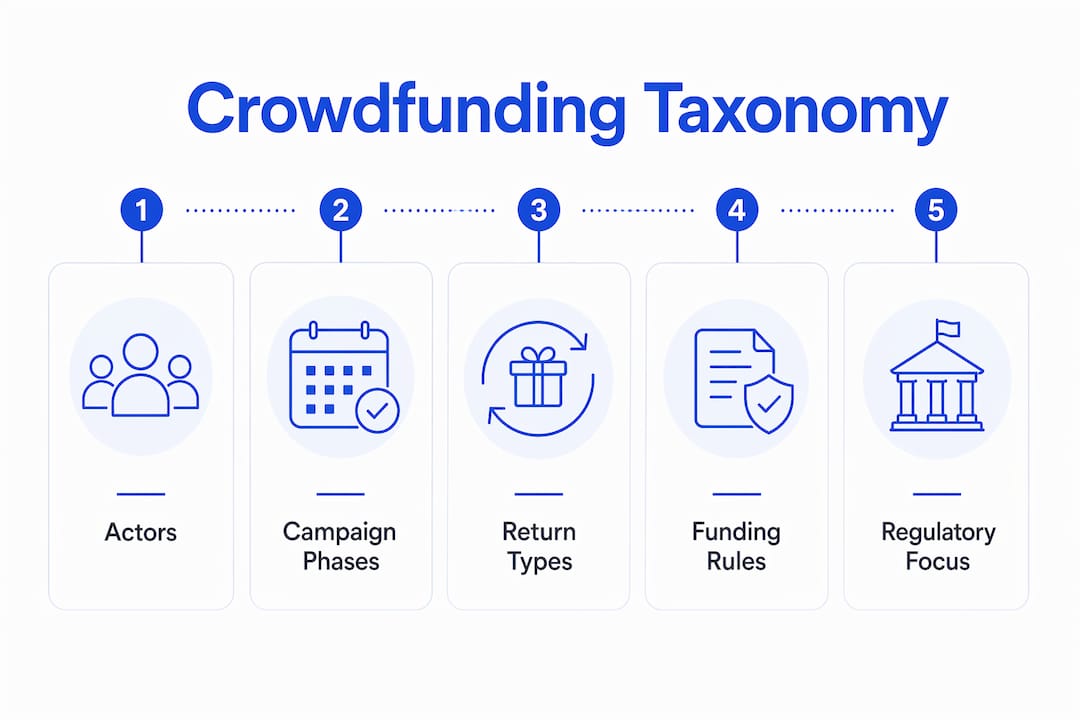
Crowdfunding taxonomy is the structured classification of crowdfunding models by actor roles, campaign phases, and economic relationships between backers and project initiators. Understanding crowdfunding classification matters because it determines how you compare platforms, assess risk, and select the model that fits your goals. The three core actors in any taxonomy are project initiators, backers, and platforms, each with distinct obligations and incentives. Whether you are an individual investor exploring loan-based returns or an organisation launching a reward campaign, taxonomy gives you the vocabulary and framework to make that choice with confidence.
Crowdfunding taxonomy is defined as a systematic framework that classifies crowdfunding by types, actor roles, campaign phases, and return structures to enable consistent comparison across diverse models. Think of it as the periodic table for crowdfunding. Each element has a defined place, and knowing where something sits tells you a great deal about how it behaves.
The taxonomy rests on three foundational actor categories. Three key actors form every crowdfunding interaction: project initiators (the founders or campaign creators), backers (the crowd providing capital), and platforms (the intermediaries facilitating the exchange). Each actor carries different rights, risks, and expectations, and taxonomy makes those differences explicit rather than leaving them buried in platform terms and conditions.
Beyond actors, taxonomy organises crowdfunding by campaign phase. The pre-funding phase covers everything from campaign creation and promotion through to the funding deadline. The post-funding phase covers fund disbursement, project delivery, and any ongoing obligations such as interest repayments or equity reporting. A 2025 systematic literature review confirms that taxonomy shapes analytical perspective in crowdfunding research, meaning the lens you apply changes what you see and measure.
The most practically useful dimension is return type. The UK Financial Conduct Authority (FCA) describes four economic relationships between backers and projects: donation, reward, equity, and debt. Each type carries a fundamentally different risk profile and set of legal obligations for all three actors.
Pro Tip: When evaluating any crowdfunding opportunity, identify the return type first. That single classification tells you whether you face credit risk (debt), business risk (equity), delivery risk (rewards), or no financial return at all (donation).
The four return-based categories are the backbone of any practical crowdfunding classification. Understanding each one precisely prevents the most common investor mistakes.
Beyond return type, taxonomy also classifies campaigns by funding rule. The two dominant rules are all-or-nothing (AON) and keep-it-all (KIA). Under AON, funds are returned to backers if the campaign target is not met. Under KIA, the initiator retains whatever is raised regardless of target achievement. These rules directly affect backer incentives, platform fee timing, and campaign design strategy.
The table below compares the four primary crowdfunding types across the dimensions most relevant to investors and project founders.
| Type | Backer return | Typical funding rule | Primary risk for backer | Regulatory scrutiny |
|---|---|---|---|---|
| Donation | None | Keep-it-all | No financial return | Low |
| Reward | Product or perk | All-or-nothing | Non-delivery of reward | Low to moderate |
| Equity | Ownership stake | All-or-nothing | Business failure or dilution | High |
| Debt (loan) | Interest repayment | All-or-nothing | Borrower default | High |
The FCA confirms that platforms charge fees as a percentage of funds raised, typically triggered only when funding targets are met under an all-or-nothing structure. This means the platform's commercial incentive aligns with campaign success, which is a structural feature worth noting when you assess platform neutrality.
Equity and debt crowdfunding attract the most regulatory attention because they involve financial instruments. The FCA and equivalent European regulators treat these as investment products, applying disclosure requirements, investor categorisation rules, and platform authorisation standards. Donation and reward models sit outside most financial regulation, which lowers the compliance burden for initiators but also reduces formal backer protections.
Return type also drives operational obligations for initiators. Ownership, repayment, perks, or donation each create different post-campaign responsibilities. An equity initiator must maintain shareholder communications and potentially file accounts. A debt initiator must service loan repayments on schedule. A reward initiator must manufacture and ship a product. Taxonomy makes these obligations visible before you commit.
Pro Tip: If you are comparing platforms across Europe, check whether they hold a European Crowdfunding Service Provider (ECSP) licence. Licensed platforms are authorised to offer equity and debt products under a harmonised regulatory framework, which is a meaningful quality signal. See regulated crowdfunding platforms for a current overview.
Taxonomy is only useful if it translates into a decision. Here is a practical sequence for selecting the right crowdfunding model based on classification criteria.
Academic frameworks and regulatory guidance have both contributed to the taxonomy we use today, and understanding their influence helps you apply it more accurately.
Scholarly research has consistently organised crowdfunding studies around actor-based and phase-based categories. A 2025 systematic literature review demonstrates that taxonomy shapes motivation analysis by determining whether a study focuses on donor behaviour, founder strategy, platform design, or campaign outcomes. This is not an academic abstraction. It means that when you read a report claiming "crowdfunding success rates are X%", the figure is only meaningful if you know which actor category and which crowdfunding type the study examined.
Regulators have adopted taxonomy for a different but equally practical purpose. The FCA uses crowdfunding classification to map types of investor participation and their inherent risks, guiding investor protection measures. This regulatory use of taxonomy has produced concrete outcomes: equity and debt platforms must be authorised, must provide standardised risk warnings, and must categorise investors before allowing participation. Donation and reward platforms face none of these requirements.
The European Union's ECSP regulation, which came into full effect in 2023, represents the most ambitious attempt to harmonise crowdfunding taxonomy at a regulatory level. It defines investment-based and lending-based crowdfunding as distinct categories, each with specific disclosure and governance requirements. Platforms operating across multiple European markets now use this taxonomy as their compliance architecture.
For a practical look at how scholarly frameworks apply to renewable energy projects, Crowdinform's guide on researching energy crowdfunding illustrates how actor and phase classifications translate into project evaluation criteria.
Crowdfunding taxonomy is the single most effective framework for comparing crowdfunding models, assessing risk, and selecting platforms aligned with your financial goals.
| Point | Details |
|---|---|
| Four return types define taxonomy | Donation, reward, equity, and debt each carry distinct risks, obligations, and regulatory treatment. |
| Three actors structure every model | Project initiators, backers, and platforms each hold different rights and responsibilities within the taxonomy. |
| Funding rules affect backer protection | All-or-nothing structures return capital if targets are missed; keep-it-all structures do not. |
| Due diligence varies by type | Credit risk applies to debt, business risk to equity, and delivery risk to rewards. |
| Regulation follows taxonomy | Equity and debt models attract FCA and ECSP oversight; donation and reward models largely do not. |
Most investors I speak with treat crowdfunding as a single category. They ask "is crowdfunding safe?" as if Kickstarter and a peer-to-peer property lending platform are the same thing. They are not. They share a name and a crowd mechanic, and almost nothing else.
The taxonomy framework changes that conversation entirely. When you know you are evaluating a debt instrument with a fixed interest rate, a defined borrower, and a specific loan-to-value ratio, you stop asking vague questions and start asking precise ones: What is the borrower's credit history? What is the platform's default rate? What recovery mechanisms exist? Those are the right questions, and taxonomy is what gets you there.
The misconception I encounter most often is that taxonomy is an academic exercise with no practical application. The opposite is true. Regulators built the ECSP framework on it. The FCA's investor protection rules are structured around it. The most experienced European crowdfunding investors I have observed use it instinctively, tagging every opportunity by return type, funding rule, and legal instrument before they read a single line of the campaign description.
My honest recommendation: before you evaluate any crowdfunding opportunity, spend thirty seconds placing it in the taxonomy. What is the return type? What is the funding rule? Who are the three actors and what are their obligations? Those three questions will save you from the majority of poor decisions in this market.
— Jevgenijs
Understanding taxonomy is the foundation. Applying it across hundreds of platforms and thousands of live projects is where Crowdinform comes in.

Crowdinform aggregates and reviews over 500 European crowdfunding platforms, covering loan, real estate, and startup investments with clear classifications aligned to the taxonomy framework described in this article. The platform's AI copilot analyses live projects and delivers structured reviews that map directly to return type, funding rule, and risk category, so you can compare opportunities without starting from scratch each time. Whether you are a cautious investor exploring safer crowdfunding options or an experienced backer tracking European deal flow, Crowdinform gives you the structured intelligence to act with confidence.
Crowdfunding taxonomy is a structured classification system that organises crowdfunding models by actor roles (initiators, backers, platforms), campaign phases (pre- and post-funding), and economic return types (donation, reward, equity, debt). It enables consistent comparison across diverse crowdfunding approaches.
The four main types are donation-based, reward-based, equity-based, and debt-based crowdfunding. Each type defines a different economic relationship between the backer and the project, with distinct risks and regulatory treatment.
All-or-nothing campaigns return funds to backers if the target is not met, protecting backer capital. Keep-it-all campaigns allow initiators to retain whatever is raised regardless of whether the target is reached, which shifts risk to the backer.
Regulators such as the FCA and the EU use crowdfunding taxonomy to map investor participation types and their inherent risks, applying authorisation requirements and disclosure obligations specifically to equity and debt models while leaving donation and reward models largely outside financial regulation.
Because each type carries a different primary risk: credit risk for debt crowdfunding, business risk for equity, and delivery risk for rewards. Taxonomy identifies the correct risk lens before you begin evaluating a specific campaign or platform.
Capital at risk. Crowdfunding investments are not covered by deposit guarantee schemes, can lose part or all of their value, and may be hard to sell before the end of their term. This guide is information, not personal investment advice.
Was this helpful?

Eugene Sokolovs Expert
Founder of Crowdinform
Keep reading
Crowdfunding in Sweden: 5 platforms compared on what you invest in, minimum, stated figures and licence, plus FI's rules and the 30% tax on interest.
What is crowdfunding? A plain guide to how it works, the main types (reward, equity, loans, real estate), the EU rules and the risks for investors.
Discover what is portfolio diversification and how it reduces risk. Learn to spread your investments effectively for smoother returns.
Comments · 0