
Can sell early
- Risk level
- High
- Risk-return
- Bad
- Start from
- €10
Questions about investing? Ask the AI guide.
Hi! I'm the Crowdinform AI guide.
Sign in free to ask the AI guide about platforms, projects and your plans.
Answers come from Crowdinform's checked data. Information, not personal investment advice.
Looking it up… Something went wrong. Please try again. {n} questions left today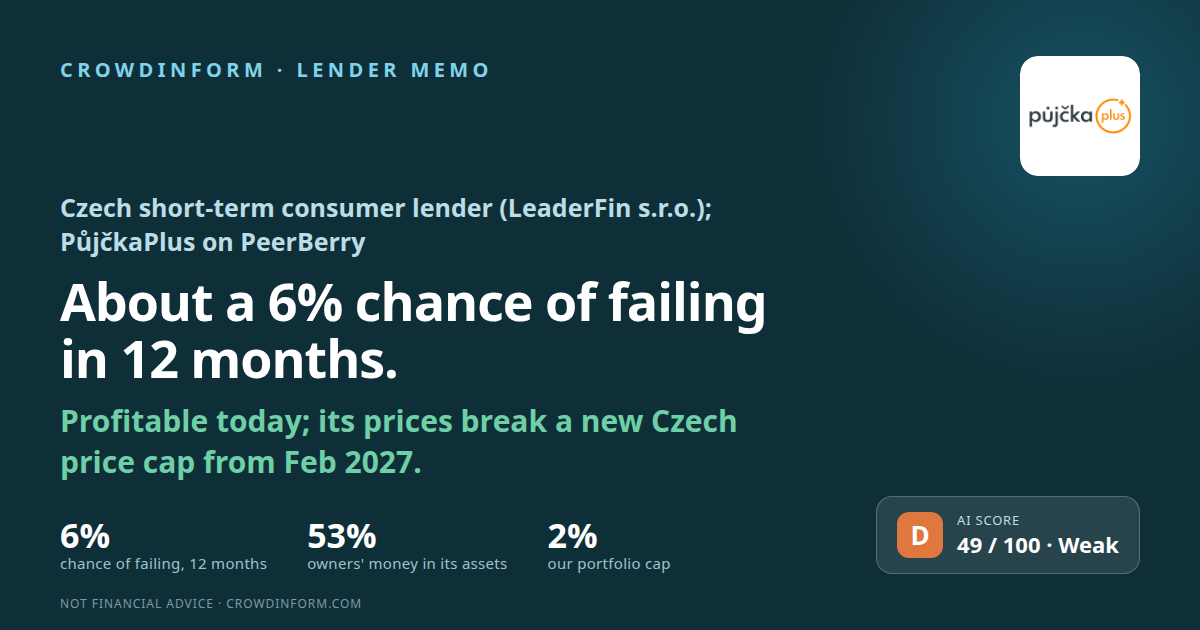
Czech Republic
Capital at risk. The rate is agreed, not guaranteed: if a borrower defaults you can lose some or all of your money.
Our AI gives this project 49 out of 100: Low. How the AI score works
Information, not personal investment advice. The AI score rates the documents the platform publishes, can be wrong, and does not predict returns.
PeerBerry’s PůjčkaPlus page says “PůjčkaPlus is an Aventus Group company in the Czech Republic” offering “short-term non-bank loans with an average amount of around EUR 300”, with a buyback and a group guarantee, and showed €1,105,945 of funded loans at 9.00% (archive copy of 20 October 2026). The company behind the brand is LeaderFin s.r.o. in Prague (IČO 044 40 170), a non-bank consumer lender licensed by the Czech National Bank. Its sole owner is UAB DN Invest in Vilnius, which also lends to it. Its accounts show no money owed to PeerBerry investors, only loans from its parent. This memo asks one question: what is the chance that LeaderFin fails to pay in the next 12 months, and why.
We ask six questions about every lender: does it earn enough, is the money owed to it coming in, does it have enough of its own money to absorb losses, how risky is its country, can we trust its numbers, and are there warning signs. Each is scored 1 to 5 and weighted. The four cards show how they land; the weighted result is the about 6% at the top.
A profit of CZK 42.2m in 2025 on CZK 256.6m of income, and owners’ money is 53% of what it owns (cushion: C). But from February 2027 the law cuts what it may charge, above all on repeat loans (earnings: D).
Bad loans cost 36 koruna for every 100 koruna of loans on its books in 2025, and it sold bad loans of CZK 92.1m for about half their face value.
Grade B in our country memo: a steady economy, a stable koruna and an AA- state; held down by the new price cap.
A clean first audit, but 2024 is restated and not audited, the auditor shares its address, and the central bank fined it in 2021 for charging above the legal limit.
The full review covers the borrower or company, the security, the cash flow, the risks and a verdict. Sign in to read it.
Information, not personal investment advice. The AI score rates the documents the platform publishes, can be wrong, and does not predict returns.
Sign in to ask the AI about this project's documents.
Sign in👍 Yes · 0 👎 No · 0
Debitum
Debitum
Comments · 0