
Regulada
Bono activo
- Nivel de riesgo
- Alto
- Riesgo-rentabilidad
- Media
- Desde
- €10
Enlace de afiliado · capital en riesgo
Ver 7 proyectos →¿Preguntas sobre inversión? Pregunte a la guía IA.
¡Hola! Soy la guía de IA de Crowdinform.
Inicia sesión gratis para preguntar a la guía IA sobre plataformas, proyectos y tus planes.
Las respuestas proceden de los datos verificados de Crowdinform. Información, no asesoramiento de inversión personalizado.
Buscando… Algo ha fallado. Inténtelo de nuevo. {n} preguntas restantes hoy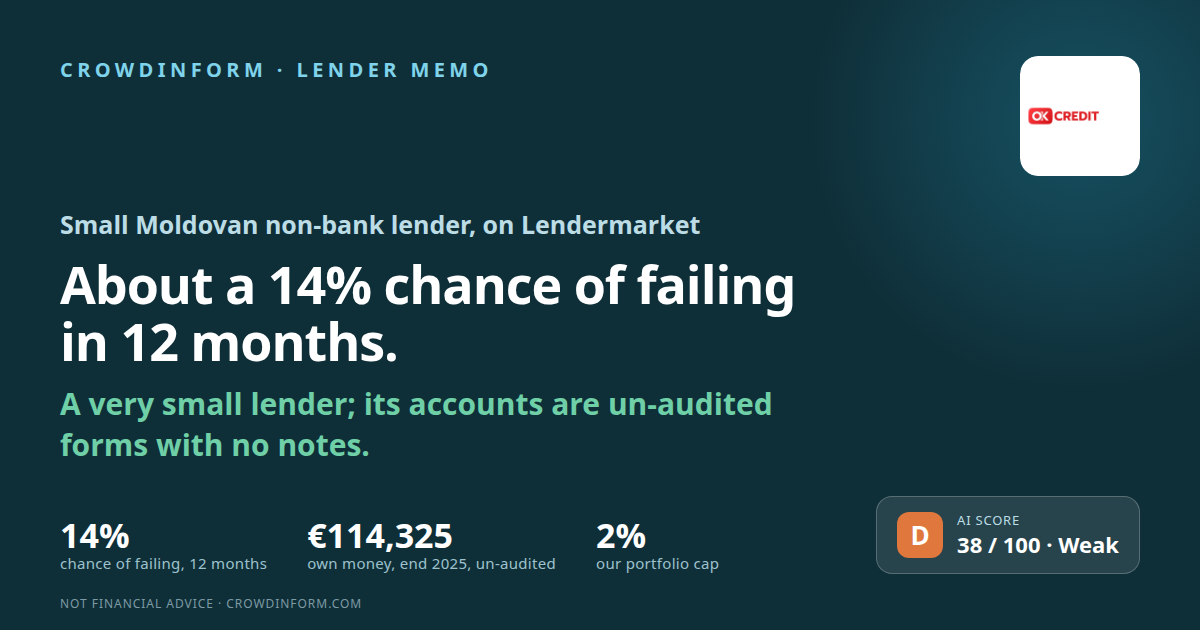
Moldavia
Capital en riesgo. El tipo está pactado, no garantizado: si un prestatario incurre en impago, puede perder una parte o la totalidad de su dinero.
Nuestra IA da a este proyecto 38 de 100: Baja. Cómo funciona la puntuación de la IA
Información, no asesoramiento personalizado de inversión. La puntuación IA valora los documentos que publica la plataforma, puede equivocarse y no predice la rentabilidad.
OK Credit on Lendermarket is O.C.N. “OK Credit” S.R.L., a Moldovan non-bank lender in Chișinău (state identification number, IDNO, 1013600011979). Lendermarket announced it as a new loan originator on 21 August 2026 and gives the same number. The company lends small sums to people, without security or against a vehicle or a property; Lendermarket says it was registered in 2013 and has operated since 2014. Lendermarket lists it under its regulated Crowdfunding Service. In that service, by Lendermarket’s Services Statement, “funding of the Loan Originator takes place via an unsecured loan advanced by the User to the Loan Originator”: the investor lends to OK Credit itself and does not buy a borrower’s loan. Lendermarket’s list shows a buyback obligation (“Yes”), no group guarantee (“No”), “skin in the game” of 10% and an average interest rate of 10.5%. The buyback is the lender’s own promise, “not a guarantee from Lendermarket” in Lendermarket’s words. Lendermarket publishes no amount per lender, so we do not know how much investors have lent to OK Credit. There is no chain of companies: no parent and no group is named in any document we read. This memo asks one question: what is the chance that OK Credit fails to pay in the next 12 months, and why.
We ask six questions about every lender: does it earn enough, are its loans being repaid, does it have enough of its own money to absorb losses, how risky is its country, can we trust its numbers, and are there warning signs. Each is scored 1 to 5 and weighted. The four cards show how they land. Together they give 38 out of 100, which means about 14%. The grade is D, and it is close to the line below: E is below 35, three points away, and C starts at 50. One point less on earnings (total 32), on the loans (34) or on the cushion (34) would make it E. The loans are the score that could most easily move, because nothing about them is published. No single score, moved up by one point, reaches C.
The un-audited forms show a profit of €21,200 in 2025 and €5,793 in 2024. Owners’ money was €114,325, or 24.6% of assets, and 93% of the 2025 profit was used. A fall in income of 6.4% would remove the 2025 profit.
No evidence either way. The forms have no line for loans to customers, for money set aside or for loans written off. This question gets our “no evidence” score of 2.
It lends in Moldova only. Moldova is grade D in our country memo of 13 September 2026, which scores 2 out of 5 here.
No auditor’s page, no signature, no notes; euros at a conversion rate the file does not state; three figures that do not follow from the lines around them. We score trust in the numbers 1 out of 5.
El análisis completo cubre al prestatario o la empresa, la garantía, el flujo de caja, los riesgos y un veredicto. Inicie sesión para leerlo.
Información, no asesoramiento personalizado de inversión. La puntuación IA valora los documentos que publica la plataforma, puede equivocarse y no predice la rentabilidad.
Inicie sesión para preguntar a la IA sobre los documentos de este proyecto.
Iniciar sesión👍 Sí · 0 👎 No · 0
Enlace de afiliado · capital en riesgo
Ver 7 proyectos →Mintos
Mintos
Comentarios · 0