
Revente anticipée
- Niveau de risque
- Très élevé
- Risque-rendement
- Très mauvais
- Dès
- €5
Lien affilié · capital à risque
Voir 5 projets →Des questions sur l'investissement ? Demandez au guide IA.
Bonjour ! Je suis le guide IA de Crowdinform.
Connectez-vous gratuitement pour interroger le guide IA sur les plateformes, les projets et vos plans.
L’IA répond à partir des données vérifiées de Crowdinform. Elle peut se tromper. Information, pas un conseil en investissement personnalisé.
Recherche en cours… Une erreur s'est produite. Veuillez réessayer. {n} questions restantes aujourd'hui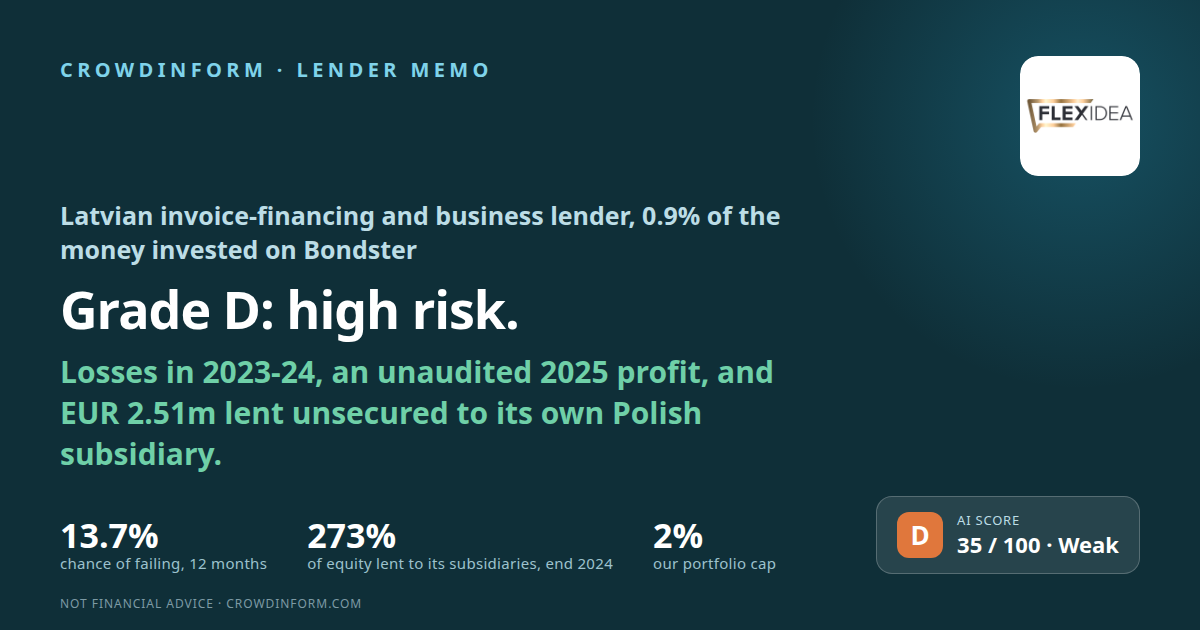
Lettonie
Capital à risque. Le taux est convenu, et non garanti : si un emprunteur fait défaut, vous pouvez perdre une partie ou la totalité de votre argent.
Notre IA attribue à ce projet 35 sur 100 : Faible. Comment fonctionne le score IA
Information, et non conseil en investissement personnalisé. Le score IA évalue les documents publiés par la plateforme, peut se tromper et ne prédit pas les rendements.
Investments in Flexidea loans on Bondster lead to SIA Flexidea (registration number 40203061404, Riga), a small Latvian company that finances the invoices of businesses (factoring: it pays a business now for invoices its customers will pay later) and, since 2024, makes short business loans it calls FLEX LOAN. Flexidea’s own presentation on Bondster (“Investor Presentation Q1 2026”) says: “Buyback Guarantee provided by FLEXIDEA for Bondster investors”. A buyback is the lender’s own promise to buy the investment back if the borrower is late; here it is Flexidea’s promise, backed only by Flexidea. Bondster’s page of loan terms for Flexidea did not load when we tried it (21 November 2026), so after how many days the buyback applies, and whether investors hold a claim on Flexidea or on its customers, we could not confirm. Flexidea is 0.93% of the money invested on Bondster (Bondster’s chart “Structure of investments by providers”, no date shown, read 20 November 2026); Bondster publishes no amount outstanding per lender that we could read. Our research records that Flexidea’s Latvian business has also been funded through Debitum, another platform. Flexidea’s largest shareholder is SIA SM Capital (68.27%); a Belgian private equity fund, Helenos, holds 14.67%. It has subsidiaries in Poland, Romania and Latvia. Bondster is run by BONDSTER Marketplace s.r.o., Prague, which is not a bank and had negative equity at the end of 2025. This memo asks one question: what is the chance that SIA Flexidea fails to pay in the next 12 months, and why.
We ask six questions about every lender: does it earn enough, are its loans being repaid, does it have enough of its own money to absorb losses, how risky is its country, can we trust its numbers, and are there warning signs. Each is scored 1 to 5 and weighted. The four cards show how they land. Together they give 35 out of 100, which means 6–15%, the range we show for a D (about 13.7% on our method). D starts at 35, so Flexidea is exactly on the line between D and E. One step down would make it an E: earnings 2 to 1 would give 29, and the country 4 to 3 would give 32. The country is the close one: we score it 4 because about 57% of Flexidea’s lending assets at the end of 2024 were Latvian invoices (Latvia, grade B) and about 43% its loan to the Polish subsidiary (Poland, grade C); weighted, that is 3.6 out of 5. If more than half of its lending were Polish, the country would score 3 and Flexidea an E. Its other four questions are already at the lowest score. C needs 50, far away. The answers to the open questions below, which we have not yet asked, could move it either way.
Losses of €113,845 in 2023 and €265,623 in 2024; a profit of €246,733 in 2025 by register figures filed without notes or auditor’s report. Own money €1.17m, 17.6% of assets, but less than nothing once the software and the loans to its subsidiaries are taken out. Cash covered 3.5% of the loans due within a year at the end of 2024.
Provisions for doubtful invoices rose from €12,733 to €201,306 in 2024, 5.8% of the invoices financed. Its largest single asset, €2.51m, is an unsecured loan to its Polish subsidiary, which had negative net assets and unaudited accounts.
Latvia is grade B (3.74) in our country memo of 13 September 2026. About 43% of its lending assets is the loan to the Polish subsidiary; Poland is grade C (3.22) in our memo of 21 September 2026. Weighted, we score 4. Flexidea publishes no split of its business by country.
The audit opinion on 2024 cannot be read; 2025 is figures only. All its property is pledged to one lender, it guarantees €7m of its subsidiaries’ debts, and it is not supervised as a lender.
L'analyse complète couvre l'emprunteur ou l'entreprise, la garantie, les flux de trésorerie, les risques et un verdict. Connectez-vous pour la lire.
Information, et non conseil en investissement personnalisé. Le score IA évalue les documents publiés par la plateforme, peut se tromper et ne prédit pas les rendements.
Connectez-vous pour interroger l'IA sur les documents de ce projet.
Connexion👍 Oui · 0 👎 Non · 0
Lien affilié · capital à risque
Voir 5 projets →Mintos
Mintos
Commentaires · 0