
Bonus pågår
Kan säljas i förtid
- Risknivå
- Högst
- Risk–avkastning
- Dålig
- Börja från
- €10
Affiliatelänk · ditt kapital är i riskzonen
Se 3 projekt →Frågor om att investera? Fråga AI-guiden.
Hej! Jag är Crowdinforms AI-guide.
Logga in gratis för att fråga AI-guiden om plattformar, projekt och dina planer.
Svaren kommer från Crowdinforms kontrollerade data. Information, inte personlig investeringsrådgivning.
Letar… Något gick fel. Försök igen. {n} frågor kvar i dag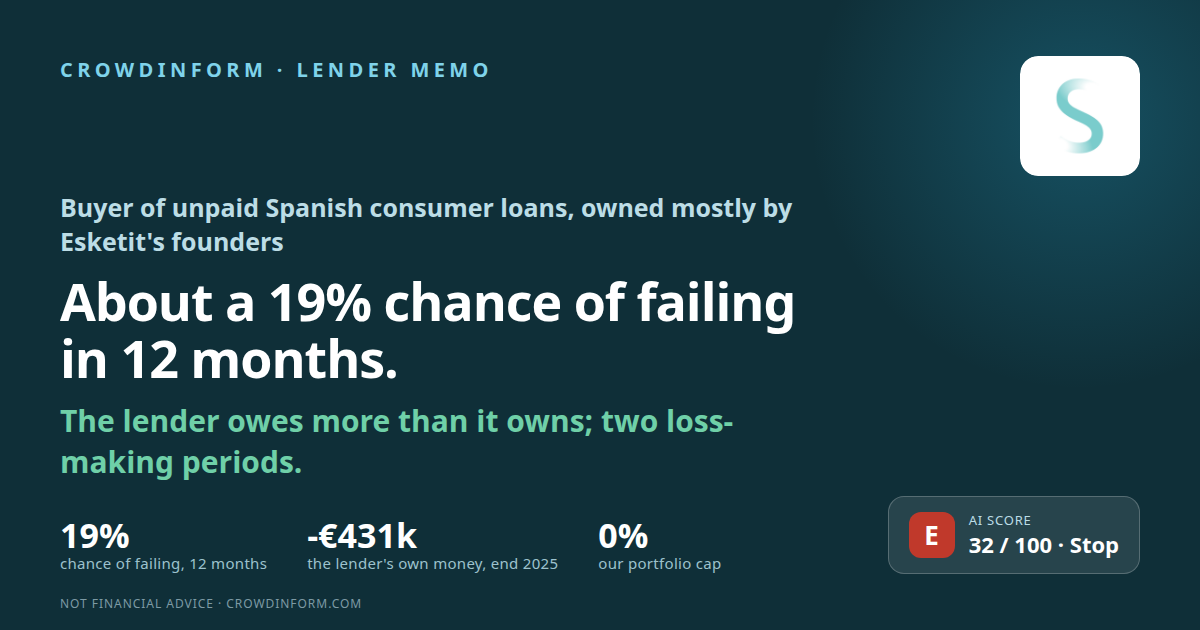
Lettland
Ditt kapital är i riskzonen. Räntan är avtalad, inte garanterad: om en låntagare inte betalar kan du förlora en del av eller alla dina pengar.
Vår AI ger det här projektet 32 av 100: Låg. Så fungerar AI-betyget
Information, inte personlig investeringsrådgivning. AI-betyget bedömer de dokument som plattformen publicerar, kan vara fel och förutspår inte avkastning.
Spanda Capital is a Latvian company (SIA Spanda Capital, registration number 40203507046, registered in September 2023) that raises money on Esketit and passes it to its Spanish subsidiary, Spanda Finance España, S.L.U. (Madrid, tax number B56658594). The Spanish company buys portfolios of consumer loans that borrowers have stopped paying, at a discount, and collects them over many years. Esketit calls Spanda “a venture established by Esketit co-founders Matiss Ansviesulis and Davis Barons”; the Latvian register shows their two holding companies with 40% each and Spanda’s chief executive, Matīss Krištobans, with 20%. Claim rights bought on Esketit lead to these two companies: SIA Spanda Capital is the lender, with a buyback promise (“Buyback: Yes”, “Group Guarantee: No”), and the Spanish company owed it €6.37m at the end of 2024. In June 2025 Esketit announced Spanda’s “largest loan offering to date”, about €7m. Esketit shows an average interest rate of 11% and does not publish how much Spanda owes investors today. This memo asks one question: what is the chance that Spanda fails to pay in the next 12 months, and why.
We ask six questions about every lender: does it earn enough, are its loans being repaid, does it have enough of its own money to absorb losses, how risky is its country, can we trust its numbers, and are there warning signs. Each is scored 1 to 5 and weighted. The four cards show how they land. Together they give 32 out of 100, which means about 19%.
The lender lost €211,786 in 2025 and €222,189 in its first period. Its owners’ money was −€431,175 at the end of 2025.
The portfolios bought in 2024 for €6.42m were carried 8.2% lower at the year end. Collections since then come only from the chief executive’s letters.
The loans and the borrowers are in Spain, grade C in our country memo of 21 September 2026.
One audited year for the Spanish company; register lines only for the lender. The two sets of books do not meet, and the owners are also founders of the platform.
Hela analysen tar upp låntagaren eller bolaget, säkerheten, kassaflödet, riskerna och ett omdöme. Logga in för att läsa den.
Information, inte personlig investeringsrådgivning. AI-betyget bedömer de dokument som plattformen publicerar, kan vara fel och förutspår inte avkastning.
Logga in för att fråga AI om projektets dokument.
Logga in👍 Ja · 0 👎 Nej · 0
Affiliatelänk · ditt kapital är i riskzonen
Se 3 projekt →Mintos
Mintos
Kommentarer · 0