What is smart investing? A practical 2026 guide
Discover what smart investing is and how it can grow your wealth. This 2026 guide reveals strategies for long-term financial success!
- Investing
Questions about investing? Ask the AI guide.
Hi! I'm the Crowdinform AI guide.
Sign in free to ask the AI guide about platforms, projects and your plans.
Answers come from Crowdinform's checked data. Information, not personal investment advice.
Looking it up… Something went wrong. Please try again. {n} questions left todayArticle
Discover why audit investment portfolios is crucial for serious investors. Uncover hidden inefficiencies and align your goals for better returns.
A portfolio audit is a systematic, diagnostic review of your holdings, fees, risk profile, and goal alignment. It goes far beyond checking whether your returns are up or down this quarter. Over 90% of analysed portfolios contain at least one consistently underperforming fund, simply because investors never looked closely enough. That statistic alone explains why auditing investment portfolios is one of the most valuable habits any serious investor can build. The audit process draws on standards used by regulated advisers, including documented suitability reviews and investment policy statement (IPS) monitoring, and applies them to your own holdings.
Portfolio audits surface problems that return-checking never will. When you only glance at total gains or losses, you miss the structural issues quietly eroding your wealth: fee drag, hidden overlaps, and allocation drift.
Fee drag is the most underestimated threat. A 1% difference in annual fees can reduce your ending portfolio value by 28% over 30 years. Alternative investment fees often exceed 2%, which means an unaudited portfolio holding several such funds may be losing a substantial share of net returns every single year.
Diversification quality matters more than quantity. Many investors hold 15 funds and believe they are well diversified. An audit frequently reveals that eight of those funds hold the same top-ten equities. True diversification, as discussed in real asset investing, requires reviewing actual underlying exposures, not just fund names.
The core benefits of a thorough portfolio audit include:
Pro Tip: Run a fee audit first. List every fund, its annual charge, and its three-year risk-adjusted return. This single exercise often produces the most immediate, tangible improvement to long-term outcomes.
Audit frequency is not a matter of preference. It is a matter of how quickly markets can move your portfolio away from its intended structure.
Experts recommend annual comprehensive audits combined with quarterly or monthly monitoring for allocation drift. Think of the annual audit as a financial annual physical: a full diagnostic that covers fees, risk, goal alignment, and performance benchmarking. The monthly or quarterly check is lighter, focused on whether any asset class has drifted beyond 5–10 percentage points from its target weight. Periodic sampled reviews at very low frequency are insufficient for compliance and for practical risk management. IPS drift can persist unnoticed between infrequent reviews, compounding the misalignment over time. Daily or monthly supervisory layers prevent this from becoming a structural problem.
A practical audit schedule looks like this:
Reactive auditing during market volatility is the least effective approach. Investors who audit only when markets fall tend to make decisions under stress, which increases the likelihood of selling at lows. A pre-scheduled audit calendar removes that temptation entirely.
A thorough audit follows a structured sequence. Skipping steps produces an incomplete picture and undermines the value of the exercise.
Collect every account statement, fund factsheet, and fee schedule. Investors with holdings across multiple platforms often discover positions they had forgotten. Consolidation is the foundation of an accurate audit.
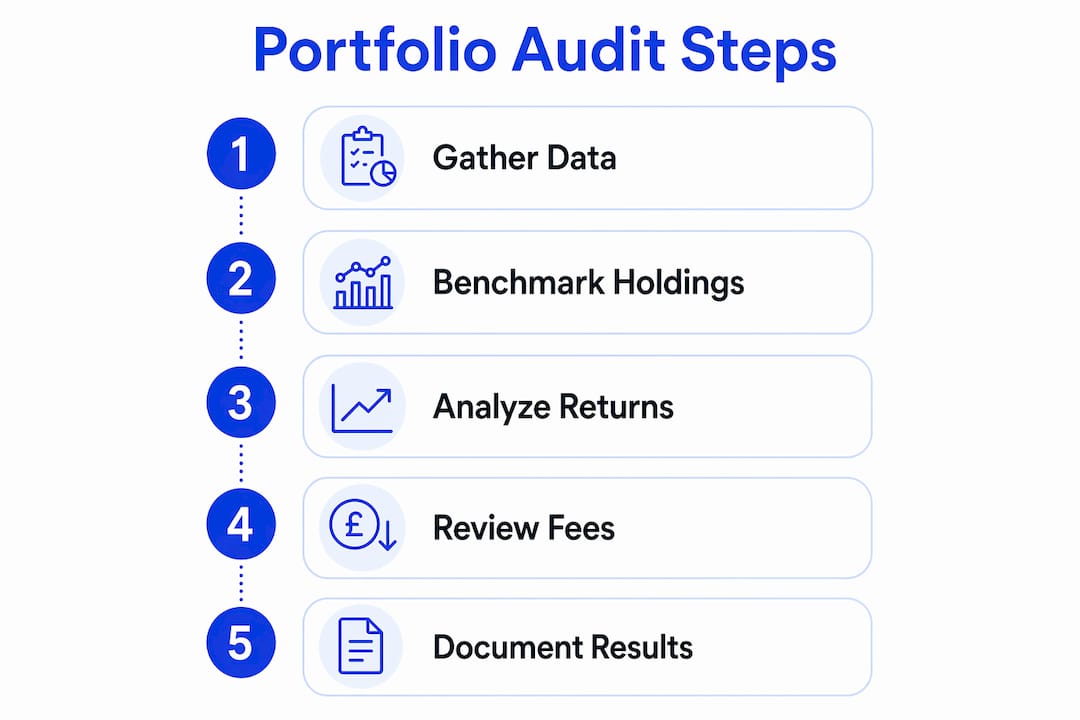
Compare every fund or asset against a relevant index. A global equity fund should be measured against the MSCI World Index, not against your portfolio's blended return. Benchmarking reveals which holdings are genuinely adding value and which are simply riding market momentum.
Raw returns mislead. A fund returning 12% with twice the volatility of its benchmark is not outperforming. Use metrics such as the Sharpe ratio to assess whether each holding is delivering adequate return per unit of risk. Understanding how to analyse investment platforms for smarter returns provides a useful framework for this step.
List every layer of cost: fund management charges, platform fees, adviser fees, and transaction costs. For multi-asset portfolios, fee layers can stack in ways that are not immediately visible from a single statement.
Portfolio monitoring is an active suitability function requiring documented evidence. Even a decision not to change a holding requires a recorded rationale. This is not bureaucracy. It is the discipline that separates reactive investors from deliberate ones.
Pro Tip: Record your audit findings in a simple spreadsheet with four columns: holding, benchmark, fee, and decision rationale. This log becomes your most valuable reference point at the next audit.
An audit without follow-through is just a report. The value lies in translating findings into deliberate adjustments.
Rebalancing is the most direct output of an audit. When allocation drift exceeds your target threshold, you sell the overweight asset class and reinvest in the underweight one. This is not market timing. It is disciplined adherence to a pre-agreed risk profile, and it is one of the clearest benefits of auditing portfolios over time.
The audit also informs hold-versus-sell decisions. A fund that has underperformed its benchmark for three consecutive years, after fees, with no structural reason to expect improvement, is a candidate for replacement. That conclusion is only reachable through a systematic audit, not through a quarterly glance at a performance chart.
Key ways to apply audit findings include:
Decisions not to trade must be logged as deliberately as trades themselves. Regulators and advisers ask about inaction as frequently as they ask about action. This discipline also protects you from your own hindsight bias when reviewing past decisions.
A portfolio audit is the single most effective tool investors have for identifying hidden inefficiencies, controlling fees, and maintaining deliberate alignment between their holdings and their financial goals.
| Point | Details |
|---|---|
| Audits reveal hidden problems | Over 90% of unaudited portfolios contain at least one consistently underperforming fund. |
| Fee drag compounds silently | A 1% annual fee difference reduces portfolio value by 28% over 30 years; audit fees first. |
| Frequency matters | Annual comprehensive audits plus monthly drift checks prevent prolonged misalignment. |
| Documentation is non-negotiable | Log every decision, including inaction, at the time it is made, not retrospectively. |
| Audit findings must drive action | Rebalance, replace, or hold based on evidence, not market sentiment or gut feeling. |
I have reviewed a lot of portfolios over the years, and the pattern is almost always the same. Investors check their returns regularly. They almost never audit their portfolios. Those are two entirely different activities, and confusing them is expensive.
Return-checking only shows past gains or losses. It tells you nothing about whether your risk profile has drifted, whether your fees are eating your compounding, or whether three of your funds are essentially holding the same assets. A genuine audit answers all of those questions.
The habit I find most underrated is contemporaneous decision logging. Most investors, even experienced ones, do not record why they made a decision at the time they made it. When they review the portfolio six months later, they reconstruct a rationale that sounds reasonable but may not reflect what they actually knew or believed at the time. A 30-second note written at the moment of decision is worth more than a 30-minute reconstruction later.
My honest advice: treat your annual audit as a non-negotiable appointment, the same way you treat a tax return deadline. Do not wait for a market correction to prompt it. The investors who audit proactively are the ones who avoid panic-selling at the worst moments, because they already know their portfolio is structurally sound. If you are not confident running a full audit yourself, a fee-only financial adviser can conduct one without the conflict of interest that comes from commission-based advice. The importance of portfolio audits is not a niche concern for institutional investors. It is the foundation of smart investing at every level.
— Jevgenijs
Crowdinform aggregates data from over 500 European crowdfunding and investment platforms, giving you a consolidated view of projects, returns, and platform credibility in one place.
For investors who want to build genuine audit discipline, Crowdinform's AI copilot reviews individual projects and surfaces the structural details that matter: fee structures, risk profiles, and performance benchmarks. You can explore investment projects across Europe with the confidence that comes from aggregated, independently reviewed data. Whether you are conducting your first audit or refining an existing process, Crowdinform gives you the information layer that makes each review faster, more thorough, and more reliable.
A portfolio audit is a structured diagnostic review of your investments that assesses fees, risk alignment, diversification quality, and goal alignment. It goes beyond return-checking to evaluate the structural integrity of your holdings.
Annual audits catch fee drag, allocation drift, and underperforming funds before they compound into significant losses. Combined with quarterly monitoring, they keep your portfolio aligned with your financial goals throughout the year.
Allocation drift occurs when market movements shift your asset class weights away from their targets. Drift beyond 5–10 percentage points from target weights signals the need for rebalancing to restore your intended risk profile.
Yes. Regulators and advisers treat inaction as a deliberate decision requiring documented rationale. A contemporaneous log of why you chose not to change a holding is as important as recording why you made a trade.
Yes, with the right data and a clear framework. Gather all account statements, benchmark each holding against a relevant index, review fees in full, and document your findings. For complex or large portfolios, a fee-only adviser adds significant value.
Capital at risk. Crowdfunding investments are not covered by deposit guarantee schemes, can lose part or all of their value, and may be hard to sell before the end of their term. This guide is information, not personal investment advice.
Was this helpful?

Eugene Sokolovs Expert
Founder of Crowdinform
Keep reading
Discover what smart investing is and how it can grow your wealth. This 2026 guide reveals strategies for long-term financial success!
Here’s your investor-focused round-up of what’s newly raising, which platforms updated, and project milestones across Europe’s top crowdfunding platforms. Skim the first section on fresh listings if you’re hunting for deals, then dive into platform updates and portfolio wins. 🚀
 Video
Want to invest in the next Google, Facebook, or Amazon—before they explode? Early-stage investments can bring massive returns, and you’re in the right place to catch them! In this video, we’ve gathered the top startup deals currently raising funds on licensed equity crowdfunding platforms. These startups are solving real problems—and they’re offering you a chance to become a shareholder and grow with them. Let’s explore the best opportunities out there and maybe even spot the next big thing before the rest of the world does!

Comments · 0