
Regulated
Can sell early
- Risk level
- Highest
- Risk-return
- Medium
- Start from
- €500
Questions about investing? Ask the AI guide.
Hi! I'm the Crowdinform AI guide.
Sign in free to ask the AI guide about platforms, projects and your plans.
Answers come from Crowdinform's checked data. Information, not personal investment advice.
Looking it up… Something went wrong. Please try again. {n} questions left todayFunding closed on 30 Sep 2026. The page stays up for reference; similar open projects are below.
Spain
20 of the company
Check the documents for how the shares are held and what rights they give.
The platform estimates up to 13×
Usually only if the company is sold or listed. Estimates are the platform's own claims.
Around 2029
Only if a sale or listing happens; shares are hard to sell before that.
Capital at risk. Most startups fail; estimates are the platform's own claims. Shares are hard to sell before an exit.
Our AI gives this project 63 out of 100: Medium. How the AI score works
Information, not personal investment advice. The AI score rates the documents the platform publishes, can be wrong, and does not predict returns.
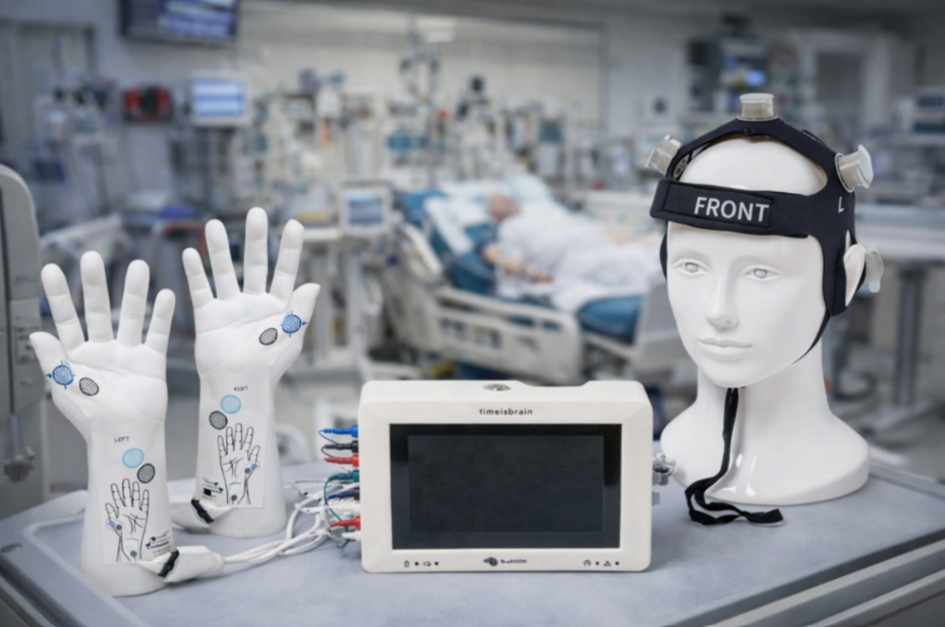
A portable, real-time device that reads a brain-signal biomarker (N20) to help decide which stroke patients should receive clot-removal surgery.
Sector: Medtech (Class IIb device / NACE 7210) · Stage: Seed / pre-CE-mark, pre-revenue · HQ: Badalona / Barcelona, Spain · Raise: €2.5M target (€430k via Capital Cell)
|
AI SCORE |
Why this score: |
|
|
|
|
63 / 100 |
|
|
⭐ Moderate |
|
|
|
|
|
|
|
|
ℹ️ This is not investment advice. The purpose of this overview is to help potential investors preselect crowdfunding projects quickly without making a final investment decision. Before investing, the final selected project should be reviewed in detail based on the information provided by the company on the respective crowdfunding platform. AI can make mistakes, so you need to double-check data. |
Time is Brain, S.L. (TiB) is a Spanish medtech spin-off from Hospital Germans Trias i Pujol, founded in July 2020 by neurologists Alicia Martínez Piñeiro (CEO), Antoni Dávalos (CSO) and Jaume Coll-Cantí. It has developed BraiN20®, a portable, non-invasive device — a tablet-style unit plus single-use electrodes — that automatically records and interprets the N20 somatosensory-evoked potential, an electrical brain signal the company positions as a real-time marker of how much brain tissue is still salvageable after an acute ischemic stroke. The intended use is to help clinicians decide which stroke patients will benefit from endovascular thrombectomy (EVT), the gold-standard clot-removal procedure. The clinical basis is the peer-reviewed PROMISE study (223 patients, published in Stroke: Vascular and Interventional Neurology, 2023), where the N20 signal predicted good functional recovery with high sensitivity. The company reports the device increases treatment-eligible patients by up to 15%, saves 60–140 minutes of time-to-treatment, and raises treatment success by 26% — these are company-stated figures whose full derivation is not in the provided materials. The device is pre-CE-mark; the company expects CE Mark during 2026. This €2.5M round (with €430k opened via the Capital Cell platform) is to fund market entry, runway to CE Mark, first commercial sales, and team build-out.
|
Target return |
Time horizon |
Target basis |
AI view on reaching this goal |
|
🎯 ~10x |
⏱ 5–7 yrs |
Mix — Two scenarios presented default x10 and ~x13 provided by company (high level). |
Plausible only on a clean CE-mark-and-commercialisation path; binary regulatory and adoption risk make the outcome wide, from total loss to a multiple. |
|
⚠️ Why aim for ~10x? Startup investing is high risk. Most early-stage companies fail or return little. A small number of winners must compensate for the losers, so each individual investment is typically targeted at roughly 10x over 5–7 years. A lower target across a portfolio of risky bets usually does not produce a positive overall return. This is why we apply a 10x / 5–7 year target when the company does not specify its own. |
|
Sector heuristic |
For a pre-CE medical device, a ~10x outcome typically requires reaching CE Mark, then either meaningful unit sales across several markets or a trade sale to a larger neuro/medtech acquirer. Hospital-by-hospital adoption is slow; centralised reimbursement (NICE, CADTH, CMS) is the faster route but demands cost-effectiveness evidence the company does not yet hold. |
|
Current key metric |
Pre-revenue. Clinical proof exists (PROMISE, n=223, published 2023); device-specific validation (PROMISE20 / PROMISE-GLOBAL) was ongoing per public trial registries, and CE Mark is not yet obtained (as of June 2026). |
|
Required scale at exit |
On a €12M pre-money, a ~10x equity return implies the company being worth roughly €120M+ at exit — achievable only with CE Mark, demonstrated clinical/economic value, and either multi-market sales traction or acquisition interest. |
|
Implied IRR |
A 10x over 5–7 years implies roughly a 39–58% annualised return — the high bar early-stage equity must target to compensate for the high failure rate. |
Exit scenario (company-stated)
|
Company-stated exit case |
The company outlines a potential exit by 2030 in the €200M–€400M range, with upside toward ~€500M if BraiN20® becomes an established part of the EVT treatment workflow or attracts competitive bidding among buyers. Named potential acquirers span neurovascular devices (Medtronic, Stryker, Johnson & Johnson MedTech), neurodiagnostics (Nihon Kohden) and imaging/workflow (GE HealthCare, Philips). This is a company-stated scenario, not an independent valuation. |
|
Conditions attached |
Explicitly conditional on CE Mark and US clearance, robust stroke-specific clinical validation, and demonstrable early commercial traction (install base and consumable usage). None of these conditions is yet met as of this memo. |
|
Gross vs net multiple |
The headline multiples are gross and undiluted. A €200M exit is roughly 14x the current ≈€14.5M post-money valuation only if your stake is never diluted. Because the company states this round is runway to its next funding round, your stake will almost certainly be diluted before any exit, so the multiple you would ac… |
The full review covers the borrower or company, the security, the cash flow, the risks and a verdict. Sign in to read it.
Information, not personal investment advice. The AI score rates the documents the platform publishes, can be wrong, and does not predict returns.
Sign in to ask the AI about this project's documents.
Sign in👍 Yes · 0 👎 No · 0
Sowefund
Raising €9m
Sowefund
Raising €600k
Sowefund
Raising €750k