
Bono activo
- Nivel de riesgo
- Alto
- Riesgo-rentabilidad
- Media
- Desde
- €10
Enlace de afiliado · capital en riesgo
Ver 11 proyectos →¿Preguntas sobre inversión? Pregunte a la guía IA.
¡Hola! Soy la guía de IA de Crowdinform.
Inicia sesión gratis para preguntar a la guía IA sobre plataformas, proyectos y tus planes.
Las respuestas proceden de los datos verificados de Crowdinform. Información, no asesoramiento de inversión personalizado.
Buscando… Algo ha fallado. Inténtelo de nuevo. {n} preguntas restantes hoy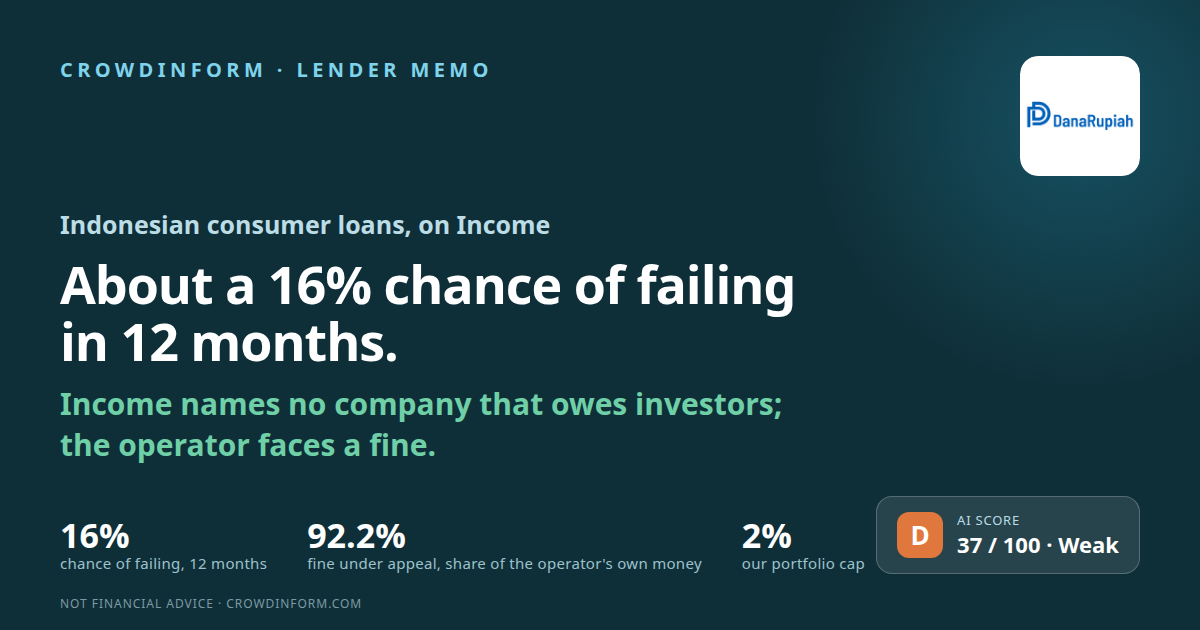
Indonesia
Capital en riesgo. El tipo está pactado, no garantizado: si un prestatario incurre en impago, puede perder una parte o la totalidad de su dinero.
Nuestra IA da a este proyecto 37 de 100: Baja. Cómo funciona la puntuación de la IA
Información, no asesoramiento personalizado de inversión. La puntuación IA valora los documentos que publica la plataforma, puede equivocarse y no predice la rentabilidad.
This memo is unusual, and we say so first. Income’s page for DanaKredi, read on 16 November 2026, names no company that owes investors. It says: “The loans are secured by assignment agreement to the investor with SPV controlling the cashflow”. An SPV is a special-purpose company; the page does not name it. The page does not use the words “buyback” or “guarantee” for this lender. Income’s general security page says every loan on Income carries a buyback obligation of the lender after 60 days; which company would owe it here is not named, and Income does not guarantee it. The only audited accounts we found are those of PT Pindar Berbagi Bersama (formerly PT Layanan Keuangan Berbagi), the company licensed by Indonesia’s financial regulator, OJK, to run the DanaKredi platform, which was called DanaRupiah until 2026. By its own accounts this company is an agent paid a platform fee: it does not carry the loans and bears none of their losses. So the charts and ratios in this memo are the operator’s, and they are not the accounts of whoever owes investors. Income also publishes short sheets headed “Un-Audited” for a “Consolidation” that the 2024 and 2025 sheets label with four short names, “PT LKB, Tech Co, PT MWI, Apt Co”; we found them unreliable and quote them only as un-audited. The chain, as far as the documents show it: investor on Income, then an unnamed SPV, then loans to individuals in Indonesia made through the DanaKredi platform; the operator stands beside the chain. Income publishes no amount per lender that we could read; Income’s monthly post for October 2026 gives the shares of its five largest lenders. DanaKredi is not among them, and the smallest of the five had 9.43% of the €33,720,192 that investors held on 31 October 2026. So DanaKredi had no more than that share, which is no more than about €3.2m by our arithmetic. That is a ceiling, not an estimate of the amount. The same post says €0.80M of DanaKredi loans were funded in October. Income’s help page, read on 16 November 2026, states that it “is not regulated by a financial authority”. This memo asks one question: what is the chance that DanaKredi fails to pay in the next 12 months, and why.
We ask six questions about every lender: does it earn enough, are its loans being repaid, does it have enough of its own money to absorb losses, how risky is its country, can we trust its numbers, and are there warning signs. Each is scored 1 to 5 and weighted. The four cards show how they land. Together they give 37 out of 100, which means about 16%. D runs from 35 to 49, so the grade is D, 2 points above E. Three of the six scores are our “no evidence” score of 2, because the accounts we have are not those of the company that owes investors. One step down on any one of them would make the grade an E: with earnings scored 1 instead of 2 the score would be 31, and with the loan book or the cushion scored 1 it would be 33. Earnings is the closest call. The operator lost money in 2024 and its income fell 55.5% in 2025; it also made a small profit in three of the four years and has no borrowings, so we keep 2. No single step up reaches C.
No accounts for the company that owes investors. The operator made Rp 626,972,679 in 2025 on income of Rp 60,112,107,479, after a loss in 2024. Its owners’ money is Rp 15,070,269,633; the fine under appeal is Rp 13.9 billion.
No evidence either way: no document we read shows arrears or losses on the loans, so this question gets our “no evidence” score of 2.
Indonesia is grade D in our country memo: the regulator sets the price of online loans, a second authority has fined 97 lenders over past pricing, and the rupiah keeps losing ground to the euro.
The obligor is not named. The notes to the operator’s accounts for 2023 to 2025 are not published. The group sheets are un-audited and do not add up from year to year. Income’s page gives two figures for the junior share.
El análisis completo cubre al prestatario o la empresa, la garantía, el flujo de caja, los riesgos y un veredicto. Inicie sesión para leerlo.
Información, no asesoramiento personalizado de inversión. La puntuación IA valora los documentos que publica la plataforma, puede equivocarse y no predice la rentabilidad.
Inicie sesión para preguntar a la IA sobre los documentos de este proyecto.
Iniciar sesión👍 Sí · 0 👎 No · 0
Enlace de afiliado · capital en riesgo
Ver 11 proyectos →Mintos
Mintos
Comentarios · 0