
Venta anticipada
- Nivel de riesgo
- Muy alto
- Riesgo-rentabilidad
- Mala
- Desde
- €10
Enlace de afiliado · capital en riesgo
Ver 8 proyectos →¿Preguntas sobre inversión? Pregunte a la guía IA.
¡Hola! Soy la guía de IA de Crowdinform.
Inicia sesión gratis para preguntar a la guía IA sobre plataformas, proyectos y tus planes.
Las respuestas proceden de los datos verificados de Crowdinform. Información, no asesoramiento de inversión personalizado.
Buscando… Algo ha fallado. Inténtelo de nuevo. {n} preguntas restantes hoy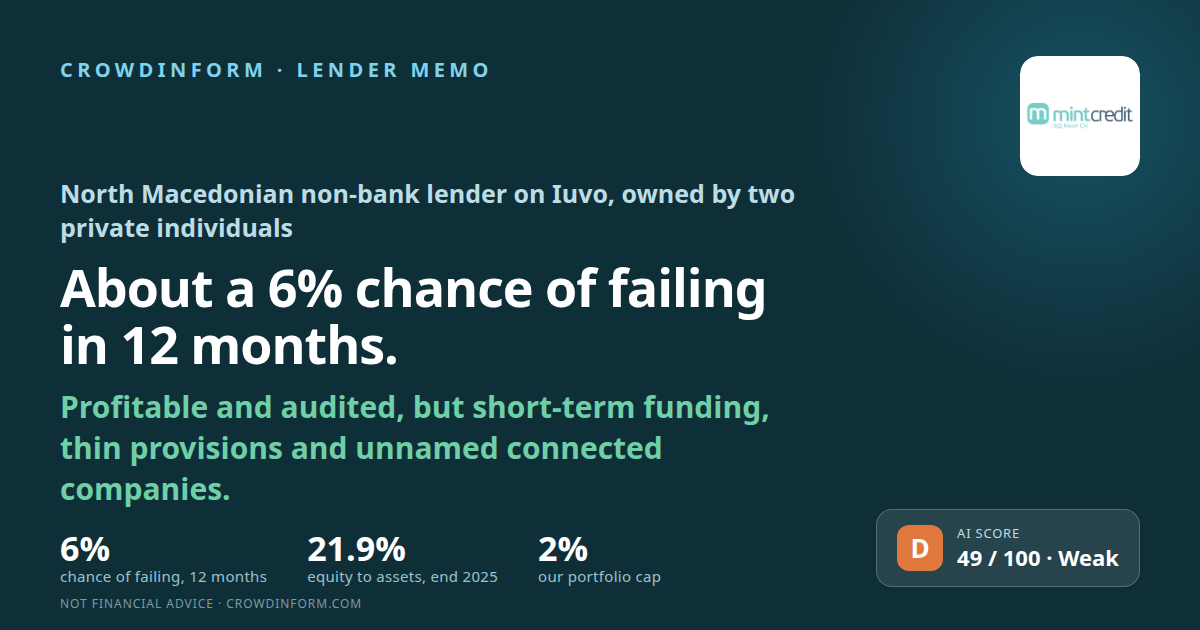
Macedonia del Norte
Capital en riesgo. El tipo está pactado, no garantizado: si un prestatario incurre en impago, puede perder una parte o la totalidad de su dinero.
Nuestra IA da a este proyecto 49 de 100: Baja. Cómo funciona la puntuación de la IA
Información, no asesoramiento personalizado de inversión. La puntuación IA valora los documentos que publica la plataforma, puede equivocarse y no predice la rentabilidad.
Financial Company MINT SN DOO Bitola, company number (PIN) 7172451, formerly SN Finansii DOO Bitola, is a licensed non-bank lender (a “financial company”) in North Macedonia. Its 2025 accounts list its activities as loans, credit cards, factoring and issuing guarantees; Iuvo’s page says it lends to people and to small companies, online and in “over 14 physical branches”. Iuvo shows Mint Credit’s receivables with a “Buyback”, and on the documents we could read, that buyback is Mint Credit’s own promise: nobody else is named as standing behind it. The money takes this route. Investor → IUVO GROUP OÜ (Estonia, 14063375), which runs the Iuvo platform → Mint SN DOO Bitola, which lists the loans and promises to buy them back → borrowers in North Macedonia, with loans of MKD 1,197.6m (about €19.5m) on its balance sheet at the end of 2025. Iuvo publishes two assignment agreements of 22 April 2026, one in which the investor buys the claim on the borrower and the originator buys it back, and one in which the claim is on the originator itself; which one applies to Mint Credit is in the key terms behind the investor login, which we have not read. Mint Credit’s accounts do not name Iuvo or any P2P platform, so we cannot see where investors’ money sits in them. Mint Credit is owned by two private individuals, 50% each, as the 2025 accounts show. It is not a company of Management Financial Group (MFG), the Bulgarian group that owns Iuvo’s operator: the “group guarantee” Iuvo describes for MFG’s lenders does not cover it. Mint Credit was 1.42% of the amount of receivables listed on Iuvo in the third quarter of 2026 (Iuvo’s quarterly portfolio, 13 October 2026); that is new listings, not an amount owed, and Iuvo publishes no amount outstanding per lender. Iuvo’s footer says: “IUVO GROUP OÜ is not a bank, investment firm, crowdfunding service provider or payment institution, and its activity is not subject to supervision as a licensed financial institution.” This memo asks one question: what is the chance that Mint Credit fails to pay in the next 12 months, and why.
We ask six questions about every lender: does it earn enough, are its loans being repaid, does it have enough of its own money to absorb losses, how risky is its country, can we trust its numbers, and are there warning signs. Each is scored 1 to 5 and weighted. The four cards show how they land. Together they give 49 out of 100, which means about 6%. D runs from 35 to 49, so the grade is D, 1 point below C: within reach of the next grade. One step up on any one of our own five questions would make it a C: trust in the numbers (2 to 3) would give 51, warning signs (2 to 3) 50, the loans or the cushion (2 to 3) 53, earnings (3 to 4) 55. One step down on earnings would give 43: still D.
Profit after tax rose to MKD 64.8m in 2025 (about €1.05m), 15.6 denars of every 100 of income. But interest took 21.1 of every 100, up from 11.7 in 2023, and MKD 906m of borrowings fell due within a year against MKD 3.4m of cash.
At the end of 2024, 10.5% of the loans were being pursued in court, while the allowance for losses was 1.5% of the book; at the end of 2023 there was none. The 2025 accounts do not show the allowance or how late the loans are.
North Macedonia is grade C (3.09) in our country memo of 13 September 2026, which scores 3 out of 5 here. A currency pegged to the euro since 2002, and a state that caps the cost of a loan and fined 16 of 26 licensed lenders in the first five months of 2026.
Two audited years whose figures add up. But the 2025 report has gaps and slips, the notes say there are no related-party dealings while the statements show them, a new auditor signed 2025, and the platform is not supervised.
El análisis completo cubre al prestatario o la empresa, la garantía, el flujo de caja, los riesgos y un veredicto. Inicie sesión para leerlo.
Información, no asesoramiento personalizado de inversión. La puntuación IA valora los documentos que publica la plataforma, puede equivocarse y no predice la rentabilidad.
Inicie sesión para preguntar a la IA sobre los documentos de este proyecto.
Iniciar sesión👍 Sí · 0 👎 No · 0
Enlace de afiliado · capital en riesgo
Ver 8 proyectos →Mintos
Mintos
Comentarios · 0