
Regulada
Bono activo
Venta anticipada
- Nivel de riesgo
- Alto
- Riesgo-rentabilidad
- Media
- Desde
- €50
Enlace de afiliado · capital en riesgo
Ver 54 proyectos →¿Preguntas sobre inversión? Pregunte a la guía IA.
¡Hola! Soy la guía de IA de Crowdinform.
Inicia sesión gratis para preguntar a la guía IA sobre plataformas, proyectos y tus planes.
La IA responde a partir de los datos verificados de Crowdinform. Puede cometer errores. Información, no asesoramiento de inversión personalizado.
Buscando… Algo ha fallado. Inténtelo de nuevo. {n} preguntas restantes hoy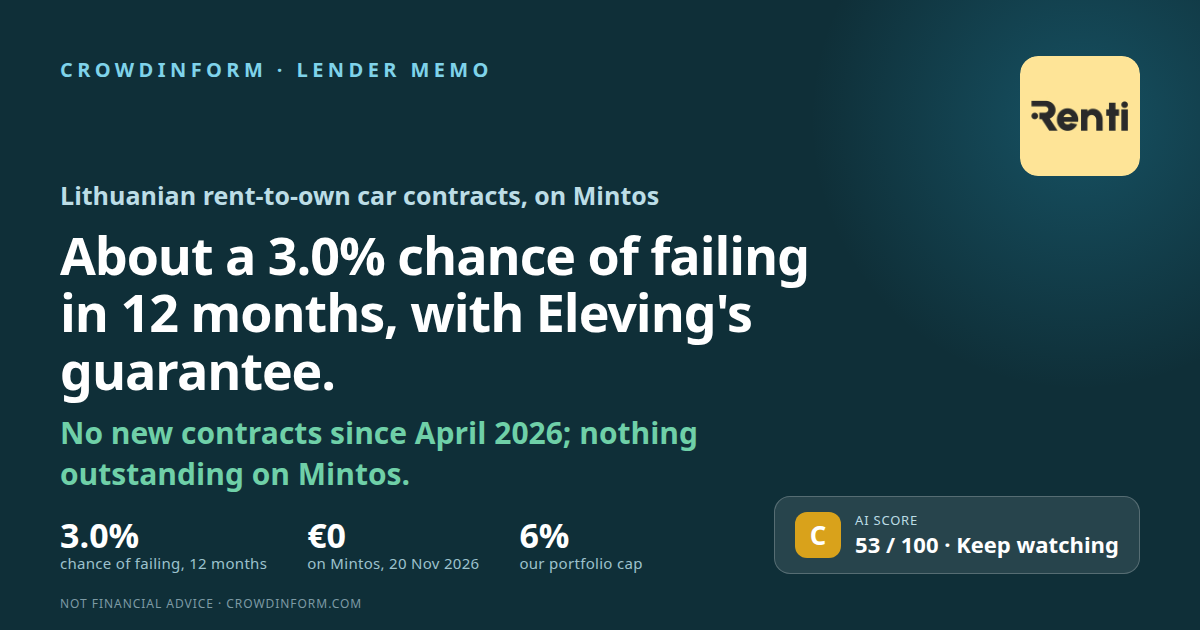
Lituania
Capital en riesgo. El tipo está pactado, no garantizado: si un prestatario incurre en impago, puede perder una parte o la totalidad de su dinero.
Nuestra IA da a este proyecto 53 de 100: Media. Cómo funciona la puntuación de la IA
Información, no asesoramiento personalizado de inversión. La puntuación IA valora los documentos que publica la plataforma, puede equivocarse y no predice la rentabilidad.
UAB Renti rents cars to people in Lithuania on long contracts with the right to buy at the end — an average of about €7,000 over 55 months, at about €282 a month, on cars that average 16 years old. Since 1 April 2026 it no longer signs new contracts, so it is now collecting its existing book. It has almost no staff of its own (2 on average in 2025; most of its people are employed by mogo LT). Mintos investors lent to it through a Mintos company, and on 20 November 2026 Mintos listed it as active and issuing notes but showed €0 outstanding, without giving a reason. This memo asks one question: what is the chance it fails to pay its lenders back in the next 12 months, and why.
The news first. Renti's 2025 accounts note that "as of 1 April 2026, the Company no longer enters into new vehicle management and usage agreements". It is a company in run-off: it collects the contracts it has and repays the money it borrowed. And on 20 November 2026 Mintos's public list showed €0 outstanding on Renti notes, against €5.8m on 13 September 2026, with no average return shown. Mintos still lists Renti as active and issuing notes and gives no reason for the zero. This memo applies to any Renti notes you hold or buy.
The good part: the 2025 audit is clean and the year was profitable. UAB ROSK Consulting signed an unmodified opinion on 18 April 2026, with no going-concern paragraph. Profit was €0.77m — €0.68m before tax and more after a tax credit — after €0.03m in 2024. Renti kept €8.48 of every €100 of income, up from €0.31. Owners' money is €4.05m, 16.4% of what the company owns, and the cars are its security.
Then the weaker part. Contracts more than sixty days late were 5.0% of the book at the end of 2025, up from 2.8% a year earlier (the audited tables; the Mintos prospectus showed 7.66% on its own basis). New contracts have not been insured against default since 1 January 2025, so those losses are Renti's own, and the money set aside is €0.56m, 2.5% of the book. The margin is thin: income only has to fall about 7.5% for the year to turn to a loss.
Who lends to Renti. About 71% of its borrowing — €14.04m of €19.89m — is one loan from its parent, UAB mogo LT, at 13%, due in October 2030. Last time we wrote that mogo LT's 2024 audit carried a going-concern doubt; its 2025 audit, signed 22 April 2026, carries none. mogo LT still has one of our vetoes in its own memo, because almost all it has lent is this loan to Renti.
The guarantee is what gives the second number. The Mintos base prospectus of 1 April 2026 says Eleving Group S.A. guarantees Renti's obligations towards the Mintos lender, the issuer and Mintos itself — and that it is not guaranteeing their obligations to investors. Eleving is rated B by Fitch, outlook positive, so under our method the group's number sets the odds: about 1 in 33. From 20 November 2026 Lithuania's new consumer-credit rules apply; because Renti writes no new contracts, a lower cost cap would touch it far less than we feared in October.
Six things would stop us scoring at all and send the answer straight to E — a default, a missed payment to a platform, a regulator pulling a licence, an auditor doubting the company can continue, a broken promise to a lender, or accounts we cannot rely on. None of them applies to this company — though one of them applies to the parent that lends to it, and section 5 says what that means. Two things would pull the answer the other way, a guarantee from a stronger owner or a credit rating. One of them does apply, and it is the only reason this memo gives a second number.
Profit of €0.77m in 2025 after €0.03m in 2024, now audited — but income can fall only about 7.5% before a loss, and the book is shrinking.
Contracts more than sixty days late rose from 2.8% to 5.0% of the book in 2025, and new contracts are no longer insured.
Grade A (4.25 out of 5) — the lowest-risk country we cover. New consumer-credit rules from 20 November 2026; Renti writes no new contracts.
Funded 71% by its parent; the parent's 2025 audit has no going-concern doubt. Renti guarantees Eleving's 2030 bonds.
El análisis completo cubre al prestatario o la empresa, la garantía, el flujo de caja, los riesgos y un veredicto. Inicie sesión para leerlo.
Información, no asesoramiento personalizado de inversión. La puntuación IA valora los documentos que publica la plataforma, puede equivocarse y no predice la rentabilidad.
Inicie sesión para preguntar a la IA sobre los documentos de este proyecto.
Iniciar sesión👍 Sí · 0 👎 No · 0
Enlace de afiliado · capital en riesgo
Ver 54 proyectos →Mintos
Mintos
Comentarios · 0