
Réglementé
- Niveau de risque
- Très élevé
- Risque-rendement
- Mauvais
- Dès
- €10
Des questions sur l'investissement ? Demandez au guide IA.
Bonjour ! Je suis le guide IA de Crowdinform.
Connectez-vous gratuitement pour interroger le guide IA sur les plateformes, les projets et vos plans.
L’IA répond à partir des données vérifiées de Crowdinform. Elle peut se tromper. Information, pas un conseil en investissement personnalisé.
Recherche en cours… Une erreur s'est produite. Veuillez réessayer. {n} questions restantes aujourd'hui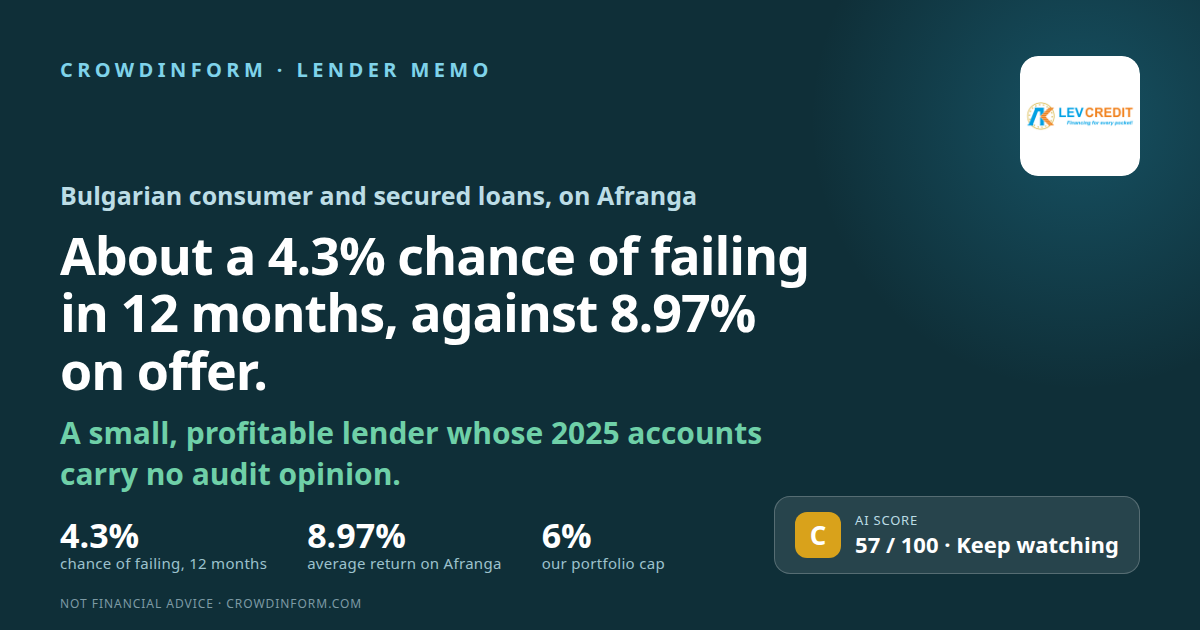
Bulgarie
Capital à risque. Le taux est convenu, et non garanti : si un emprunteur fait défaut, vous pouvez perdre une partie ou la totalité de votre argent.
Notre IA attribue à ce projet 57 sur 100 : Moyen. Comment fonctionne le score IA
Information, et non conseil en investissement personnalisé. Le score IA évalue les documents publiés par la plateforme, peut se tromper et ne prédit pas les rendements.
Lev Credit EOOD is a small lender in Shumen, in northern Bulgaria — about half its consumer lending secured on property, the rest unsecured, run by 16 people from a head office and 8 branches. Investors reach it through Afranga, where there is no buyback and no guarantee from anyone. This memo asks one question: what is the chance it fails to pay its lenders back in the next 12 months, and why.
Start with what is not here. Most memos in this series end up discussing a buyback promise, or a parent's guarantee, or both. Lev Credit has neither. Afranga does not offer a buyback, its owner DETEKS OOD has given no guarantee, and the company is independent of the group that runs the platform. An Afranga investor's money rests on this company alone — which is why the rest of this page is about the company and nothing else.
For its size it is unusually well funded. Owners' money is €951k of €1,302k of assets — 73%. Afranga investors have lent €296k, about 31% of the owners' money, and there is no bank and no bond. The qualification is the size itself. €951k is not much: a single large secured loan, at up to €50k, is 5% of the whole cushion, and the business runs on 16 people.
The latest year has no audit report, and its figures moved. The 2025 annual report, dated 26 January 2026, carries no audit opinion. The interim published in April then restated 2025 profit from BGN 499k — about €255k — to €267k, about €12k, with no reason given. The 2024 accounts were audited and the opinion was clean. Accounts have also reached the Commercial Register between one and three and a quarter years late; 2023 and 2024 both arrived on 10 March 2026.
2025 looks better than the business got. Of every €100 of income the company kept €13.98 in 2024 and €40.45 in 2025 — but the second figure is flattered, because provisions were released rather than charged. The bad-debt line was €34.49 of every €100 in 2024 and a credit of €−4.39 in 2025. Strip that out and the year is good rather than remarkable.
A quarter of the loan book has been in default for more than half a year. Loans more than 180 days late were 46.6% of the gross book at the end of 2024 and 24.5% in March 2026. That share is falling because the book is growing around it, not because the old loans are being collected — €312k of the €394k is more than 360 days late. It is 94% provided for, so it carries almost nothing on the balance sheet.
Six things would stop us scoring at all and send the answer straight to E — a default, a missed payment to a platform, a regulator pulling a licence, an auditor doubting the company can continue, a broken promise to a lender, or accounts we cannot rely on. None of them applies — though one came within a year of applying, and section 4 says which. Two things would pull the answer the other way, a guarantee from a stronger owner or a credit rating. Neither applies. Nobody guarantees this company and nobody has promised to buy a bad loan back, so there is no second number on this page and nothing standing behind the first.
Owners' money is 73% of assets and the business is profitable — with 2025 helped by released provisions.
Nearly a quarter of the gross book is more than 180 days late. It is old, and 94% provided for.
Grade C (3.30 out of 5). The euro since January 2026, a 52% cost cap, and a new consumer-credit law in parliament.
A 2024 payout of 2.9 times that year's profit, accounts filed late, and 2025 figures revised without explanation.
L'analyse complète couvre l'emprunteur ou l'entreprise, la garantie, les flux de trésorerie, les risques et un verdict. Connectez-vous pour la lire.
Information, et non conseil en investissement personnalisé. Le score IA évalue les documents publiés par la plateforme, peut se tromper et ne prédit pas les rendements.
Connectez-vous pour interroger l'IA sur les documents de ce projet.
Connexion👍 Oui · 0 👎 Non · 0
Mintos
Mintos
Commentaires · 0