
Regulada
Bono activo
Venta anticipada
- Nivel de riesgo
- Alto
- Riesgo-rentabilidad
- Media
- Desde
- €50
Enlace de afiliado · capital en riesgo
Ver 11 proyectos →¿Preguntas sobre inversión? Pregunte a la guía IA.
¡Hola! Soy la guía de IA de Crowdinform.
Inicia sesión gratis para preguntar a la guía IA sobre plataformas, proyectos y tus planes.
Las respuestas proceden de los datos verificados de Crowdinform. Información, no asesoramiento de inversión personalizado.
Buscando… Algo ha fallado. Inténtelo de nuevo. {n} preguntas restantes hoy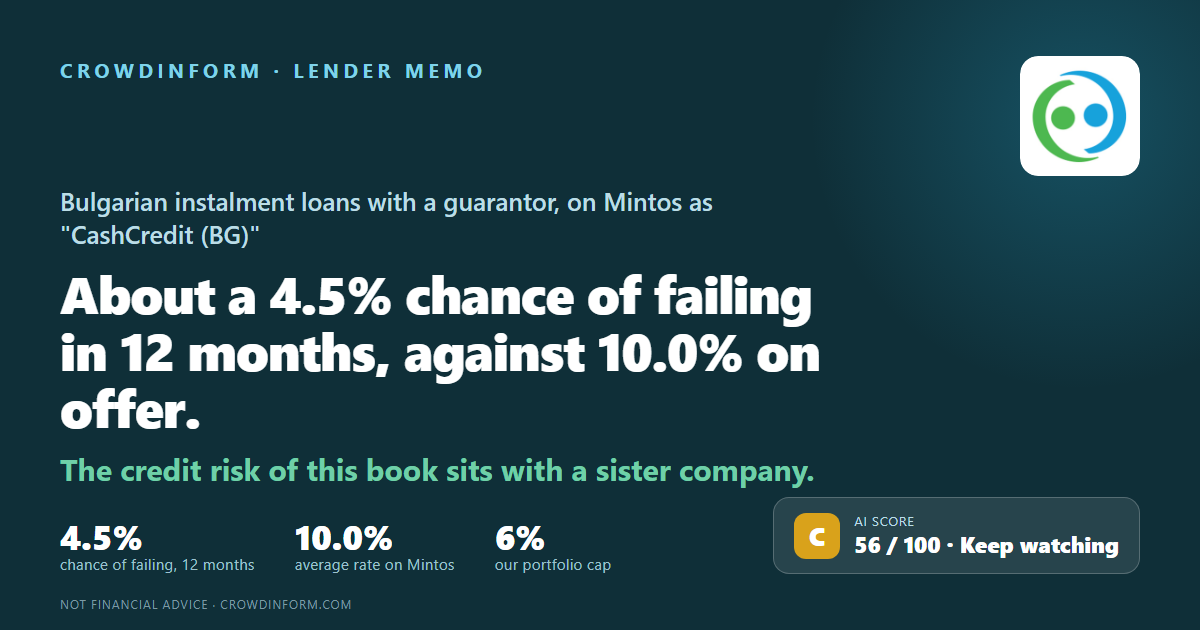
Bulgaria
Capital en riesgo. El tipo está pactado, no garantizado: si un prestatario incurre en impago, puede perder una parte o la totalidad de su dinero.
Nuestra IA da a este proyecto 56 de 100: Media. Cómo funciona la puntuación de la IA
Información, no asesoramiento personalizado de inversión. La puntuación IA valora los documentos que publica la plataforma, puede equivocarse y no predice la rentabilidad.
Cash Credit Mobile EAD is the Bulgarian lender Mintos investors know as CashCredit — small instalment loans of about €420 on average, up to €5,000, from 61 offices, most of them requiring a guarantor. This memo asks one question: what is the chance it fails to pay its lenders back in the next 12 months, and why.
The cushion is the good news, and it is real. Owners' money is €3.79m against €6.85m of assets — 55% at the end of 2024 and 53% by September 2025. Very few lenders in this series are funded that way. The qualification is size rather than proportion: 55% of a small balance sheet is still only €3.79m.
The direction is the worry. Of every €100 of revenue the company kept €23.79 in 2023, €12.92 in 2024 and €8.67 in the first nine months of 2025. Profit fell 53% between the two audited years, from BGN 1.09m to BGN 0.52m, and nine months of 2025 brought BGN 0.29m. Revenue fell too. Running the business now takes about €70 of every €100, against €54.68 in 2023.
Late loans tripled in five quarters — from 3.2% of the book more than ninety days late in June 2024 to 9.5% in September 2025. The reported cost of bad debts did not rise with them, and the reason is the next paragraph.
The credit risk of this book sits with a sister company. Cash Credit EAD guarantees most of the loans, and CashCredit books no loss on a loan it treats as fully guaranteed. At the end of 2024 that sister owed it BGN 21.0m of overdue guaranteed instalments, up from BGN 18.2m a year earlier — 283% of CashCredit's own equity on its own. It is set off against BGN 25.4m that CashCredit owes the sister. The same company also guarantees CashCredit's obligations to the Mintos issuer. It is unrated, it is small, and it is already carrying this book's losses.
And a draft law is aimed at exactly how this company lends. Most of its loans require a guarantor and some of its branches are franchises. The bill passed committee at first reading on 16 September 2026, and on 9 October the governing side set out the amendments it will table between the readings: a ban on the franchise model, fees abolished where they are used to get round the cost cap, and a borrower who was not properly assessed repaying only the principal, with no interest. None of it is law yet.
Six things would stop us scoring at all and send the answer straight to E — a default, a missed payment to a platform, a regulator pulling a licence, an auditor doubting the company can continue, a broken promise to a lender, or accounts we cannot rely on. None of them applies to this company — but section 4 explains how close one comes. Two things would pull the answer the other way, a guarantee from a stronger owner or a credit rating. Neither applies. There is a written guarantee, but it comes from an unrated sister company rather than a rated parent, so it earns no uplift under our method and there is no second number on this page.
Owners' money is 55% of assets. But profit has more than halved since 2023 and interest cover has fallen to 1.6 times, or 1.7 with depreciation added back.
Loans over ninety days late went from 3.2% to 9.5% in five quarters. The low reported losses rest on a sister's guarantee.
Grade C (3.30 out of 5). The euro since January 2026, a 52% cost cap, and a new consumer-credit law in parliament.
The whole book's credit risk sits with an unrated sister; there are errors in the audited notes; and the draft law targets guarantors and franchises.
Every investment carries risk, and risk is not really a letter or a mark out of ten. It is two plain questions: how likely is it that this company fails, and how much of your money would you lose if it did. Put those together and you can see whether the reward is worth it.
For CashCredit: Mintos showed an average investor rate of 10.0% a year on 5 November 2026. On our reading the chance of the company failing in the next twelve months is about 4.5%. If about 1 in 22 lenders like this one fail in a year and about 70% of the money is gone when they do, the risk costs about 3.2% a year, and about 6.8% is left once the risk is paid for. That is our arithmetic on our own scale, and you are entitled to disagree with the scale; what you should not do is read the 10.0% on its own. One thing the arithmetic cannot price is the draft law, because nobody knows what will be in it.
55% of assets is excellent. €3.79m is not much money. Both sentences are true and the second is the one that matters if something large goes wrong.
Loans more than ninety days late tripled while the bad-debt charge stayed near zero. That is the guarantee working as designed — and it moves the question from this company to its sister.
The amendments announced on 9 October would ban the franchise model and strip out fees used to get round the cap. CashCredit uses franchises and guarantors. Nothing has been voted.
On the Bulgarian National Bank's register under article 3 of the Credit Institutions Act. Bulgaria only, 61 offices — some of them run as franchises — with about 25% of its loans in Sofia.
About €420 on average, up to €5,000, at an annual cost of up to 50%. Most require a guarantor, which is the feature the draft law would restrict.
BGN 14.2m at September 2025. Revenue was BGN 4.02m — about €2.05m — in 2024, down from BGN 4.60m.
Through Cash Credit Bulgaria EOOD, and controlled by Georgi Boyanov Krumov and Plamen Vasilev Petrov. The owner changed in December 2022 from a Cayman Islands company.
The notes are in euros and are issued by SIA Mintos Finance No. 5. You do not lend to CashCredit directly.
Outstanding on 5 November 2026 on the platform's own figure.
A 60-day buyback, a pledge, and Cash Credit EAD guaranteeing CashCredit's obligations to the Mintos issuer — expressly not the issuer's obligations towards investors.
As we read it on 5 November 2026. Mintos last updated it on 9 October 2026, up from 6.4, when the portfolio-performance part rose; it had cut the buyback-strength part on 9 July 2026. That is Mintos's number, not ours.
El análisis completo cubre al prestatario o la empresa, la garantía, el flujo de caja, los riesgos y un veredicto. Inicie sesión para leerlo.
Información, no asesoramiento personalizado de inversión. La puntuación IA valora los documentos que publica la plataforma, puede equivocarse y no predice la rentabilidad.
Inicie sesión para preguntar a la IA sobre los documentos de este proyecto.
Iniciar sesión👍 Sí · 0 👎 No · 0
Enlace de afiliado · capital en riesgo
Ver 11 proyectos →Mintos
Mintos
Mintos