
Réglementé
Bonus en cours
Revente anticipée
- Niveau de risque
- Élevé
- Risque-rendement
- Moyen
- Dès
- €50
Lien affilié · capital à risque
Voir 11 projets →Des questions sur l'investissement ? Demandez au guide IA.
Bonjour ! Je suis le guide IA de Crowdinform.
Connectez-vous gratuitement pour interroger le guide IA sur les plateformes, les projets et vos plans.
Les réponses proviennent des données vérifiées de Crowdinform. Information, et non conseil en investissement personnalisé.
Recherche en cours… Une erreur s'est produite. Veuillez réessayer. {n} questions restantes aujourd'hui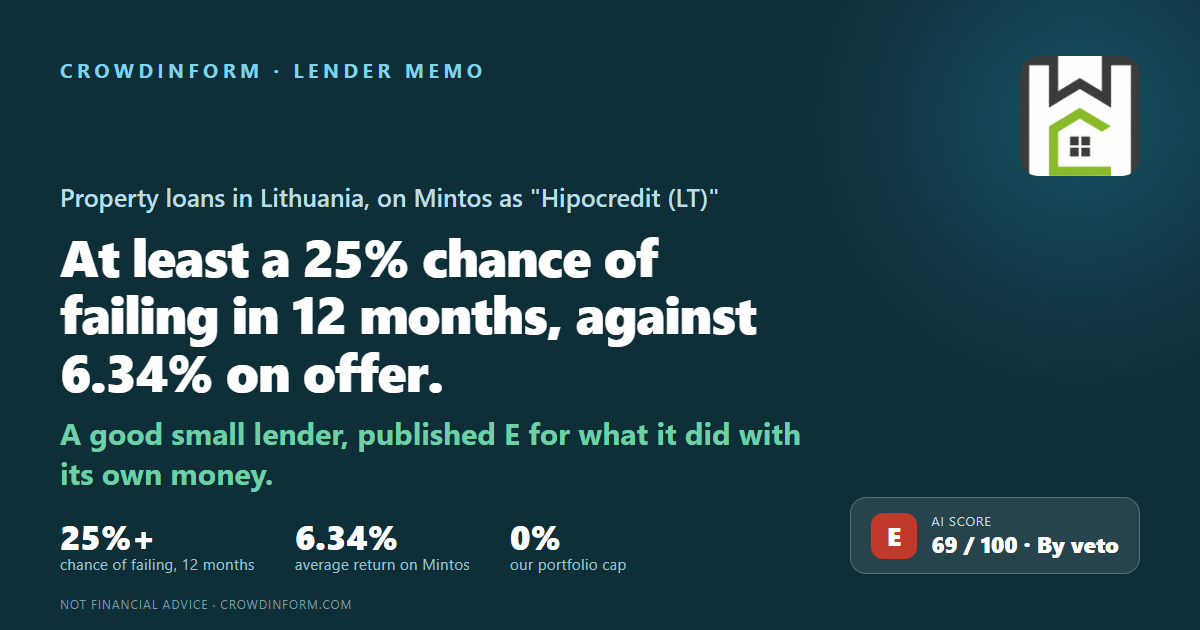
Lituanie
Capital à risque. Le taux est convenu, et non garanti : si un emprunteur fait défaut, vous pouvez perdre une partie ou la totalité de votre argent.
Notre IA attribue à ce projet 69 sur 100 : Moyen. Comment fonctionne le score IA
Information, et non conseil en investissement personnalisé. Le score IA évalue les documents publiés par la plateforme, peut se tromper et ne prédit pas les rendements.
UAB Hipotekiniai kreditai is a small Lithuanian lender in Kaunas — 3 staff — that lends against property, mostly to companies, at 12% to 18% a year. Mintos investors lend to it under the name "Hipocredit (LT)", which is worth knowing because a different company called Hipocredit has its own memo. This memo asks one question: what is the chance it fails to pay its lenders back in the next 12 months, and why.
The marks come to 69, which would be a B — about 1 in 45. They are not what decides this memo. One of our automatic vetoes applies, from the company's own audited accounts: every year it has lent more to companies in its own family than it owns itself, where our line is half. That alone sets the answer to at least 1 in 4.
The figures. Against owners' money of €1.86m at the end of 2023 it had lent €8.12m — 437% of it. A year later €10.27m against €3.16m, or 325%. By the end of 2025 the figure was €3.70m against €4.28m — 86%, still above the half-the-cushion line and still the whole of what remains.
And the direction of travel is the interesting part. The larger of the two loans — €6.57m to a related Latvian company, made "through the Company's shareholder" and secured on 592 vehicles — simply stops appearing in the 2025 accounts. It was due on 16 September 2026, a date that has now passed. Lending to Lithuanian companies rose by almost exactly the same amount in the same year. That may be a repayment. It may be a reclassification. The accounts do not say, and we found no statement either way.
What is left is a loan to a company it no longer owns. The €3.70m was lent to AS Hipocredit, its Latvian subsidiary — but on 16 July 2026 that company was sold out of the group. Whether the loan went with it, was repaid, or simply stayed is not disclosed. An unsecured loan to a subsidiary is one thing; the same loan to a company you no longer control is another.
Everything else about it is sound, and the memo should say so plainly. It kept €32.81 of every €100 of income in 2025 and about a third in each of the three years. Every loan it makes carries a mortgage, at an average of 43% of the property's value. Interest was covered 1.77 times. Owners' money has grown every year because no dividend has ever been paid. The veto is not a judgement about whether it can lend; it is about where its own capital has gone.
Six things would stop us scoring at all and send the answer straight to E — a default, a missed payment to a platform, a regulator pulling a licence, an auditor doubting the company can continue, a broken promise to a lender, or accounts we cannot rely on. One of them does apply, on the company’s own audited accounts, and it is what this memo is published on. Two things would pull the answer the other way, a guarantee from a stronger owner or a credit rating. Neither applies. This is the top company of its own group — there is nobody above it to give a guarantee — so there is no second number on this page.
Profit €1,117,300 in 2025, €32.81 of every €100 left over, interest covered 1.77 times.
Every loan secured on property at 43% of its value on average — but 91% is lent to companies and no arrears figures are published at all.
Grade A (4.25 out of 5). The euro, courts in the world's top ten, a sovereign rated A. The best country we cover.
The related-party lending above, €13.92m from lenders the accounts never name, and sponsorship rising eightfold in two years.
Every investment carries risk, and risk is not really a letter or a mark out of ten. It is two plain questions: how likely is it that this company fails, and how much of your money would you lose if it did. Put those together and you can see whether the reward is worth it.
Here are both halves of the sum, side by side. Mintos showed an average net annual return of 6.34% on these loans when we read it on 5 November 2026. Our half is this: if a company on at least 25% odds fails and about 70% of the money is gone when it does, the risk costs about 17.5% a year. Whatever rate you are offered, that is what has to be covered before anything is left. Check the rate yourself before you rely on it: it is Mintos's average, not a promise.
This company lends carefully against property and makes money doing it. The override is about what it did with its own capital, which is a different question — and the one that decides whether it can pay you.
The car-backed loan stopped being mentioned. That is all we know. Treat a figure that disappears as unexplained until something explains it.
Mintos lists this one as "Hipocredit (LT)". AS Hipocredit in Latvia is a different company, sold out of this group in July 2026, with its own memo. Do not read one as the other.
On the Bank of Lithuania's public list of real-estate credit lenders since 2017. Kaunas, 3 staff, lending across Lithuania. Its registered share capital is €5,000 — everything else in the cushion is profit it never paid out.
At 12% to 18% a year, every one secured by a mortgage. Limits run from 75% of value for a flat in central Vilnius down to 40% outside the 35 largest towns.
At the end of 2025, flat on the year, with €13.7m newly lent during it. Income was €3,405,620 and profit €1,117,300.
Led by Gediminas Velička with 49.9%, on the company's own 2025 presentation. It is the top company of its own group, so there is nobody above it to guarantee anything.
The name is the Latvian company's; the borrower is this one. Mintos raised the buyback part of its score twice during 2025.
Outstanding when we read it on 5 November 2026, on the platform's own figure. The audited accounts show €3.23m owed to Mintos investors at the end of 2025 — a small part of its €27.16m of funding.
Each Mintos loan is repaid when the matching borrower repays, backed by a buyback promise. Mintos showed an average net annual return of 6.34% on 5 November 2026; the box above sets it against our estimate of what the risk costs.
Read on 5 November 2026: portfolio performance 10.0, servicer efficiency 8.3, buyback strength 7.2, cooperation structure 5.5. The loan-servicer subscore was raised in that quarterly round, after an improvement in a country rating Mintos uses.
L'analyse complète couvre l'emprunteur ou l'entreprise, la garantie, les flux de trésorerie, les risques et un verdict. Connectez-vous pour la lire.
Information, et non conseil en investissement personnalisé. Le score IA évalue les documents publiés par la plateforme, peut se tromper et ne prédit pas les rendements.
Connectez-vous pour interroger l'IA sur les documents de ce projet.
Connexion👍 Oui · 0 👎 Non · 0
Lien affilié · capital à risque
Voir 11 projets →Mintos
Mintos
Mintos