
Regolamentata
Bonus attivo
Vendita anticipata
- Livello di rischio
- Alto
- Rischio-rendimento
- Medio
- Inizia da
- €50
Link di affiliazione · capitale a rischio
Vedi 42 progetti →Domande sugli investimenti? Chiedi alla guida IA.
Ciao! Sono la guida IA di Crowdinform.
Accedi gratis per fare domande alla guida IA su piattaforme, progetti e i tuoi piani.
Le risposte provengono dai dati verificati di Crowdinform. Informazione, non consulenza personalizzata sugli investimenti.
Sto cercando… Qualcosa è andato storto. Riprova. {n} domande rimaste oggi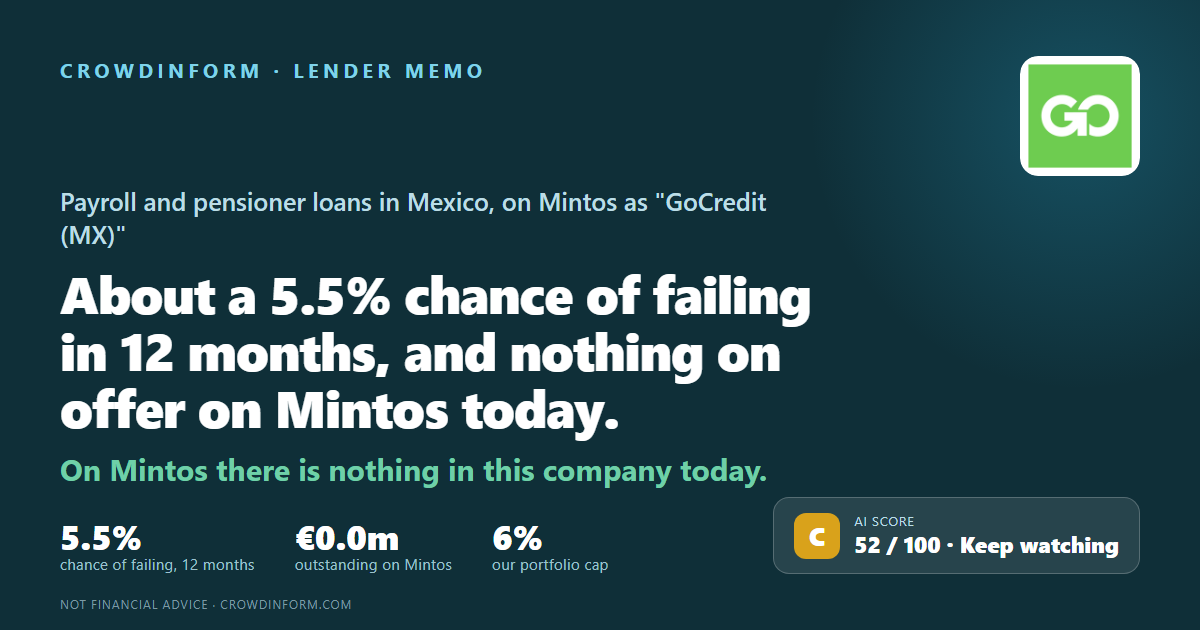
Messico
Capitale a rischio. Il tasso è concordato, non garantito: se un debitore è inadempiente puoi perdere una parte o la totalità del tuo denaro.
La nostra IA assegna a questo progetto 52 su 100: Medio. Come funziona il punteggio IA
Informazioni, non consulenza personalizzata in materia di investimenti. Il punteggio IA valuta i documenti pubblicati dalla piattaforma, può essere sbagliato e non prevede i rendimenti.
Start with the unusual part: on Mintos there is nothing in this company today. On 9 November 2026 Mintos showed no GoCredit Notes outstanding and a 0% average rate, and on 13 September 2026 it listed no loans at all in its performance table. Monto Fácil repaid its Mintos funding during 2025 and 2026 with no delay we could find. But it keeps a live Mintos prospectus and a Risk Score, so Notes could reappear. This memo therefore rates the lender, not money now at risk. The question is the usual one: what is the chance that Monto Fácil, S.A.P.I. de C.V., SOFOM, E.N.R. fails to pay its lenders in the next 12 months?
The lending itself is the steadiest part of this memo. Monto Fácil lends to government workers and to pensioners, and is repaid by deduction from the payroll or the pension before the borrower sees the money. Loans more than ninety days late have stayed near five per cent for three years — 4.61%, 5.22%, 4.79% — while the book grew. The allowance is about 1.2 times those late loans.
The complication is how it is funded, and it changes the profit. MXN 399.6m of its money comes from a Banregio trust, and the returns that trust pays its investors — MXN 76.93m in 2025 — are charged to equity rather than to profit, because under the accounting rules the trust money counts as equity. The company reported MXN 95.29m of profit — about €4.8m. Count the trust returns as the cash cost they are, and what is left is MXN 18.36m — 3.92 of every 100 of income, against 0.89 in 2024 and a loss of −4.85 in 2023.
And the paper trail is thin. The last audit report we have is RSM's clean opinion on 2023. The 2024 and 2025 figures are management statements with no audit report attached, and the 2024 figures changed between the two versions we hold: total assets MXN 886.7m became MXN 880.3m, and administrative costs MXN 69.6m became MXN 85.1m. That is what holds the trust-in-the-numbers mark down to a D.
So: about 1 in 18, a C, and nothing of yours in it today. If GoCredit Notes reappear on Mintos, this is the starting point — and Mintos's own score for this company, 8.0, is the highest of the Mexican originators we cover.
Six things would stop us scoring at all and send the answer straight to E — a default, a missed payment to a platform, a regulator pulling a licence, an auditor doubting the company can continue, a broken promise to a lender, or accounts we cannot rely on. None of them applies to this company. Two things would pull the answer the other way, a guarantee from a stronger owner or a credit rating. Neither applies: we found no guarantee from its parent, Go.MGMT, and no credit rating.
Reported profit MXN 95.29m — but after MXN 76.93m paid to the trust investors, 3.92 of every 100 is left.
Payroll and pension loans; 4.79% more than ninety days late, and the allowance covers those about 1.2 times.
No rate cap; a June 2026 usury ruling; and a total annual cost of 144.1% on one of its own products.
No audit report since 2023, and the 2024 figures changed between two versions of the same year.
Every investment carries risk, and risk is not really a letter or a mark out of ten. It is two plain questions: how likely is it that this company fails, and how much of your money would you lose if it did. Put those together and you can see whether the reward is worth it.
For Monto Fácil, the first half of the sum is zero today. Nothing is on offer: Mintos showed a 0% average rate and no Notes outstanding. So there is no reward to weigh and no risk being taken. Here is the half you will need if that changes. On our reading the chance of this company failing in the next twelve months is about 5.5%. If about 1 in 18 lenders like this one fail in a year and about 70% of the money is gone when they do, the risk costs about 3.8% a year. Subtract that from whatever rate is offered before deciding the reward is worth it. That is our arithmetic on our own scale, and you are entitled to disagree with the scale.
A lender that ran its platform funding down to nothing without a single missed payment has told you something no ratio can. It is the strongest fact in this memo and it is why the warning-signs mark is not lower.
MXN 95.29m reported, MXN 18.36m left once the trust investors are paid. Both numbers are correct; only one of them is the margin a lender should look at.
Ordinary shareholders have put in MXN 42.8m, which is 4.3% of what the company owns. But the trust's MXN 399.6m ranks behind every lender, so from a lender's seat the cushion is MXN 442.4m — 44.2%.
An unregulated Mexican finance company, founded in April 2011 in Monterrey. A subsidiary of Go.MGMT, S.A. de C.V. Trades as "GO Credit", with more than 100 staff.
To government workers and to IMSS, ISSSTE and PEMEX pensioners, repaid by deduction. The total annual cost runs from 78.3% to 144.1%.
Gross, at the end of 2025 — about €38.4m — up 11% over the year.
A Banregio trust whose money counts as equity, and an Invex trust that is debt. The parent manages the first and takes a fee on it.
Euro and dollar Notes, on Mintos since August 2021. A base prospectus for SIA Mintos Finance No. 13 dated 23 February 2026 is live.
Nothing outstanding when we read Mintos on 9 November 2026; no loans listed on 13 September 2026, and nothing in our own register of 20 September — platform figures.
When Notes were live there was a 60-day buyback, a pledge and repayment through a Banorte trust, as the February 2026 prospectus sets out.
Raised 4 times between March 2024 and October 2025, and still 8.0 after Mintos's update of 9 October 2026 — the highest of the Mexican originators we cover. That is Mintos's number, not ours.
L'analisi completa copre il debitore o l'azienda, la garanzia, i flussi di cassa, i rischi e un verdetto. Accedi per leggerla.
Informazioni, non consulenza personalizzata in materia di investimenti. Il punteggio IA valuta i documenti pubblicati dalla piattaforma, può essere sbagliato e non prevede i rendimenti.
Accedi per fare domande all'IA sui documenti di questo progetto.
Accedi👍 Sì · 0 👎 No · 0
Link di affiliazione · capitale a rischio
Vedi 42 progetti →Mintos
Mintos