Why audit investment portfolios: a practical 2026 guide
Discover why audit investment portfolios is crucial for serious investors. Uncover hidden inefficiencies and align your goals for better returns.
- Investing
Questions about investing? Ask the AI guide.
Hi! I'm the Crowdinform AI guide.
Sign in free to ask the AI guide about platforms, projects and your plans.
Answers come from Crowdinform's checked data. Information, not personal investment advice.
Looking it up… Something went wrong. Please try again. {n} questions left todayArticle
Discover what smart investing is and how it can grow your wealth. This 2026 guide reveals strategies for long-term financial success!
Smart investing is the practice of building long-term wealth through disciplined, strategy-driven decisions that prioritise diversification, cost control, and risk management over short-term speculation. Unlike reactive trading or performance chasing, it is defined by process, not luck. Research from a 2022 Vanguard study shows that investors following a balanced 60/40 global index strategy earned 1.9 percentage points more annually than average active fund buyers after fees. That gap compounds dramatically over decades. Whether you are just starting out or refining your approach, the principles of smart investing apply equally, and they are more accessible than most people assume.
Smart investing is a structured, goal-oriented approach to growing wealth that relies on evidence-based principles rather than market predictions. It combines diversification across asset classes, consistent contributions, low-cost vehicles such as index funds and ETFs, and the behavioural discipline to stay the course through volatility. The Vanguard research above is not an anomaly. It reflects a consistent pattern: simple, disciplined strategies outperform complex, fee-heavy ones over time.
The benefits of smart investing extend beyond returns. A well-constructed portfolio reduces the emotional burden of market swings, protects capital during downturns, and builds compounding momentum that accelerates over time. Consider this: investing $500 monthly at 8% annual returns produces £186,000 in 15 years, but £745,000 in 30 years. The difference is not a larger contribution. It is time and discipline.
Smart investing is also not the exclusive domain of professionals. Platforms like Crowdinform, tools like Morningstar's fund screener, and frameworks like the Investment Policy Statement (IPS) put institutional-grade thinking within reach of individual investors at every level.
The principles of smart investing form a repeatable framework that removes guesswork from wealth building. They are not complicated, but they require consistency to work.
Pro Tip: Set up automatic monthly contributions to a low-cost global index fund before you do anything else. Automation removes the single biggest obstacle to smart investing: yourself.
Diversification is the only free lunch in investing, and it is the cornerstone of every smart investment strategy. By spreading capital across uncorrelated assets, you reduce the impact of any single loss on your overall portfolio. Maintaining a diversified portfolio of mutual funds for five to seven years typically offers the lowest risk of capital loss. That is not a coincidence. It reflects how time and breadth work together to smooth volatility.
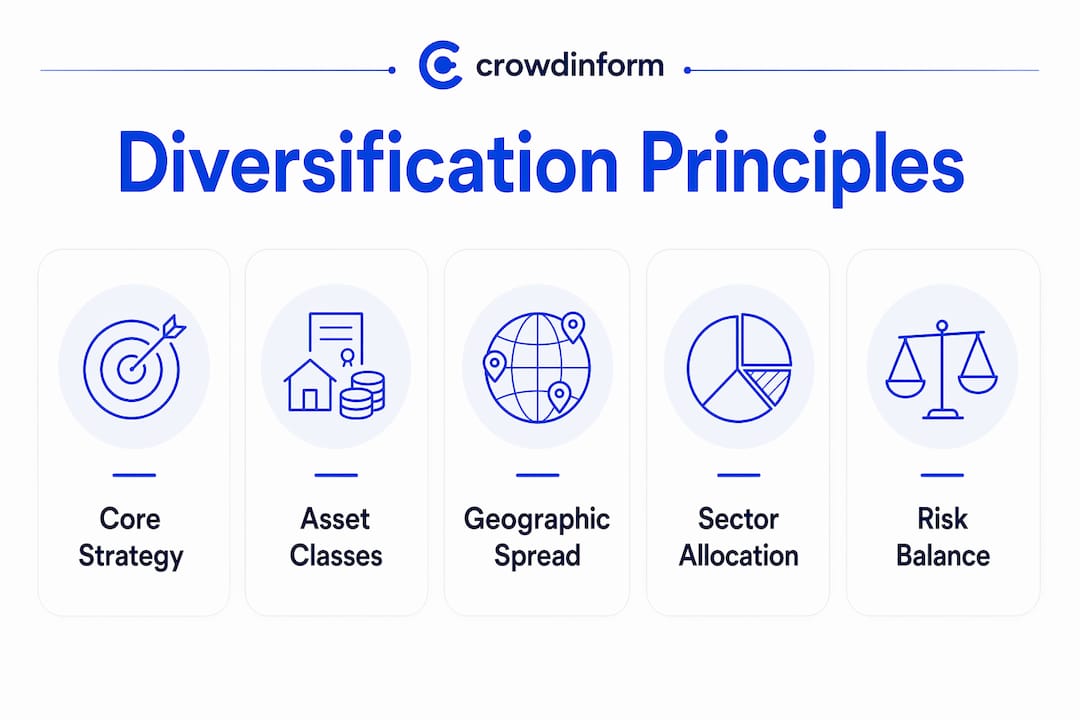
Geographic and sector diversification add another layer of protection. A portfolio concentrated in UK technology stocks is exposed to both sector-specific downturns and domestic economic shocks simultaneously. Adding international equities, emerging market exposure, and real assets such as property or infrastructure reduces that dual vulnerability. You can explore how real asset inclusion strengthens portfolio resilience in more detail.
The table below illustrates the difference in risk and return profile between a diversified and a non-diversified portfolio over a 10-year horizon:
| Portfolio type | Asset classes held | Estimated max drawdown | Annualised return (approx.) |
|---|---|---|---|
| Non-diversified | Single equity sector | 40–60% | Variable, high volatility |
| Partially diversified | Equities + bonds | 20–35% | Moderate, lower volatility |
| Fully diversified | Equities, bonds, real assets, alternatives | 10–20% | Consistent, compounding growth |
Ray Dalio's All Weather Portfolio takes this further by balancing risk across four economic environments: rising growth, falling growth, rising inflation, and falling inflation. The result is a portfolio that performs across cycles rather than excelling in one and collapsing in another. For individual investors, the practical takeaway is clear: diversifying across asset classes is not optional. It is the structural foundation of how to invest wisely.
Risk in smart investing is not simply the chance of a bad day in markets. It is the probability of failing to meet your financial goals within your required timeframe. That reframing matters because it shifts the focus from short-term price movements to long-term outcome planning.
Effective risk management combines several practical tools:
Behavioural discipline is where most investors lose ground. Changing investments based on headlines or chasing recent performance consistently reduces returns. Fidelity's research confirms that staying invested and disciplined yields better results than any tactical adjustment based on market sentiment.
Investment educator Filippo Ucchino frames this precisely: smart investing is process-based, not outcome-based. Following a disciplined process matters even when individual results vary in the short term. That mindset shift, from judging each trade to evaluating your overall system, is what separates successful long-term investors from the rest.
Pro Tip: When markets fall sharply, open your IPS before you open your brokerage account. Reading your own pre-decided rules is the most effective circuit breaker against panic selling.
Fees are the most underestimated threat to long-term wealth accumulation. According to Morningstar's "Mind the Gap" report, overpaying fees by 1% annually can subtract 25% from your final nest egg over 35 years. That is not a marginal difference. It is the equivalent of working an extra decade to compensate for avoidable costs.
The table below summarises the key cost and tax considerations for smart investors:
| Cost or tax factor | Typical range | Smart investing approach |
|---|---|---|
| Active fund management fee | 1.0–2.5% annually | Switch to index funds or ETFs (0.05–0.25%) |
| ETF / index fund fee | 0.05–0.25% annually | Prioritise lowest-cost options available |
| Capital gains tax | Varies by jurisdiction | Use tax-advantaged accounts (ISA, SIPP in the UK) |
| Tax-loss harvesting benefit | 0.5–1.5% annually (tax alpha) | Offset gains with strategic realisation of losses |
| Platform / dealing fees | £0–£12 per trade | Choose flat-fee platforms for larger portfolios |
Tax-efficient investing amplifies the fee advantage. In the UK, Stocks and Shares ISAs and SIPPs shelter returns from capital gains and income tax entirely. Asset location, placing tax-inefficient assets such as bonds inside tax-advantaged accounts and equities in general investment accounts, adds further efficiency without changing your underlying strategy.
The practical rule is straightforward: every pound saved in fees and taxes is a pound that compounds. Low-cost index funds from providers such as Vanguard, iShares, and HSBC Global Asset Management are the preferred vehicles for most individual investors pursuing smart investment strategies.
Starting is simpler than most people expect. The DFPI financial health hierarchy provides a clear sequence: build an emergency fund first, clear high-interest debt second, then begin investing. Skipping these steps means you risk selling investments at a loss to cover unexpected costs.
For evaluating specific platforms and crowdfunding opportunities, Crowdinform's guide on analysing investment platforms provides a structured framework for comparing options by risk, return, and fee profile. If you are also considering how to deploy spare capital efficiently, this guide on investing spare cash wisely in 2026 offers practical context for prioritising contributions.
Smart investing succeeds because it replaces emotional, reactive decisions with a disciplined, process-driven system built on diversification, low costs, and long-term commitment.
| Point | Details |
|---|---|
| Define your process first | Write an Investment Policy Statement before making any investment decisions. |
| Diversification reduces real risk | Holding diversified funds for five to seven years typically offers the lowest capital loss risk. |
| Fees compound against you | A 1% annual fee excess can reduce your final portfolio by 25% over 35 years. |
| Time amplifies returns dramatically | £500 monthly at 8% grows to £186,000 in 15 years but £745,000 in 30 years. |
| Behaviour matters as much as strategy | Staying invested through volatility consistently outperforms tactical market timing. |
I have spent years reviewing investment platforms and strategies across Europe, and the pattern I see most consistently is this: the investors who struggle are rarely those who lack knowledge. They are the ones who confuse complexity with sophistication.
The most effective smart investing approach I have encountered is almost boring in its simplicity. A low-cost global index fund, automated monthly contributions, an annual rebalance, and a written policy statement that prevents panic decisions. That is it. The investors I have seen build genuine long-term wealth are not the ones trading the most actively or holding the most exotic instruments. They are the ones who set up a sensible system and then largely left it alone.
The fear beginners feel is real, and I do not dismiss it. Markets fall. Headlines are alarming. The temptation to act is constant. But the data is unambiguous: staying invested and disciplined yields better outcomes than almost any tactical response to short-term noise. The mindset shift from "what should I do right now?" to "am I following my process?" is the single most valuable thing any investor can develop.
Smart investing for beginners does not require a finance degree or a large starting capital. It requires a clear goal, a written plan, and the patience to let compounding do its work. That is accessible to everyone.
— Jevgenijs
Crowdinform aggregates and reviews over 500 European crowdfunding platforms, giving you the data and AI-powered tools to make informed, diversified investment decisions aligned with smart investing principles.

Whether you are interested in P2P loans, real estate crowdfunding, or startup equity, Crowdinform's AI copilot helps you evaluate projects, compare platforms, and build a portfolio that reflects your goals and risk tolerance. The platform brings institutional-level analysis to individual investors, making it easier than ever to apply the principles covered in this guide. Start exploring crowdfunding investment opportunities on Crowdinform today and take your first step towards a genuinely diversified, process-driven portfolio.
Smart investing is the practice of growing wealth through disciplined, evidence-based strategies that prioritise diversification, low costs, and long-term commitment over speculation or market timing.
The DFPI recommends investing 10–15% of your annual income once you have an emergency fund covering three to six months of living expenses and have cleared high-interest debt.
A strategy is smart when it is process-based rather than outcome-based, meaning it follows pre-defined rules for asset allocation, rebalancing, and risk management regardless of short-term market conditions.
Index funds and ETFs are the preferred vehicles for most individual investors because they offer broad diversification at minimal cost. Morningstar data shows that a 1% fee excess can reduce a final portfolio by 25% over 35 years.
Diversification spreads risk across uncorrelated assets so that no single loss significantly damages your overall portfolio. Research shows that holding a diversified portfolio for five to seven years typically offers the lowest risk of capital loss.
Capital at risk. Crowdfunding investments are not covered by deposit guarantee schemes, can lose part or all of their value, and may be hard to sell before the end of their term. This guide is information, not personal investment advice.
Was this helpful?

Eugene Sokolovs Expert
Founder of Crowdinform
Keep reading
Discover why audit investment portfolios is crucial for serious investors. Uncover hidden inefficiencies and align your goals for better returns.
Here’s your investor-focused round-up of what’s newly raising, which platforms updated, and project milestones across Europe’s top crowdfunding platforms. Skim the first section on fresh listings if you’re hunting for deals, then dive into platform updates and portfolio wins. 🚀
 Video
Want to invest in the next Google, Facebook, or Amazon—before they explode? Early-stage investments can bring massive returns, and you’re in the right place to catch them! In this video, we’ve gathered the top startup deals currently raising funds on licensed equity crowdfunding platforms. These startups are solving real problems—and they’re offering you a chance to become a shareholder and grow with them. Let’s explore the best opportunities out there and maybe even spot the next big thing before the rest of the world does!

Comments · 0