
Reguliert
Bonus läuft
Vorzeitig verkaufbar
- Risikostufe
- Hoch
- Risiko-Rendite
- Mittel
- Start ab
- €50
Empfehlungslink · Kapitalverlustrisiko
42 Projekte ansehen →Fragen zum Investieren? Fragen Sie den KI-Guide.
Hallo! Ich bin der KI-Guide von Crowdinform.
Melden Sie sich kostenlos an, um den KI-Guide zu Plattformen, Projekten und Ihren Plänen zu fragen.
Die Antworten stammen aus den geprüften Daten von Crowdinform. Information, keine persönliche Anlageberatung.
Wird nachgeschlagen… Etwas ist schiefgelaufen. Bitte versuchen Sie es erneut. Heute noch {n} Fragen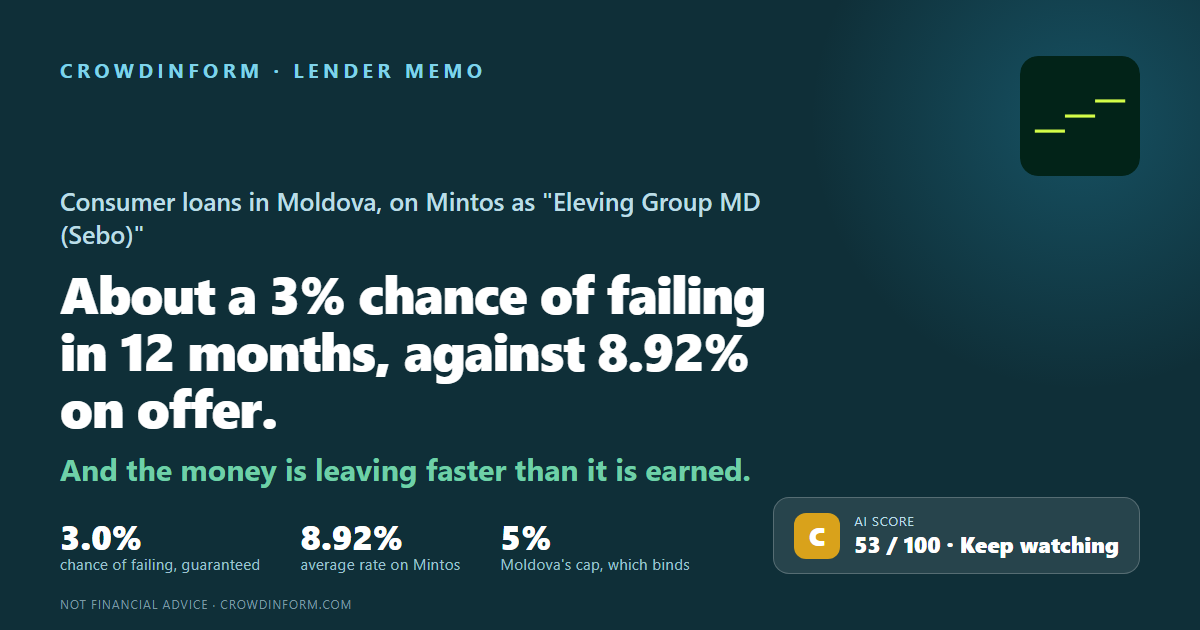
Moldau
Kapitalverlustrisiko. Der Zins ist vereinbart, nicht garantiert: Fällt ein Kreditnehmer aus, können Sie Ihr Geld teilweise oder vollständig verlieren.
Unsere KI gibt diesem Projekt 53 von 100 Punkten: Mittel. So funktioniert der KI-Score
Informationen, keine persönliche Anlageberatung. Der KI-Score bewertet die von der Plattform veröffentlichten Dokumente, kann falsch sein und sagt keine Renditen voraus.
O.C.N. Sebo Credit S.R.L. is Eleving Group's consumer lender in Moldova — instalment loans from MDL 1,000 to 400,000 over up to sixty months, from 30 branches, to about 272,000 customers — and since December 2025 it also holds a book of car loans bought from a sister company. Mintos investors lend to it through a Mintos company. This memo asks one question: what is the chance it fails to pay its lenders back in the next 12 months, and why. It replaces our memo of 13 September 2026, which read a low Mintos subscore as meaning there was no parent guarantee. The prospectus shows there is one.
The direction is the finding. Of every €100 of income Sebo kept €36.37 in 2023, €31.67 in 2024, €18.69 in 2025 — and in the first quarter of 2026 it lost €2.26. Income barely moved over those years; what changed is the cost of bad borrowers, which rose from €16.08 of every €100 to €28.12, and then €36.30 in the first quarter.
And the money is leaving faster than it is earned. Dividends declared were 40% of profit in 2023, 81% in 2024 and 147% in 2025 — MDL 74.0m, about €3.8m, against MDL 50.3m of profit. On 16 March 2026 another MDL 21.0m was declared, in a quarter the company was making a loss. Owners' money fell MDL 23.7m during 2025 as a result. Our method treats payouts above profit two years running as a veto — one more such year, and this memo's answer becomes at least 1 in 4 on the 2026 accounts.
The cushion is still real, and it is thinning. Owners' money was €11.9m at the end of 2025 — 31% of what the company owns, down from 64% a year earlier because the loan book roughly doubled on borrowed money, and 28% by March 2026. Nothing of it is lent to group companies: receivables from them are MDL 27.9m, about 12% of the cushion, far below the half our connected-lending test uses.
The guarantee is what gives the second number. The Mintos base prospectus of 2 July 2026 says Eleving Group S.A. guarantees Sebo's obligations to the Mintos companies — and, in the same passage, that it "is not guaranteeing Mintos, the SPV or the Issuer's obligations towards the Investors". Eleving is rated B by Fitch, outlook positive, so under our method its rating sets the odds: about 1 in 33. In the other direction Sebo guarantees up to €300m of Eleving's 2030 bonds, with its assets and 98.4% of its shares pledged.
And the country is the hardest of the four questions. Moldova is a D on our scale. Interest has been capped at 50% a year since 2022, a draft law would halve it to 25%, and Sebo earned about 57% on its own average book in 2025. If that draft passed as written, income could fall by about two-fifths — a loss of roughly €2.8m a year before tax.
Six things would stop us scoring at all and send the answer straight to E — a default, a missed payment to a platform, a regulator pulling a licence, an auditor doubting the company can continue, a broken promise to a lender, or accounts we cannot rely on. None of them applies yet — but one is a single year away, and the first flag on this page says which. Two things would pull the answer the other way, a guarantee from a stronger owner or a credit rating. One of them does apply, and it is the only reason this memo gives a second number.
Profit down well over half in two years, and the first quarter of 2026 was a loss. Owners' money is still 31% of assets.
About 11% of its own loans defaulted and steady; bad debts took €28.12 of every €100 in 2025 and €36.30 in early 2026.
Grade D (2.27 out of 5). A 50% interest cap, a draft law to halve it, and a war next door.
Paid out 147% of 2025 profit; one group loan funds it; and it guarantees Eleving's bonds.
Every investment carries risk, and risk is not really a letter or a mark out of ten. It is two plain questions: how likely is it that this company fails, and how much of your money would you lose if it did. Put those together and you can see whether the reward is worth it.
For Sebo: Mintos showed an average investor rate of 8.92% a year on 9 November 2026 (9.1% on 13 September). On our reading the chance of the company behind it failing in the next twelve months is about 3.0% — the parent's number, because of the guarantee. If about 1 in 33 lenders like this one fail in a year and about 70% of the money is gone when they do, the risk costs about 2.1% a year, and about 6.8% is left once the risk is paid for. On Sebo's own number instead of the parent's, the risk cost would be about 3.6% and about 5.3% would be left. That is our arithmetic on our own scale, and you are entitled to disagree with the scale; what you should not do is read the 8.92% on its own.
Sebo made money in all three audited years. What the chart shows is the rate at which that is getting harder — and a company paying out more than it earns while that happens is spending its cushion to stand still.
Payouts above profit twice running is an automatic override in our method. 2025 was the first year. The 2026 accounts decide whether this memo's answer stays where it is.
A C would allow 6%, the guarantee would allow 12% — but Moldova as a whole allows 5%. For a reader, the country is the constraint here, not the lender.
On the regulator's register since 2019 and supervised by the National Bank of Moldova. Moldova only, with 30 branches at the end of 2025 — 32 in the July 2026 prospectus.
MDL 1,000 to 400,000 over up to sixty months, to about 272,000 customers — and, since December 2025, a book of car loans bought from a sister company.
Net, at the end of 2025, after the €14.8m purchase that nearly doubled it. Income of MDL 269m — about €13.7m — in 2025.
Through AS Eleving Consumer Finance. Eleving Group S.A. is rated B by Fitch with a positive outlook.
The notes are issued by SIA Mintos Finance No. 6. You do not lend to Sebo directly.
Outstanding on 9 November 2026 on the platform's own figure (€3,839,416), read that day. On 13 September 2026 our capture showed €7.6m (another sheet of it €7.4m). Eleving's reports show €5.4m of Mintos loans in Moldova at 30 June 2026 and €6.8m at 30 September 2026.
The average investor rate shown on 9 November 2026 (9.1% on 13 September). Sebo's receivables are pledged to the Mintos lender, and Eleving Group guarantees Sebo's obligations to the Mintos companies.
Updated by Mintos on 9 October 2026 and read on 9 November 2026; it was 7.8 on 13 September. Its parts: loans performing 7.4, collections 7.9, buyback 9.3, structure 4.5. That is Mintos's number, not ours, and we have not checked how it is built.
Die vollständige Analyse behandelt den Kreditnehmer bzw. das Unternehmen, die Sicherheit, den Cashflow, die Risiken und ein Fazit. Melden Sie sich an, um sie zu lesen.
Informationen, keine persönliche Anlageberatung. Der KI-Score bewertet die von der Plattform veröffentlichten Dokumente, kann falsch sein und sagt keine Renditen voraus.
Melden Sie sich an, um der KI Fragen zu den Dokumenten dieses Projekts zu stellen.
Anmelden👍 Ja · 0 👎 Nein · 0
Empfehlungslink · Kapitalverlustrisiko
42 Projekte ansehen →Mintos
Mintos
Mintos