
Regulada
Bono activo
Venta anticipada
- Nivel de riesgo
- Alto
- Riesgo-rentabilidad
- Media
- Desde
- €50
Enlace de afiliado · capital en riesgo
Ver 42 proyectos →¿Preguntas sobre inversión? Pregunte a la guía IA.
¡Hola! Soy la guía de IA de Crowdinform.
Inicia sesión gratis para preguntar a la guía IA sobre plataformas, proyectos y tus planes.
Las respuestas proceden de los datos verificados de Crowdinform. Información, no asesoramiento de inversión personalizado.
Buscando… Algo ha fallado. Inténtelo de nuevo. {n} preguntas restantes hoy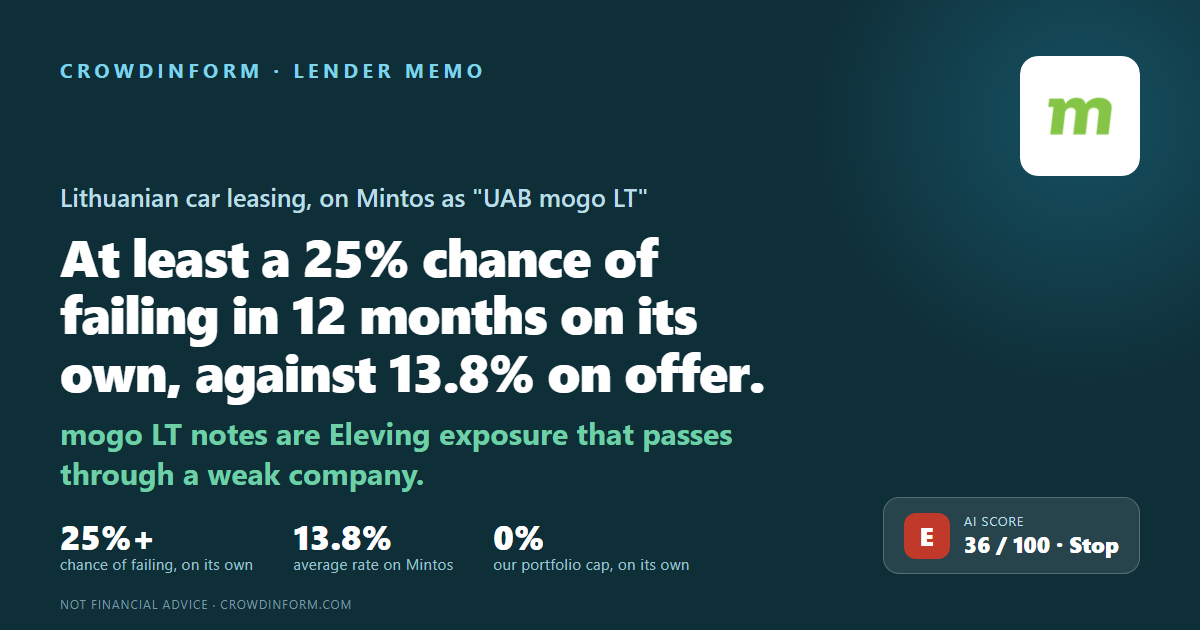
Lituania
Capital en riesgo. El tipo está pactado, no garantizado: si un prestatario incurre en impago, puede perder una parte o la totalidad de su dinero.
Nuestra IA da a este proyecto 36 de 100: Baja. Cómo funciona la puntuación de la IA
Información, no asesoramiento personalizado de inversión. La puntuación IA valora los documentos que publica la plataforma, puede equivocarse y no predice la rentabilidad.
UAB mogo LT lends against cars in Lithuania — leasing and leaseback, an average loan of €8,029 over fifty-seven months, at annual rates from 26% to 90%. It has thirty-one staff in Vilnius, fourteen fewer than a year ago, and has been on the Bank of Lithuania's public list of consumer credit providers since the end of 2012. It belongs to Eleving Group, and it owns all of a second Lithuanian company, UAB Renti. Mintos investors buy notes issued against its loans. This memo asks one question: what is the chance it fails to pay its lenders back in the next 12 months, and why.
The marks come to 36, which would be a D. They are not what decides this memo. One automatic veto applies. mogo LT has lent 9.3 times its own cushion to its subsidiary Renti, on its audited 2025 accounts — our line is half. That alone makes this an E and sets the odds at 1 in 4 or worse. A second veto in our October memo, a going-concern doubt in the 2024 audit report, no longer applies: the audit report on 2025, signed on 22 April 2026, carries no such paragraph.
What changes the answer is the parent. Mintos's own base prospectus for these notes states that Eleving Group S.A. "guarantees to the Issuer the performance of Lending Company's obligations". Eleving is rated B by Fitch with a positive outlook, affirmed on 12 December 2025, and we found no rating action since. A confirmed guarantee from a rated parent is one of only two things in our method that improve the odds, and it replaces them with the parent's: about 1 in 33. The guarantee runs to the Mintos issuer, not to you directly.
So the honest summary is this. mogo LT notes are Eleving exposure that passes through a weak company. If you are comfortable lending to Eleving Group at about 13.8% you may be comfortable here; if the question you were asking was about mogo LT itself, the answer is the first number, not the second.
Six things would stop us scoring at all and send the answer straight to E — a default, a missed payment to a platform, a regulator pulling a licence, an auditor doubting the company can continue, a broken promise to a lender, or accounts we cannot rely on. One of them applies on its own accounts, and section 3 sets it out. Two things would pull the answer the other way, a guarantee from a stronger owner or a credit rating. One of them does apply, and it is the only reason this memo gives a second number.
Lost money in 2024 and 2025. Interest to its own lenders is larger than what it earns from customers.
A small car book in run-off, and getting worse as it shrinks: 12.8% of it was defaulted at the end of 2024. No arrears table for 2025.
The best country score we give. None of this company's problems come from its market, though the rate cap falls on 20 November 2026.
A conduit for group money, audited by a firm registered at the company's own address, and a guarantor of Eleving bonds many times its own size.
Every investment carries risk, and risk is not really a letter or a mark out of ten. It is two plain questions: how likely is it that this company fails, and how much of your money would you lose if it did. Put those together and you can see whether the reward is worth it.
For mogo LT there are two answers, and the difference between them is the guarantee. Taking the company on its own, at least a 25% chance of failing and about 30% of the money coming back: the risk costs roughly 17.5% a year against an average investor rate of 13.8% — more than the rate pays. Taking Eleving's guarantee at face value, about a 3% chance: the risk costs roughly 2.1% a year, leaving about 11.7 points. Those are not small differences of degree. They are different investments, and which one you are making depends on a guarantee given to the Mintos issuer rather than to you.
An advertised 10% is what you are promised if everything goes well. What you keep is that rate minus what failures cost you. So the rate on its own tells you very little.
Risk cost = chance of failing × share of your money you would not get back. Nobody knows the second number in advance. How much comes back has varied widely from case to case. We use 30% back, 70% lost, as our own working assumption so that memos can be compared with each other — it is not a measured figure, and the answer moves a lot if you choose differently.
Take two imaginary lenders. One pays 14% but has a 17% chance of failing within the year: the risk costs about 11.9% a year, leaving roughly 2%. The other pays 9% with a 2.5% chance: the risk costs about 1.8%, leaving about 7%. The lower rate is the better deal. That is the whole idea.
On the Bank of Lithuania's public list, registered 31 December 2012. We read the Bank's own entry on 12 October 2026. It takes no deposits.
Wholly owned, within Eleving Group, which is rated B by Fitch with a positive outlook, affirmed 12 December 2025. mogo LT in turn owns all of UAB Renti.
An average car loan of €8,029 over fifty-seven months, at annual rates from 26% to 90%. Thirty-one staff in Vilnius.
Gross, at June 2025, on its own balance sheet; the Mintos prospectus puts gross receivables at €3.1m. Interest income was €3.08m in 2025, down 9%. Owners' money €1.52m.
Read on 9 November 2026, down from €0.8m on 13 September (see the update at the top), at an average investor rate of 13.8%, with a Mintos Risk Score of 9.4 updated on 9 October 2026 (loan performance 10.0, servicing 10.0, buyback 9.3, structure 6.0). Notes are issued by SIA Mintos Finance No. 1. All platform figures are Mintos's own.
The underlying receivables are pledged to the issuer, and Eleving Group guarantees mogo LT's obligations to the issuer — not to investors directly.
El análisis completo cubre al prestatario o la empresa, la garantía, el flujo de caja, los riesgos y un veredicto. Inicie sesión para leerlo.
Información, no asesoramiento personalizado de inversión. La puntuación IA valora los documentos que publica la plataforma, puede equivocarse y no predice la rentabilidad.
Inicie sesión para preguntar a la IA sobre los documentos de este proyecto.
Iniciar sesión👍 Sí · 0 👎 No · 0
Enlace de afiliado · capital en riesgo
Ver 42 proyectos →Mintos
Mintos
Mintos