Regulated
- Risk level
- High
- Risk-return
- Medium
- Start from
- €500
Questions about investing? Ask the AI guide.
Hi! I'm the Crowdinform AI guide.
Sign in free to ask the AI guide about platforms, projects and your plans.
Answers come from Crowdinform's checked data. Information, not personal investment advice.
Looking it up… Something went wrong. Please try again. {n} questions left todayFunding closed on 30 Sep 2026. The page stays up for reference; similar open projects are below.
France
The platform estimates 1.3–4×
Usually only if the company is sold or listed. Estimates are the platform's own claims.
Around 2031
Only if a sale or listing happens; shares are hard to sell before that.
Capital at risk. Most startups fail; estimates are the platform's own claims. Shares are hard to sell before an exit.
Our AI gives this project 65 out of 100: Medium. How the AI score works
Information, not personal investment advice. The AI score rates the documents the platform publishes, can be wrong, and does not predict returns.
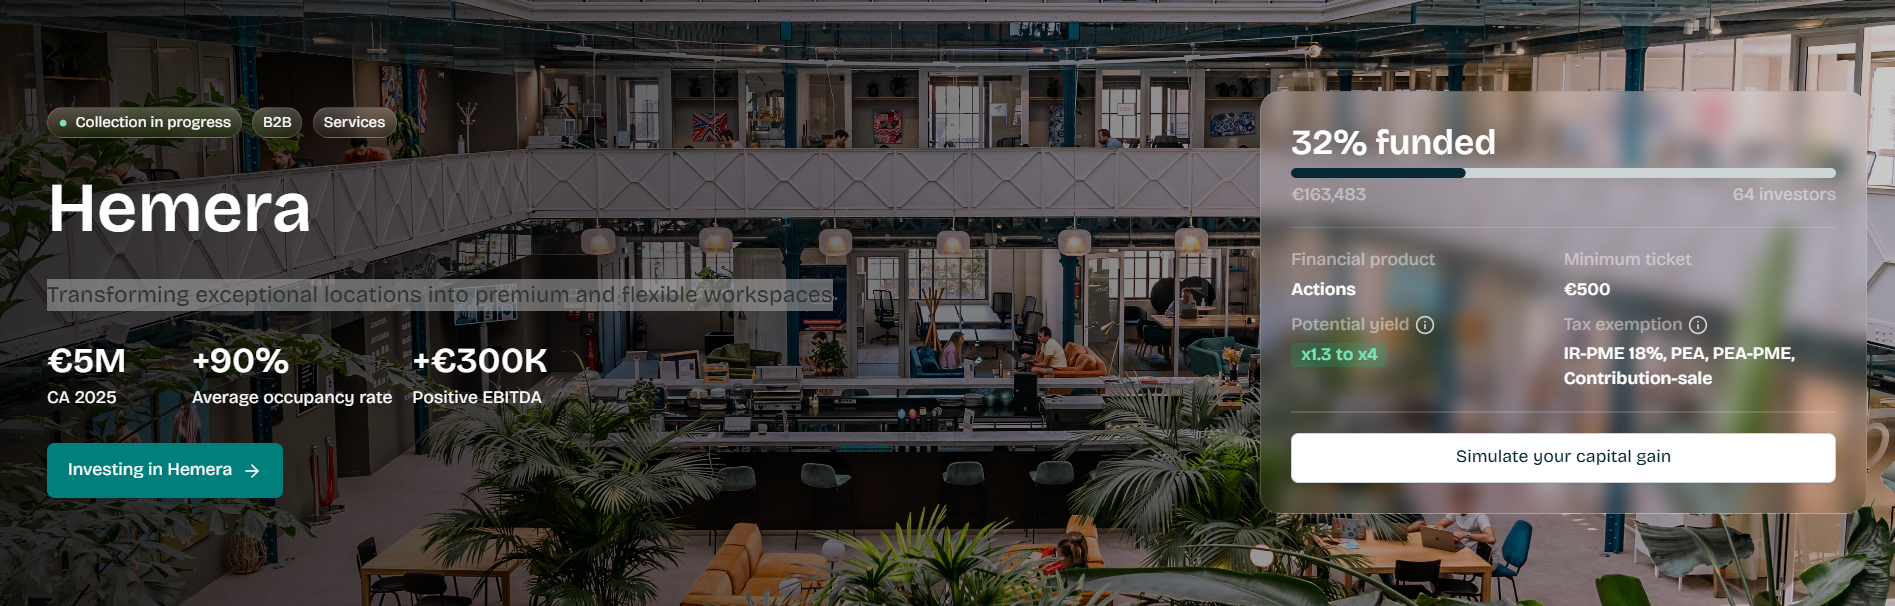
Operator that converts character buildings in south-west France into premium, flexible workspaces (offices, coworking, events, catering).
Sector: Flexible office / coworking (NACE 55.90) · Stage: Development capital (Cap Dev) · HQ: Bordeaux, France · Raise: €500K–€1,500K (equity)
|
|
Why this score: |
|
AI SCORE |
|
|
65 / 100 |
|
|
⭐ Moderate |
|
|
|
|
|
|
|
|
ℹ️ This is not investment advice. The purpose of this overview is to help potential investors preselect crowdfunding projects quickly without making a final investment decision. Before investing, the final selected project should be reviewed in detail based on the information provided by the company on the respective crowdfunding platform. AI can make mistakes, so you need to double-check data. |
🏢 Company description
HEMERA is a Bordeaux-based operator (SAS, RCS Bordeaux 818 141 459) that identifies, transforms and runs character buildings as premium flexible workspaces combining private offices, coworking, events and catering on short, no-commitment contracts. The company was incorporated in 2016 and opened its first site in 2019; public sources (Rue89 Bordeaux) confirm an earlier ~€2M raise in 2017. By end-2025 the company reports 9 operating sites across five cities in Nouvelle-Aquitaine (~13,370 m², 212 hosted companies, ~1,100+ active coworkers, 27-month average tenure). Revenue reached €5.0M in 2025 (+45% versus 2024) per the FICI, though the year closed with an operating loss of €82k and a net loss of €135,071. The business is structured as an OpCo/PropCo split: HEMERA (the company you invest in) operates the sites, while a separate founder/family-controlled property company (SAS Parrou-Duboscq) owns the buildings, carries the bank debt and the heavy works, and leases to HEMERA — keeping HEMERA capital-light but creating a related-party rent. The €500K–€1.5M round is raised via Tudigo to fund new-site openings (57%) and to absorb each new site's ramp-up phase (43%); founders are Julien Parrou-Duboscq (a serial entrepreneur who took ConcoursMania to an IPO) and Benoît Droulin (ex-DG of ORSYP, co-founder of Azendoo).
|
Target return |
Time horizon |
Target basis |
AI view on reaching this goal |
|
🎯 2.5x |
⏱ 3–5 yrs |
Company-provided — the company set its own 2.5x / 5-year target (Middle scenario), built on a forward EBITDA multiple and comparable transactions. |
Plausible only if multiple new sites open and ramp to a normative (not yet realised) margin; the 2025 net loss and related-party rent dependence make it uncertain. |
|
Company methodology |
Market multiples applied to projected 2031 normative EBITDA (the margin sites are assumed to reach at maturity), cross-checked against comparable transactions. Middle scenario: exit at 6.9x normative EBITDA of €1.9M ⇒ ~€16.2M exit valuation ⇒ 2.5x on a €5.5M pre-money entry. |
|
Comparable exits cited |
|
| Sample (n=5) VE/EBITDA: mean 6.39x, median 6.90x; multiple retained 6.90x. Sources: CFNews, PitchBook. | |
|
Milestones expected |
|
|
Pre-money valuation |
€5.5M (on a non-fully-diluted basis, per the LOI). |
|
Post-money valuation |
€6.0M at the €0.5M floor; €7.0M at the €1.5M cap. |
|
Instrument |
Equity — ordinary shares at €40/share (€1 nominal + €39 premium), held via the Tudigo nominee SPV. |
|
How the valuation was set |
Forward multiple (6.9x) on 2031 normative EBITDA plus comparable transactions. The normative EBITDA is, by the company's own statement, higher than its accounting EBITDA because sites are assumed at full maturity in 2031. |
|
External benchmarks |
Comparable office-flex exits cited at $330M–$800M for far larger operators; used to justify the 6.9x exit multiple rather than to set the pre-money directly. |
|
Notable terms |
Entry pre-money €5.5M is ~18x trailing 2025 accounting EBITDA (€301k); 2025 net result was a loss. Tax relief available (IR-PME 18%, PEA/PEA-PME, 150-0 B ter), requiring a 5-year (or 7-year) hold. |
📜 Instrument & investor terms
You buy ordinary shares — the most basic form of company equity, ranking behind any preferred shares — but you do not hold shares in HEMERA directly. Instead you hold shares in a nominee vehicle, TUDI HOLDING 163 (an SPV, or special-purpose vehicle: a company created solely to pool crowd investors and hold the HEMERA stake on their behalf). Inside the SPV one share carries one vote, but the SPV as a single block is what votes at HEMERA's level, so your influence over HEMERA itself is effectively nil. The historic institutional investors hold preference shares with priority rights; the crowd does not. Exit decisions are therefore made by HEMERA's board and major shareholders, with the SPV bound to follow the shareholders' agreement — including a clause that can force the crowd to sell (see Exit mechanics).
The company's fin…
The full review covers the borrower or company, the security, the cash flow, the risks and a verdict. Sign in to read it.
Information, not personal investment advice. The AI score rates the documents the platform publishes, can be wrong, and does not predict returns.
Sign in to ask the AI about this project's documents.
Sign in👍 Yes · 0 👎 No · 0
Sowefund
Raising €9m
Sowefund
Raising €600k
Sowefund
Raising €750k